Private Credit Pulse
BiweeklyJuly 14, 2026

Private Credit Pulse June 30, 2026

6.30PrivateCredit1.jpg
6.30PrivateCredit2.jpg
6.30PrivateCredit3.jpg
6.30PrivateCredit4.jpg
6.30PrivateCredit5.jpg
6.30PrivateCredit6.jpg
6.30PrivateCredit7.jpg
6.30PrivateCredit8.jpg
6.30PrivateCredit9.jpg
6.30PrivateCredit10.jpg
6.30PrivateCredit11.jpg
6.30PrivateCredit12.jpg
6.30PrivateCredit13.jpg
6.30PrivateCredit14.jpg
6.30PrivateCredit15.jpg
6.30PrivateCredit16.jpg
6.30PrivateCredit17.jpg
5.19PrivateCredit18.jpg

Executive Summary

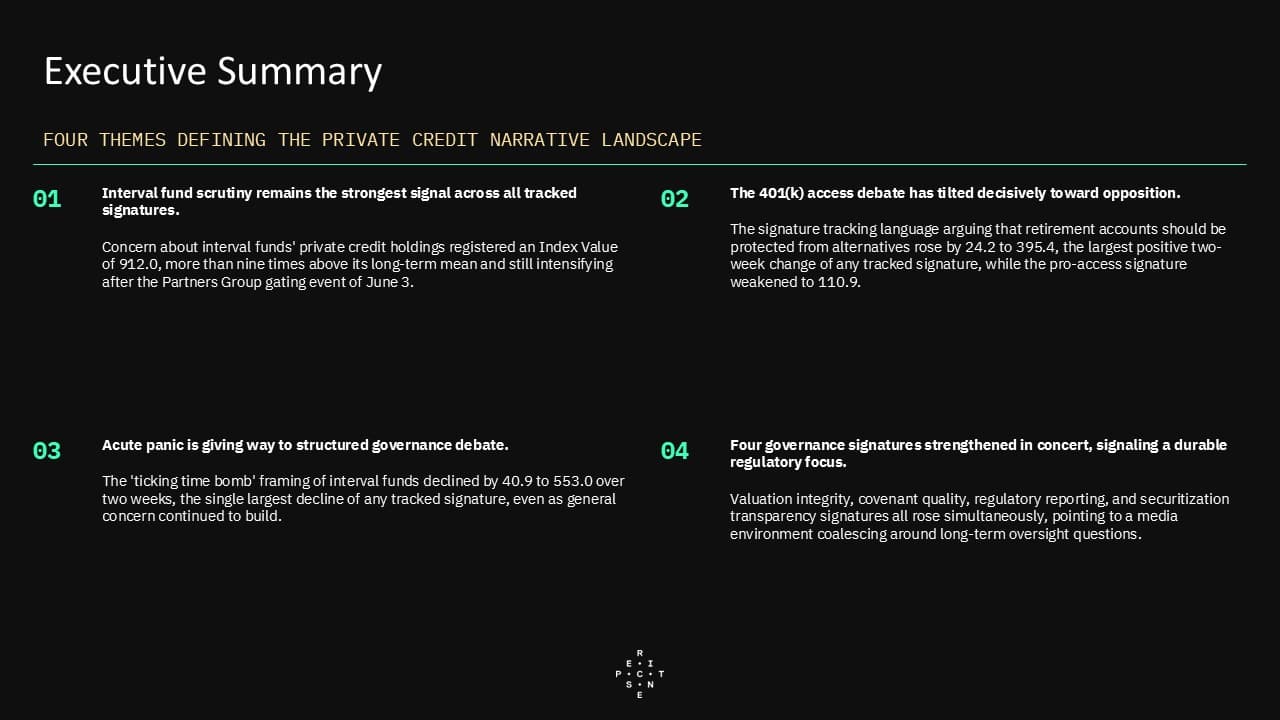
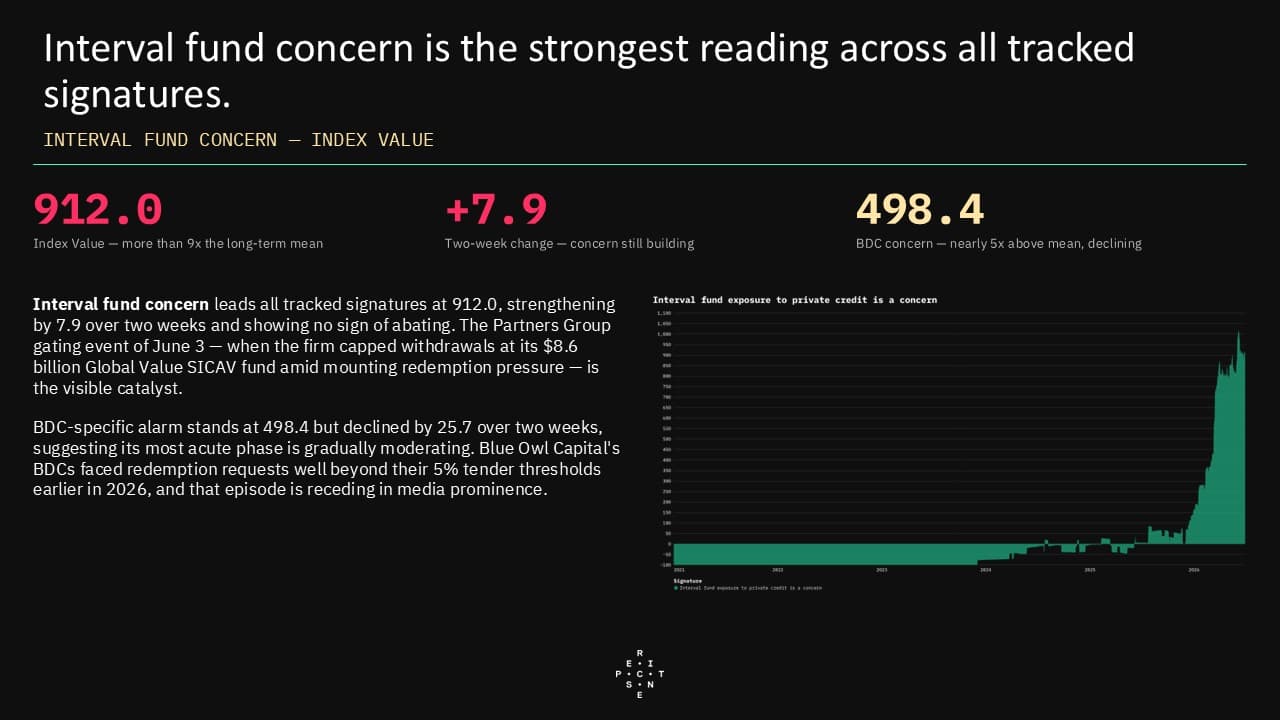
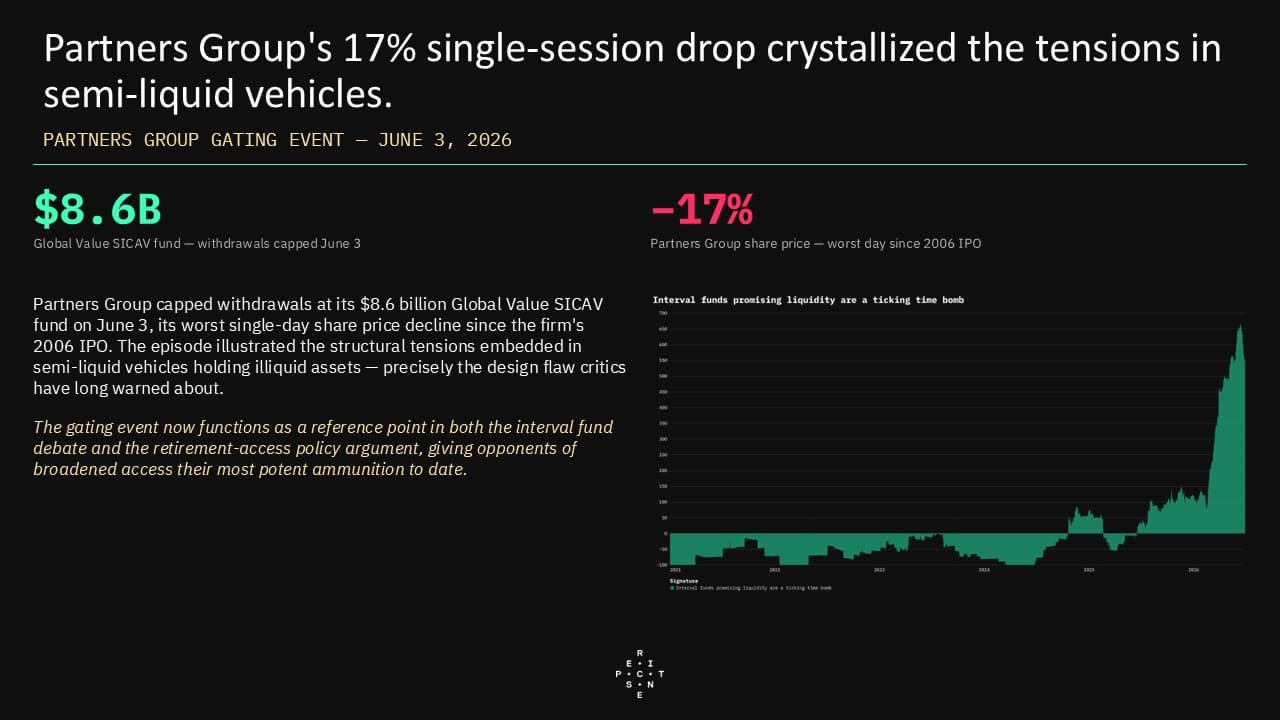
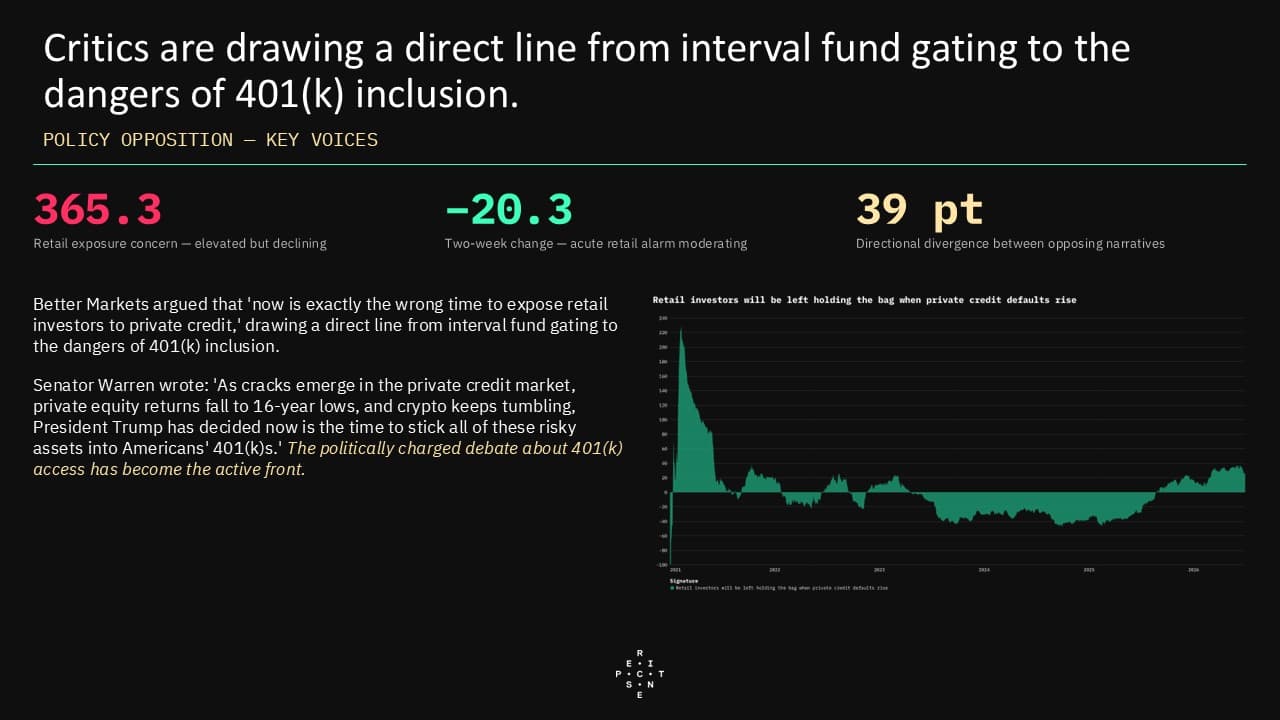
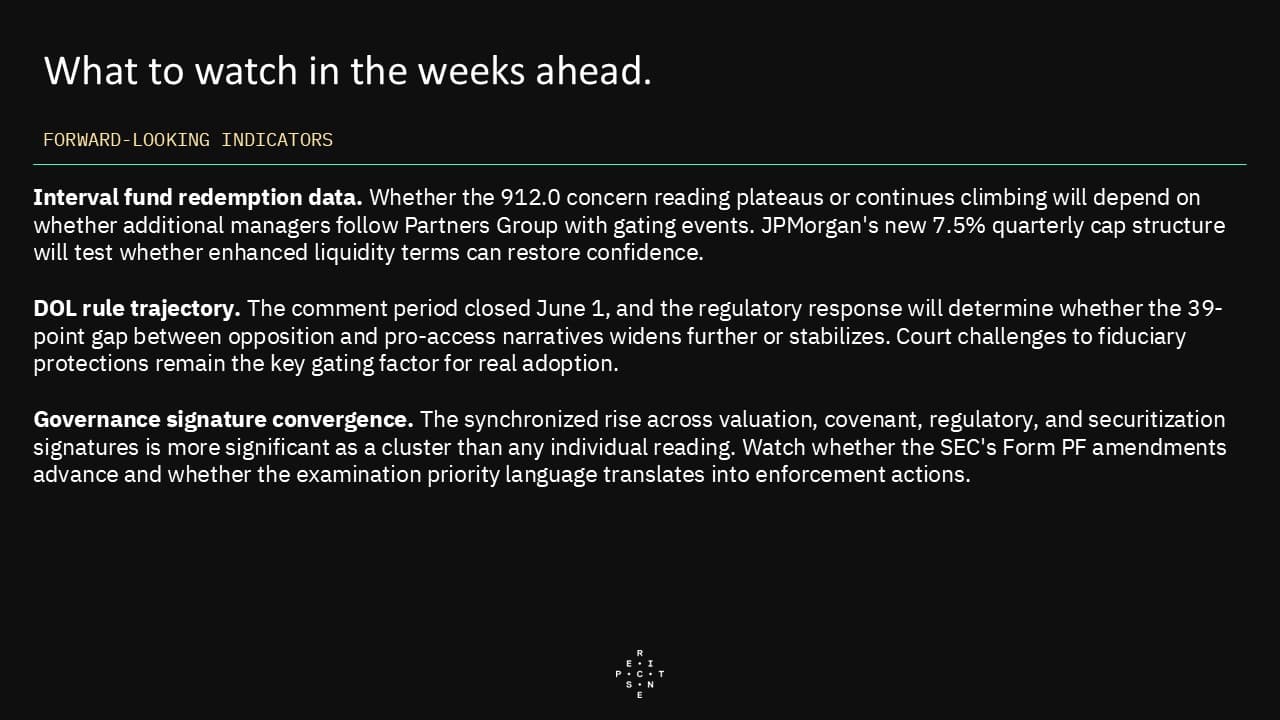
  • The Partners Group gating event of June 3 has created a two-front media problem for the private credit industry, sustaining record-level scrutiny of interval fund structures while simultaneously providing opponents of the DOL's proposed 401(k) alternative-access rule with their most potent ammunition to date. Perscient's semantic signature tracking concern about interval funds remains the strongest reading across all tracked signatures, and the interval fund redemption experience is now cited directly in policy arguments against broadening retirement account access to alternatives.
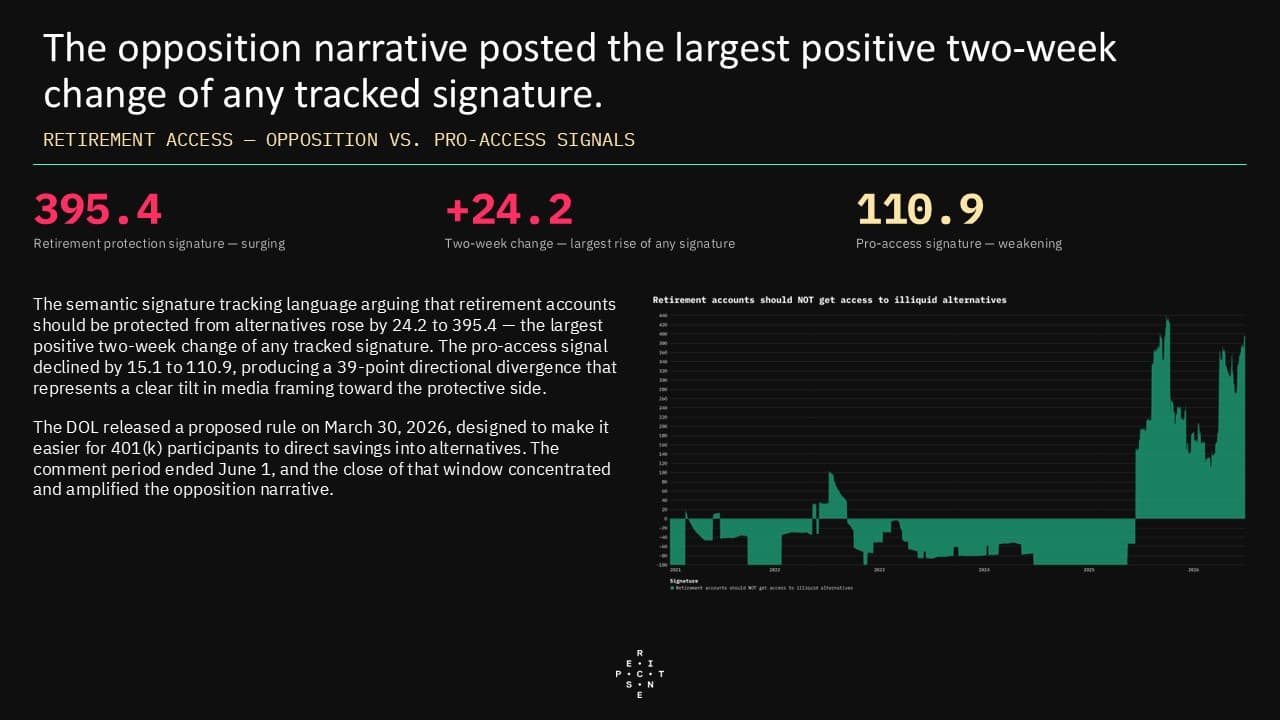
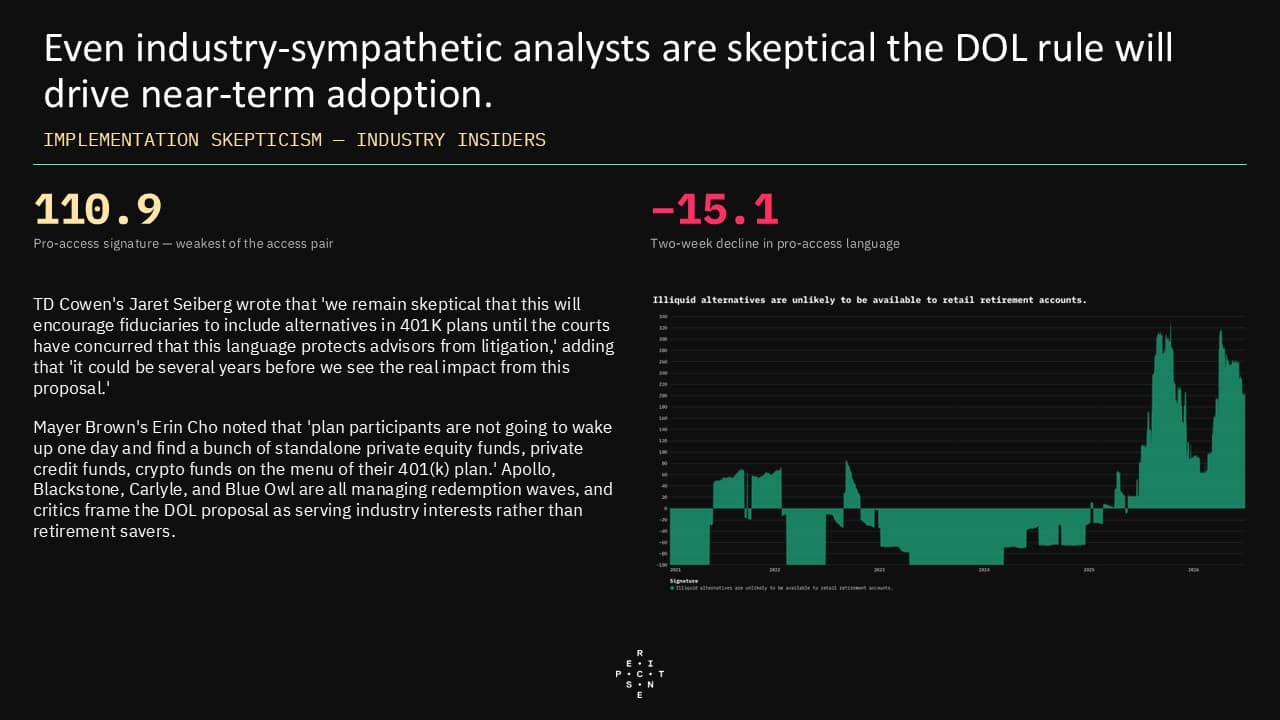
  • Media framing of the 401(k) debate has tilted decisively toward opposition. The semantic signature tracking language arguing that retirement accounts should be protected from alternatives registered the largest positive two-week change of any tracked signature, while the pro-access signature weakened—a directional divergence that underscores the degree to which cautionary voices currently dominate the retirement access conversation. Even some industry-sympathetic analysts have expressed skepticism that the proposed rule will lead to near-term adoption.
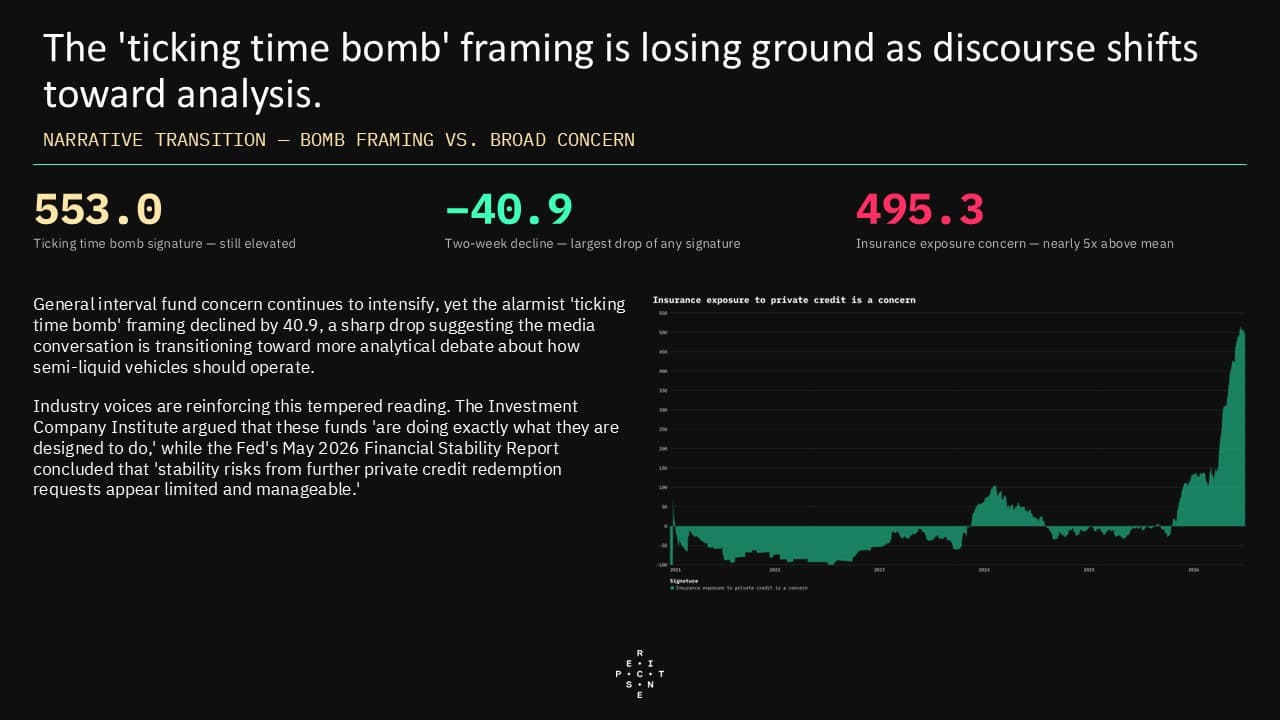
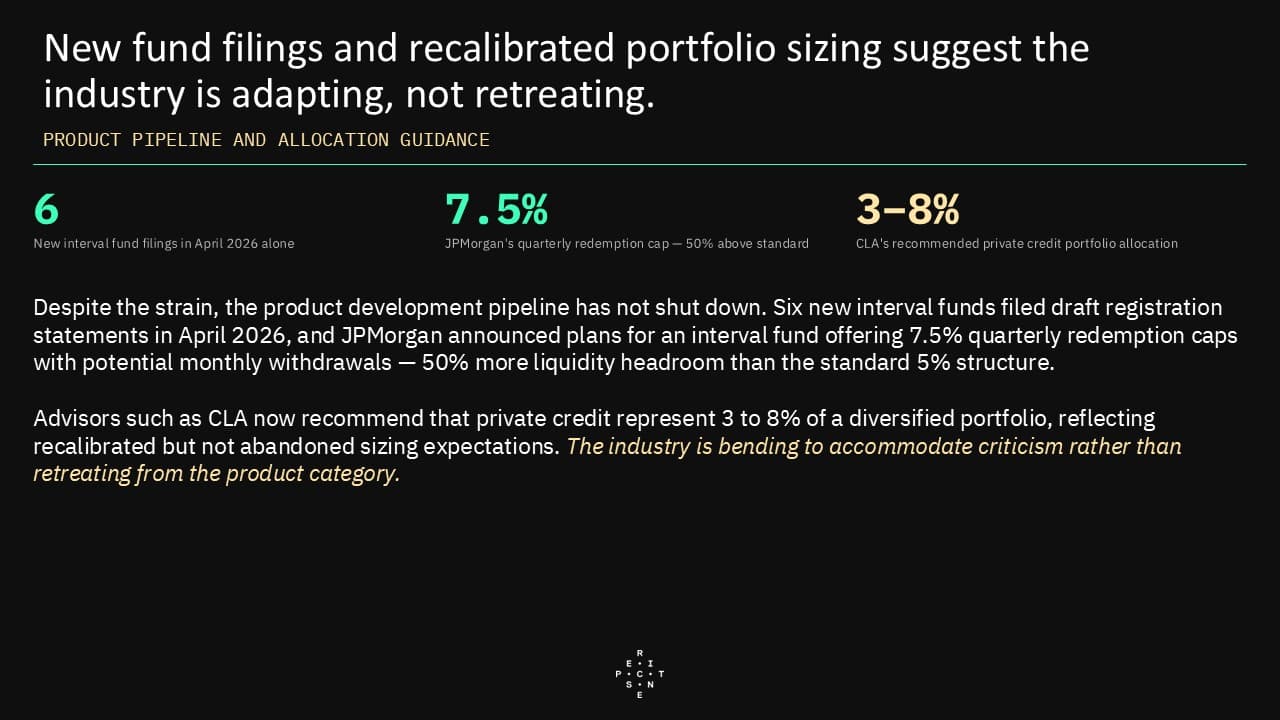
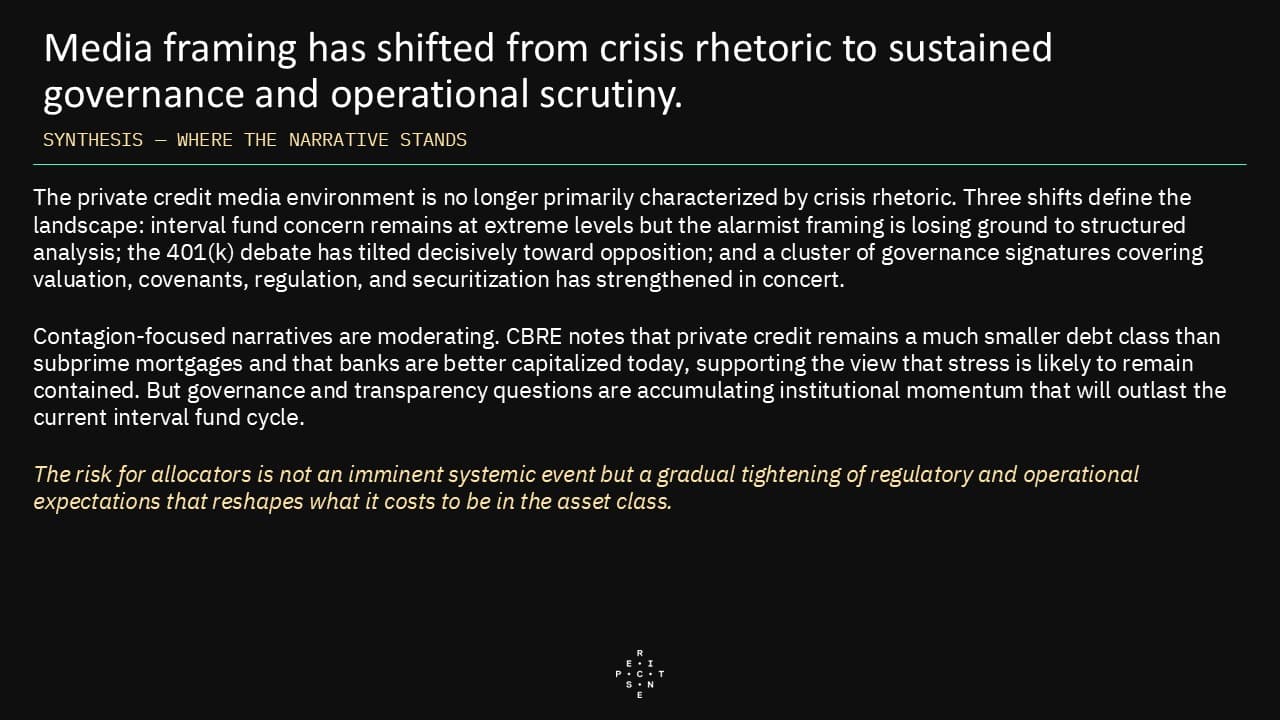
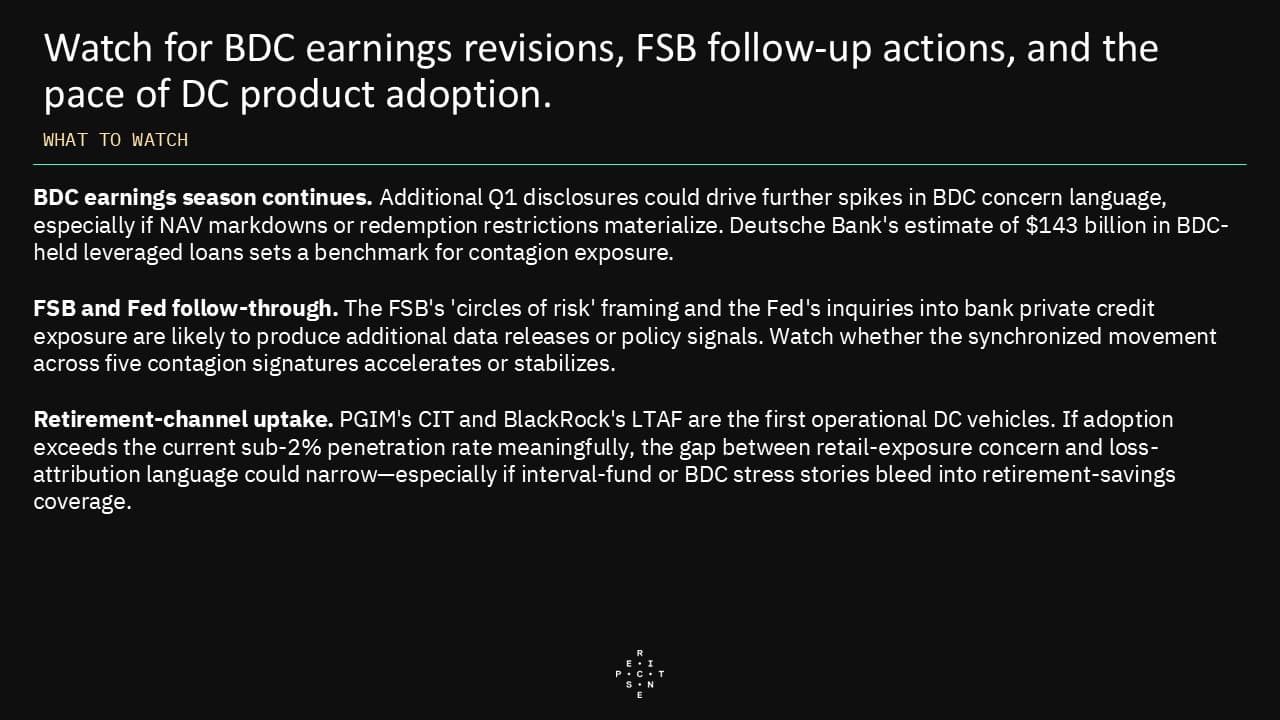
  • Although interval fund concern remains at extreme levels, the media conversation is undergoing a qualitative shift. The "ticking time bomb" framing of interval funds recorded the single largest decline of any tracked signature over the two-week period, suggesting that discourse is transitioning from acute panic toward more structured, analytical debate about how semi-liquid vehicles should operate. Industry defenders are gaining traction with arguments that gating mechanisms are functioning as designed, new fund filings continue, and the Federal Reserve has characterized stability risks as manageable.
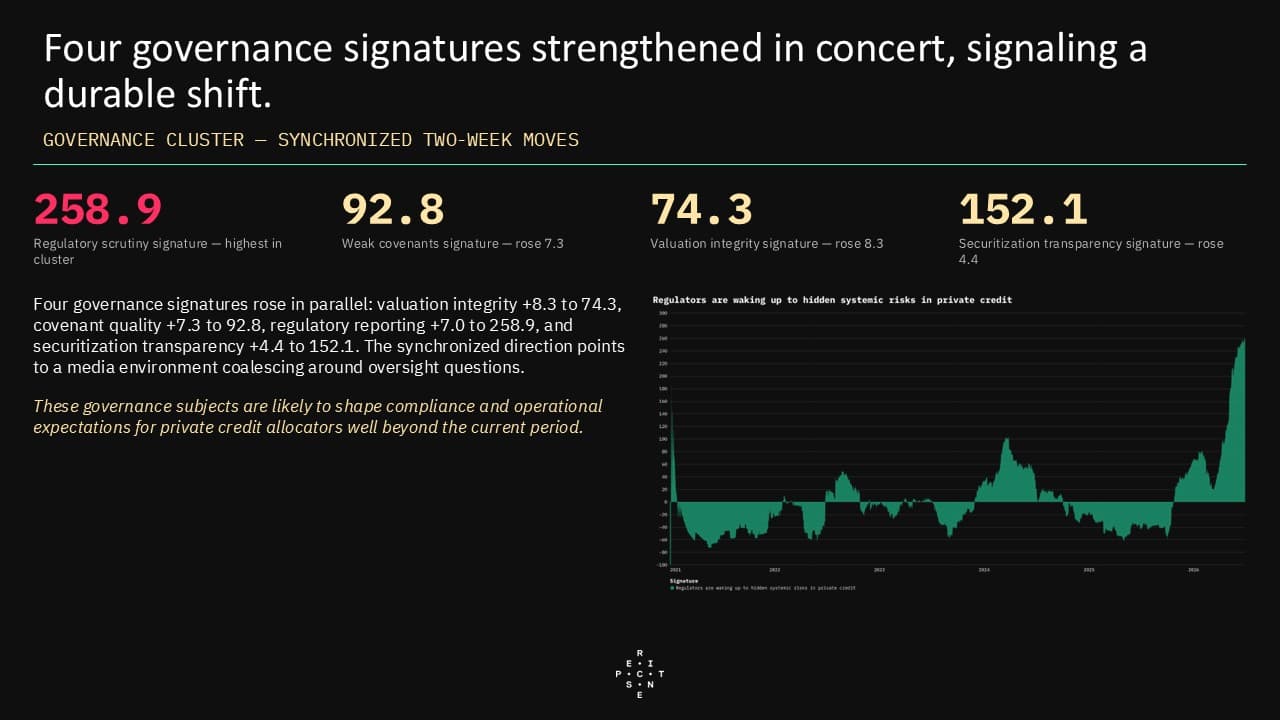
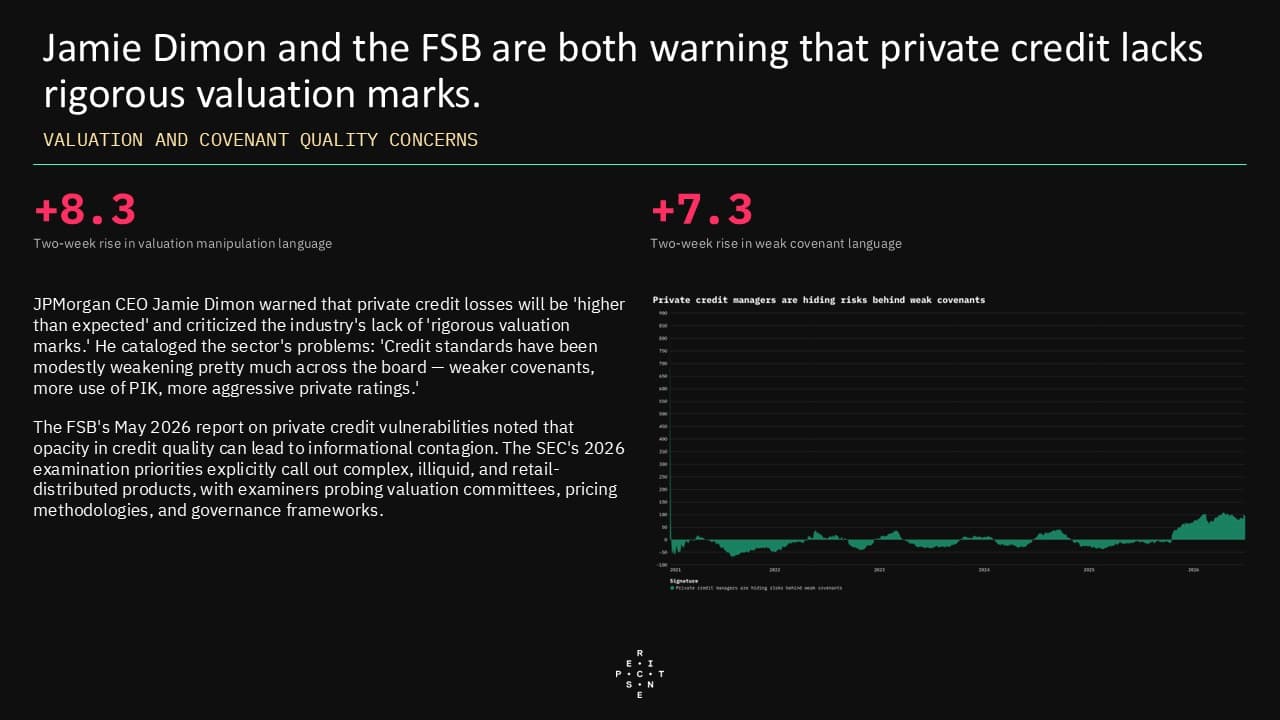
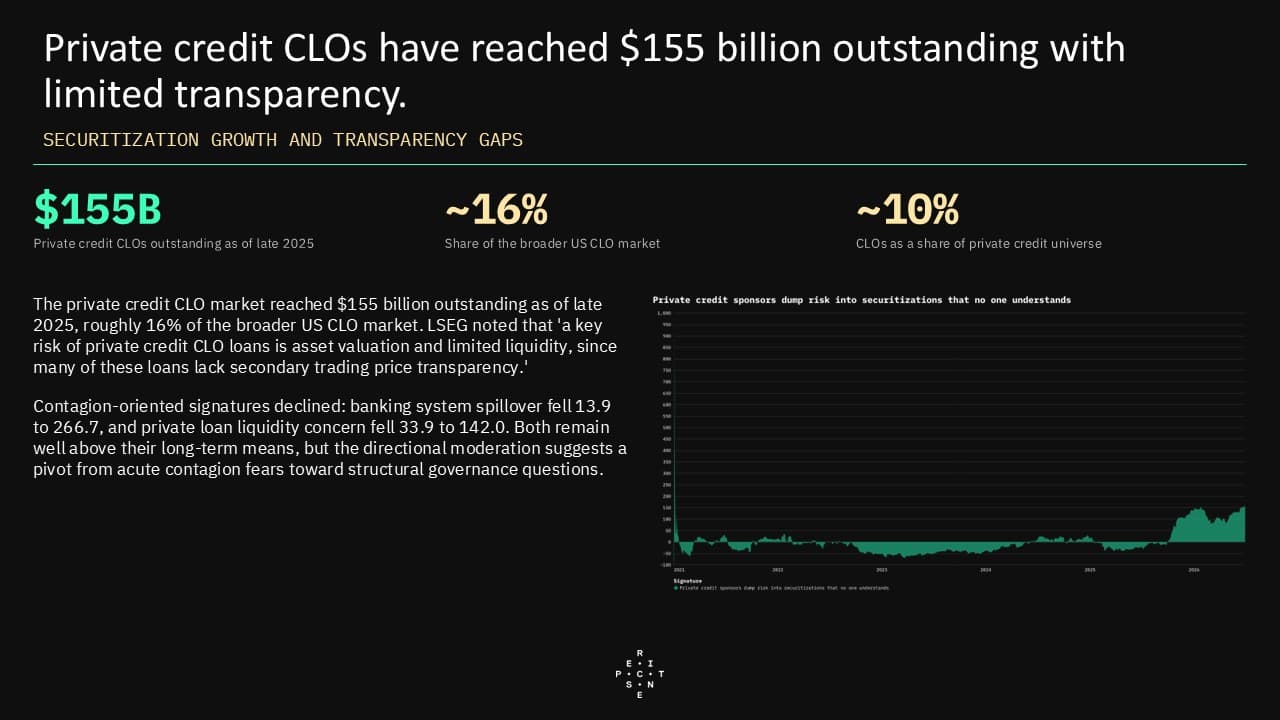
  • A quieter but potentially more consequential development is the synchronized strengthening of four governance-related semantic signatures covering valuation integrity, covenant quality, regulatory reporting, and securitization transparency. This coordinated movement, alongside moderating contagion-focused narratives—such as those warning about banking system spillover or private loan liquidity evaporation—indicates that financial media is increasingly framing private credit risk as a long-term regulatory and operational challenge rather than an imminent systemic threat. These governance subjects are likely to shape compliance and operational expectations for private credit allocators well beyond the current period.

Recent Pulses

Markets PulseWeeklySep 22, 2026

Markets Pulse September 15, 2026

The regime-change story arrives without any accompanying fear language. Every flight-to-safety signature — Treasurys, Swiss franc, yen, gold, money market funds — sits deep in negative territory, geopolitical and monetary policy uncertainty signatures were flat, and risk-on and risk-off readings have converged to nearly the same level just below zero. Media are narrating a supply shock, a five-percent ten-year, and a first hike since 2023 while conspicuously declining to counsel defensive positioning. Election-season transfer proposals collided with a hardening sovereign-risk story, and media asserted both outcomes at once. The helicopter-money signature registered the largest single move in the file, and stimulus-check predictions rose with it, yet signatures tracking debt paydown, deficit reduction, and austerity legislation also strengthened in the same week, while fiscal policy uncertainty remained flat. Commentators are expressing conviction about incompatible fiscal futures rather than doubt. Simultaneously, signatures tying runaway spending to higher Treasury yields, and those linking bond weakness to deficits and unfunded tax cuts, all gained, and claims that Treasurys are pricing genuine default risk moved into positive territory. Taken together, Sections 1 and 2 describe a media framework in which monetary and fiscal policy are pulling in opposite directions. Coverage pairs a hawkish Fed responding to oil-driven inflation with a proposed trillion-dollar household giveaway, and the reserve-currency channel sharpened alongside it: the signature tying dollar-status threats specifically to debt sustainability rose while the generic version held flat. Claims that White House pressure on foreign Treasury holders is deterring buyers remain the densest reading in the entire file, even as it eased slightly, and official-sector gold substitution language stayed elevated without accelerating further. Tariff politics are running in reverse, and the war has been absorbed into the same affordability argument. The signature tracking broad public opposition to tariffs climbed to one of the highest standings in the file while claims of public support weakened further, and the stated rationale rotated decisively: reshoring-manufacturing arguments dropped hard while "make other countries pay their fair share" and negotiating-leverage framings gained. Directional language turned two-sided for the first time in months. Bridging Sections 1 and 3, voter coverage now treats tariffs and the conflict as a single price story, which the K-shaped-economy framing organizes into a midterm affordability fight — notably, the market version of that bifurcation narrative eased even as chip stocks sold off, and the argument that investors have no alternative to US large-cap growth has effectively vanished from coverage.

Markets PulseWeeklySep 22, 2026

Markets Pulse

Next release: September 29, 2026

Private Credit PulseBiweeklySep 22, 2026

Private Credit Pulse

Next release: October 06, 2026