Exclusive long and short form commentary for Perscient Pro members, offering insights into markets, policy, and narrative.
A Perscient exclusive product that reveals the deeper meaning of the stories shaping markets, events, and our world.
A Perscient exclusive research product synthesizing market narrative shifts with breaking news and high impact articles.
Actionable positions and trades created using Perscient's narrative intelligence platform
Access the complete archive of webinars led by Ben, available exclusively to Perscient Pro members with new sessions added.

By Epsilon Theory
|November 7, 2026
Post-election and post-market wipeout call, through the lens of what we’re seeing in narrative-world.

By Epsilon Theory
|November 3, 2026
Live example of how to build a systematic trading strategy from narrative virality and regime data.

By Epsilon Theory
|November 2, 2026
We had a market update Zoom call last Friday during our regularly scheduled Office Hours. As of today (Monday, Nov 2) it looks like we’re all just going to pretend that last Friday didn’t happen and/or doesn’t have any repercussions (“the midterms are a clearing event” lol), but I think this was a good conversation about the wipeout that’s happened across the tech world.

By Epsilon Theory
|October 29, 2026
Introduction to the Parallax platform, our flagship offering for a) new narrative virality and regime data, b) agentic reports discovering new connections between markets and narratives, and c) customized narrative reports on your equity and multi-asset portfolios.

By Epsilon Theory
|October 20, 2026
Ben Hunt of Epsilon Theory argues that the AI buildout is becoming too big to fail, with consequences for energy costs, credit markets, and consumers. His central question: who bears the cost when private investment becomes a national priority?

By Epsilon Theory
|October 1, 2026
September was another respectable month for the model portfolio, and we're staying net short going into October.

By Epsilon Theory
|September 11, 2026
A recording of our Office Hours call originally held on September 11, 2026.

By Epsilon Theory
|August 27, 2026
In this webinar, we tie together both the long-standing gold/credibility/de-dollarization trade and the long-standing private credit/insurance/systemic risk trade, using a recent tech breakthrough in measuring narrative virality and regime status to do it.

By Epsilon Theory
|August 3, 2026
Cliffs Notes on last week's World War AI Revisited webinar, plus model portfolio rebalancing for August.

By Epsilon Theory
|July 29, 2026
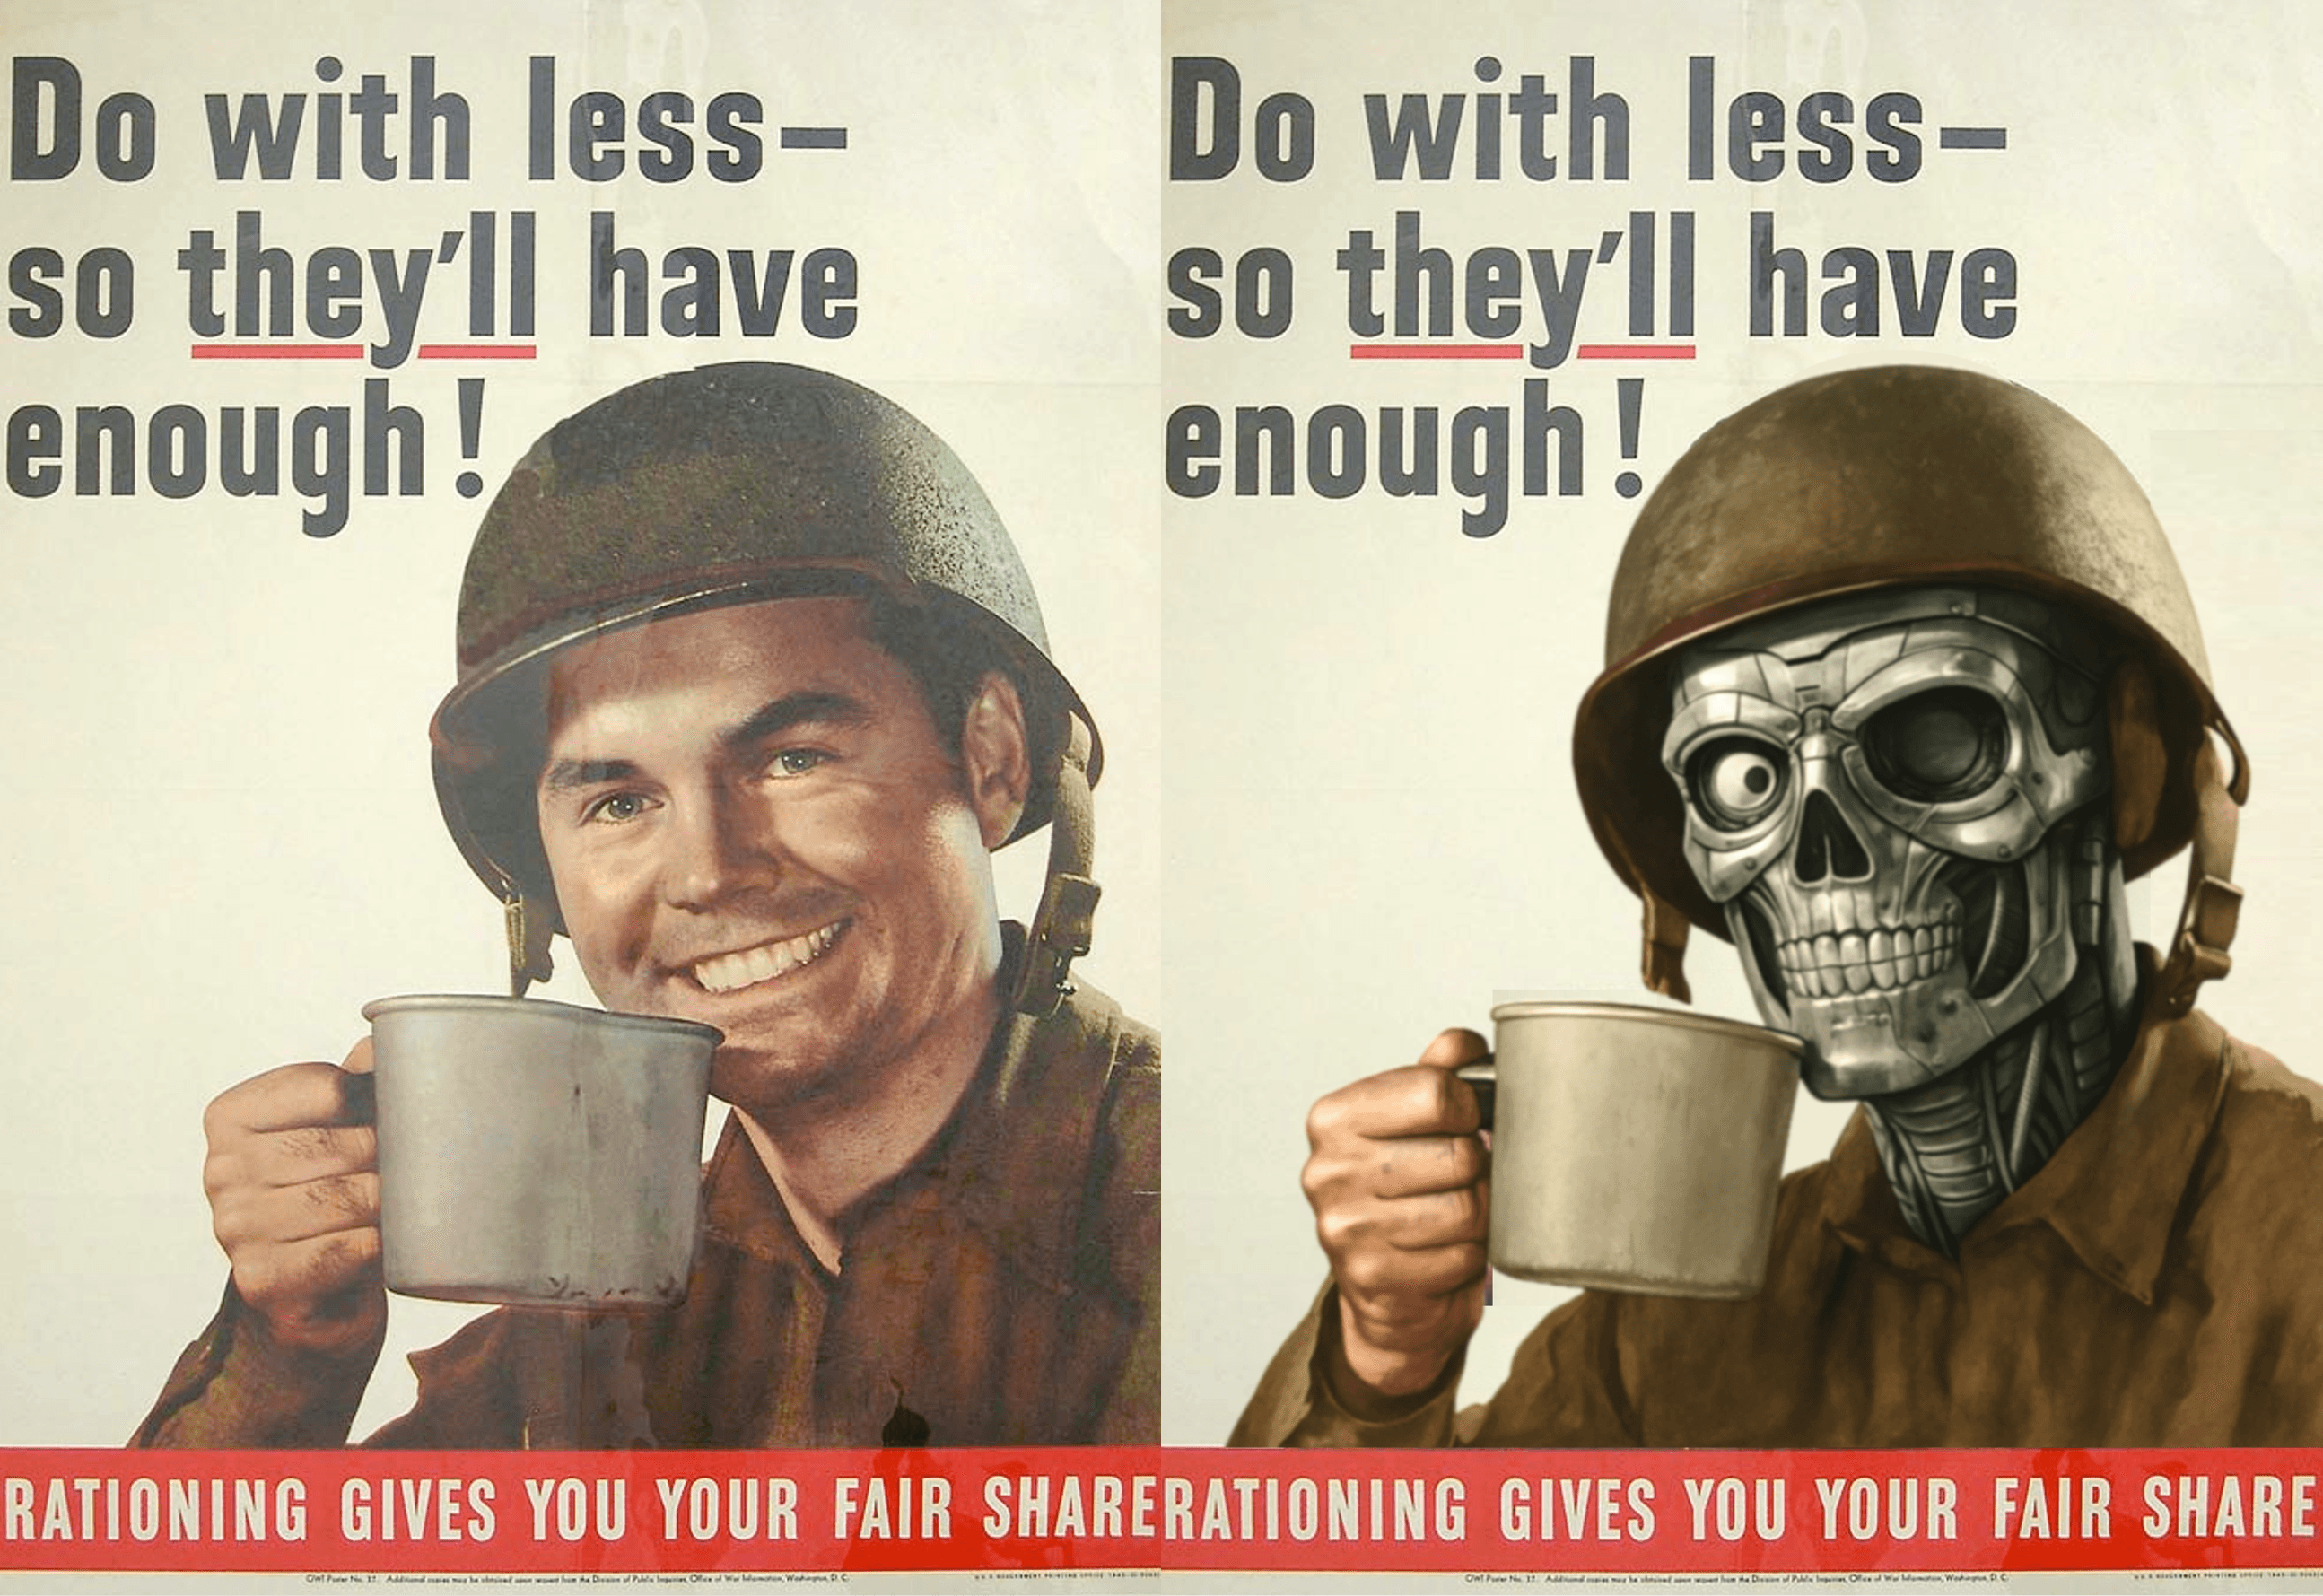
Last November, I published a note titled World War AI (attached and linked). It had one core observation – that the resource mobilization effort required for AI capex buildout plans in the US over the next few years rivals the resource mobilization effort of World War II – with two associated predictions:

By Epsilon Theory
|July 23, 2026
The resource mobilization effort required for AI capex buildout plans in the US over the next few years rivals the resource mobilization effort of World War II, and the associated shortages in capital, energy and labor are just now starting to bite.

By Epsilon Theory
|July 13, 2026
Do I think we’ll end up with the US taking a 20% toll on Hormuz cargos? No, that’s the typical crazy-high Trump opening bid. Do I think we’ll end up with the US taking something and the Iranians taking something and the Omanis taking something, so that the price of oil and everything else in the world is permanently higher than before the war? One million percent yes.

By Epsilon Theory
|July 9, 2026
We've built an extremely promising new dataset of methodologically reliable comparisons of market-moving central bank narratives across time and across countries. What we're seeing in Fed credibility narratives over the past year and the past eight weeks are pretty wild!

By Epsilon Theory
|July 1, 2026
It’s never easy to be net short in a portfolio, especially when you make the transition (because you’ll always get the timing wrong) and especially when you’ve got an election just a few months out (because every White House will juice the market and this particular White House will stop at nothing to juice the market), but net short is the right call here.
Meanwhile, back at the ranch, Apple is raising prices, oil inventories are at all-time seasonal lows, and if you’re not a communist on the Dem side or an election-denying Trumpist on the GOP side you can’t win a primary.

By Epsilon Theory
|June 17, 2026
As far as the model portfolio goes, I’ll just quote the immortal line from Airplane: looks like I picked the wrong week to quit sniffing glue. But I still think what I think.

By Epsilon Theory
|June 8, 2026
A recording of our open webinar for Pro and Parallax members to talk about dominant market narratives, from AI capex euphoria to the absurdity of the Iran War to the absolute exhaustion that all investors are feeling with all this, and take your questions on what we’re seeing across the narrative landscape.

By Epsilon Theory
|May 13, 2026
It’s not just that all of the bullish AI capex stories are getting louder. It’s also that all the bearish narratives around AI capex and AI-related company valuations have gotten much quieter.
The narrative dogs that don't bark are as important as the ones that do.

By Epsilon Theory
|May 8, 2026
In sharp contrast to every other country that we track, China is telling itself a powerful, self-confident story of economic strength across all macro narratives. China sees itself as the clear winner in its strategic competition with the US, and I don't think they're wrong.

By Epsilon Theory
|May 1, 2026
I'm back to shorting the US consumer everywhere I can, because I think consumer-related stocks are helpless if (when!) we get some bad news from the higher-for-longer oil prices, as there is no one in government – not the Fed and not the Treasury Secretary – with any credibility to jawbone significant narrative support.

By Epsilon Theory
|April 23, 2026
Middle-market companies are the engine of the US economy, and credit is the oxygen that keeps that engine firing. As the private credit securitization machine seizes up, I gotta ask: Is anyone still lending to middle market companies?