Private Credit Pulse
BiweeklyJune 30, 2026

Private Credit Pulse June 16,2026

6.16PrivateCreditPulse1.jpg
6.16PrivateCreditPulse2.jpg
6.16PrivateCreditPulse3.jpg
6.16PrivateCreditPulse4.jpg
6.16PrivateCreditPulse5.jpg
6.16PrivateCreditPulse6.jpg
6.16PrivateCreditPulse7.jpg
6.16PrivateCreditPulse8.jpg
6.16PrivateCreditPulse9.jpg
6.16PrivateCreditPulse10.jpg
6.16PrivateCreditPulse11.jpg
6.16PrivateCreditPulse12.jpg
6.16PrivateCreditPulse13.jpg
6.16PrivateCreditPulse14.jpg
6.16PrivateCreditPulse15.jpg
6.16PrivateCreditPulse16.jpg
5.19PrivateCredit17.jpg
5.19PrivateCredit18.jpg

Executive Summary

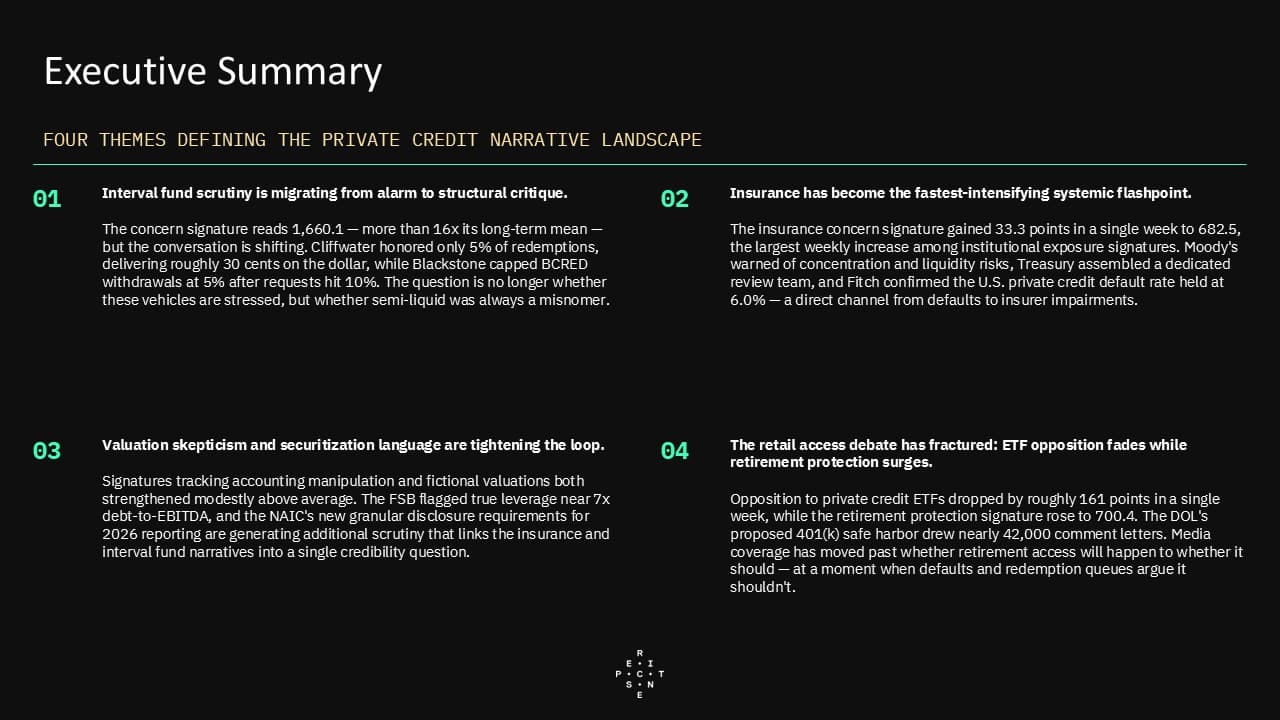
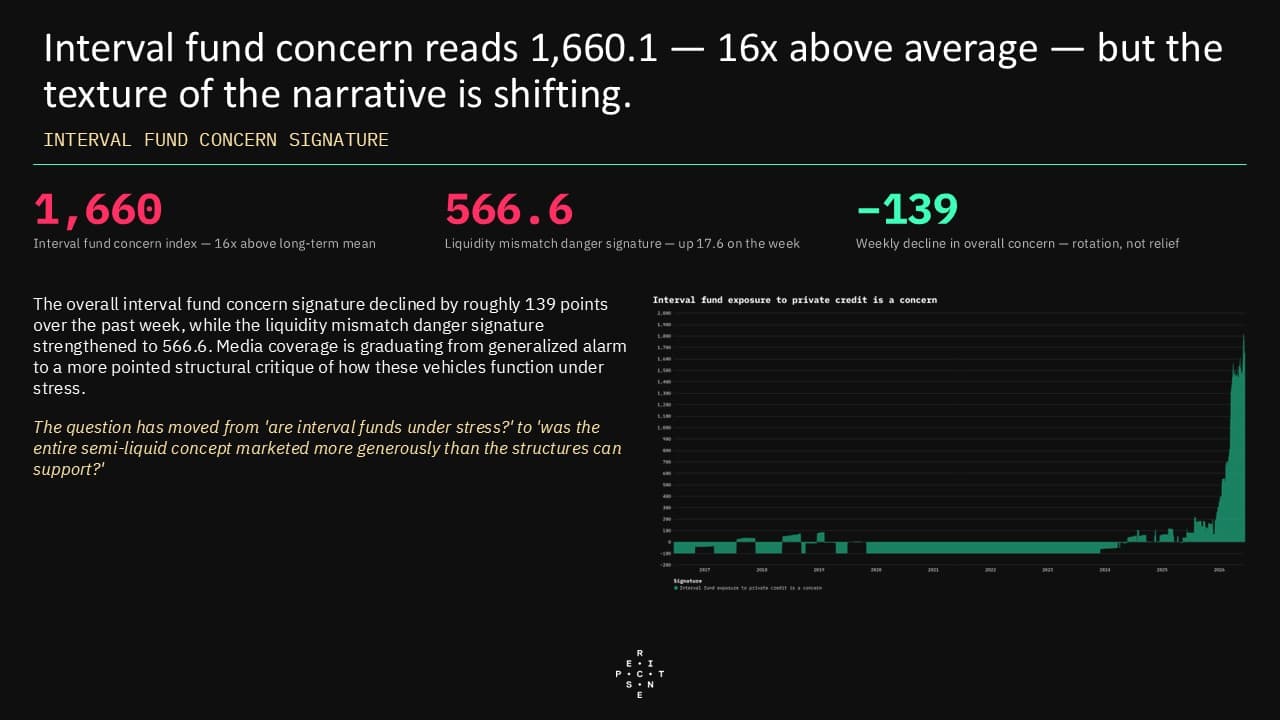
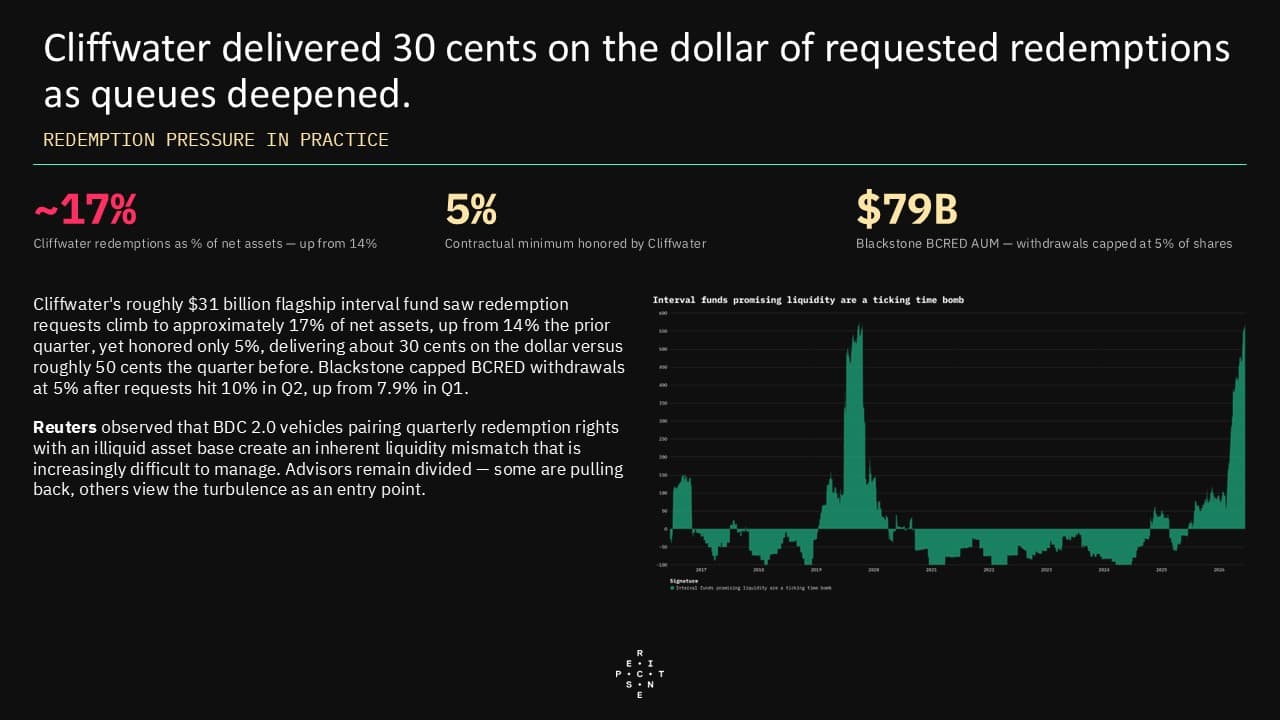
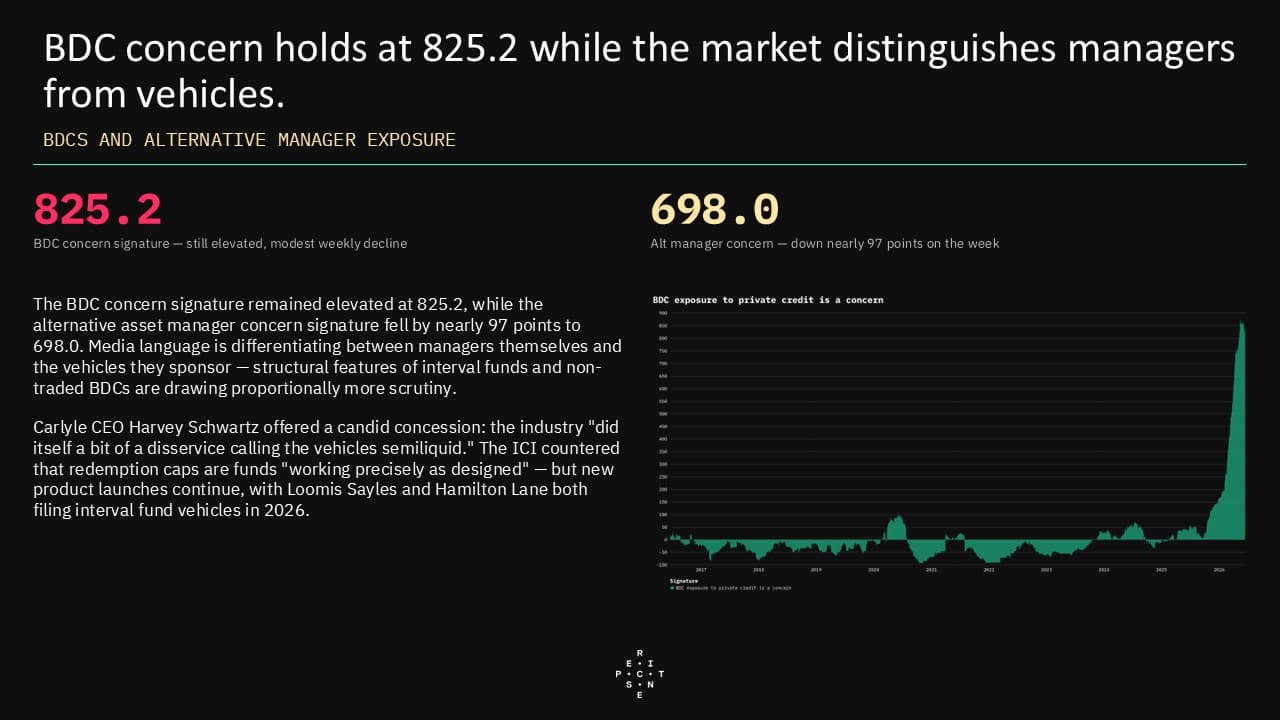
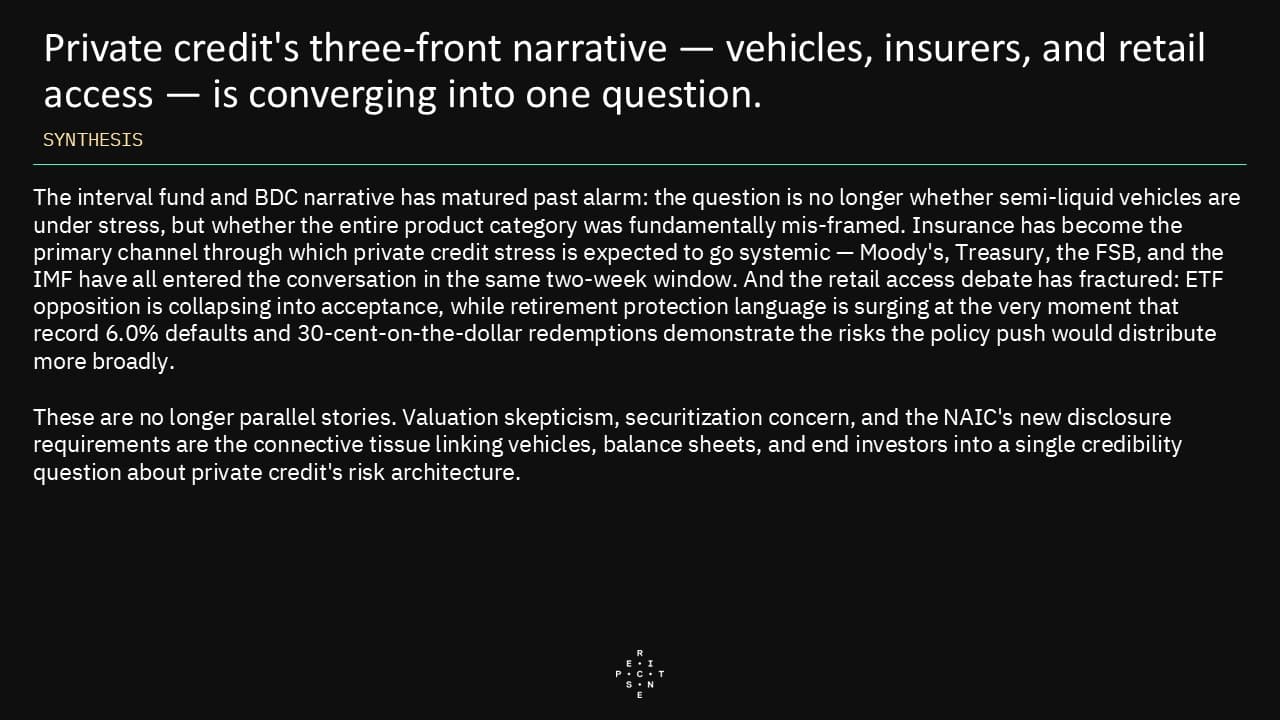
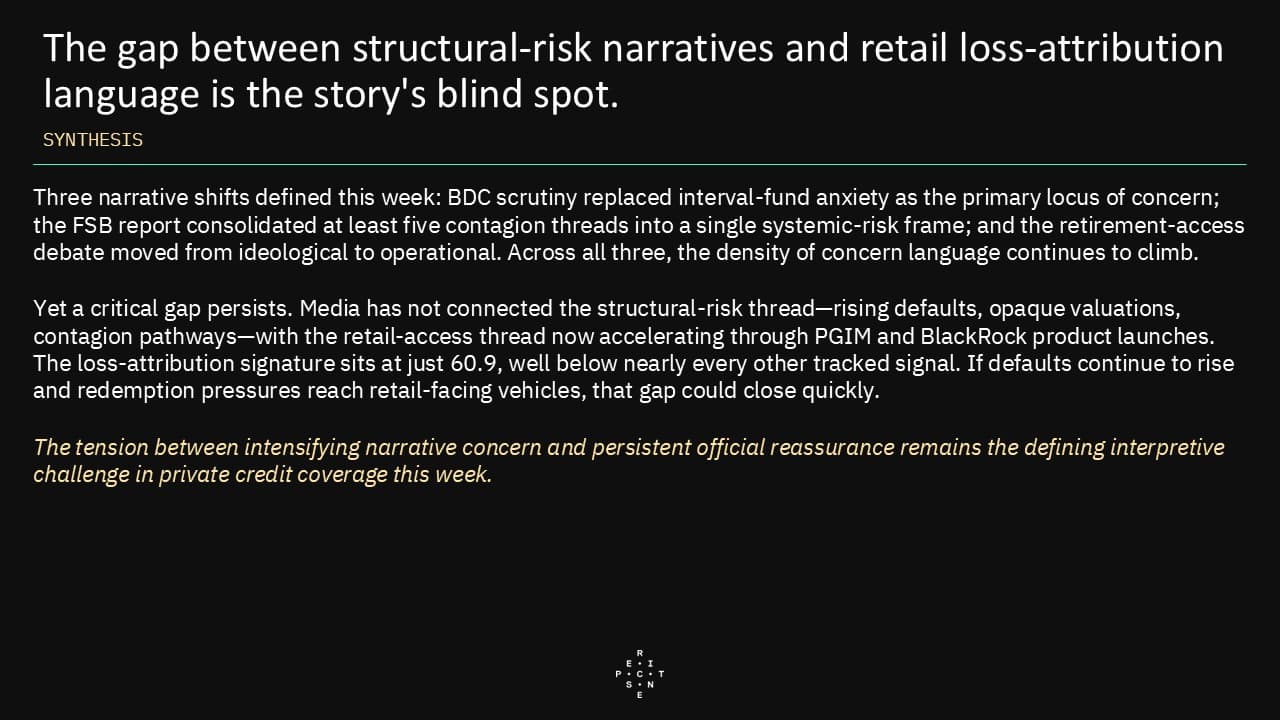
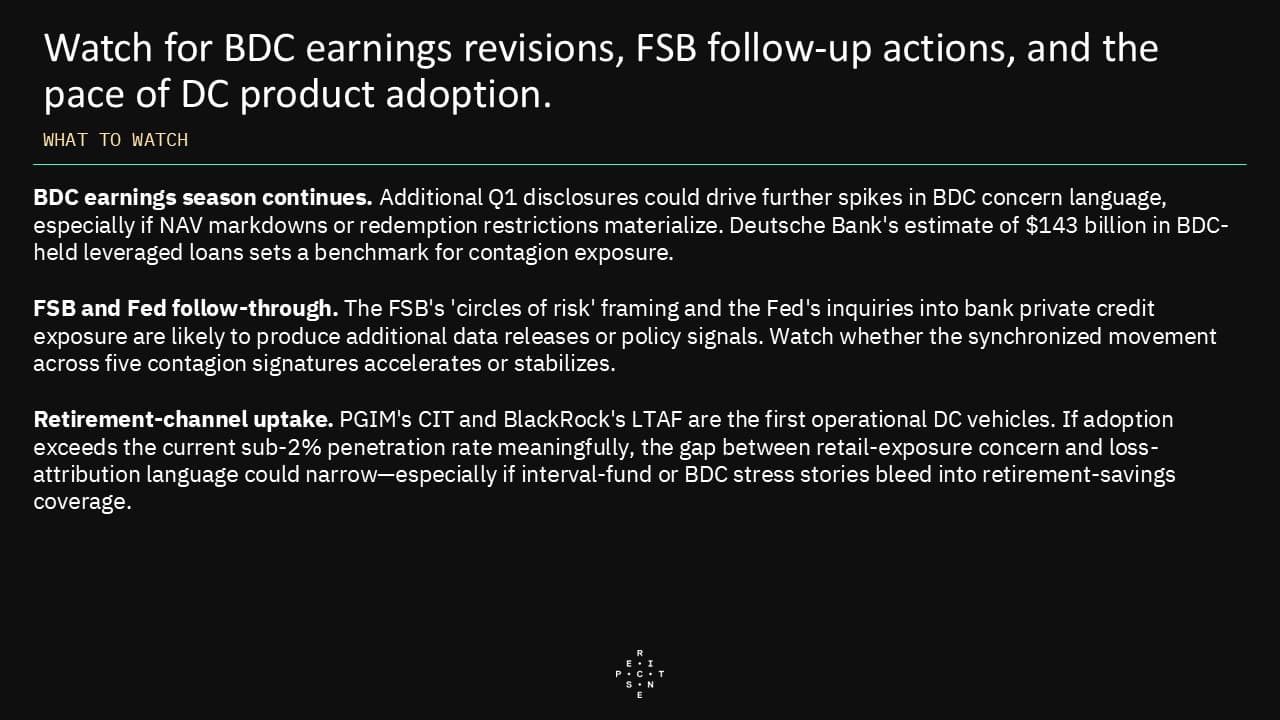
  • Interval fund and BDC scrutiny remains the most voluminous private credit media narrative, but its character is shifting from generalized alarm toward pointed structural critique. Redemption queues at major vehicles—where investors received roughly 30 cents on the dollar of requested withdrawals—and candid industry concessions that "semi-liquid" may have been marketed more generously than the structures support are driving coverage away from whether these vehicles are under stress and toward whether the entire product category was fundamentally mis-framed.
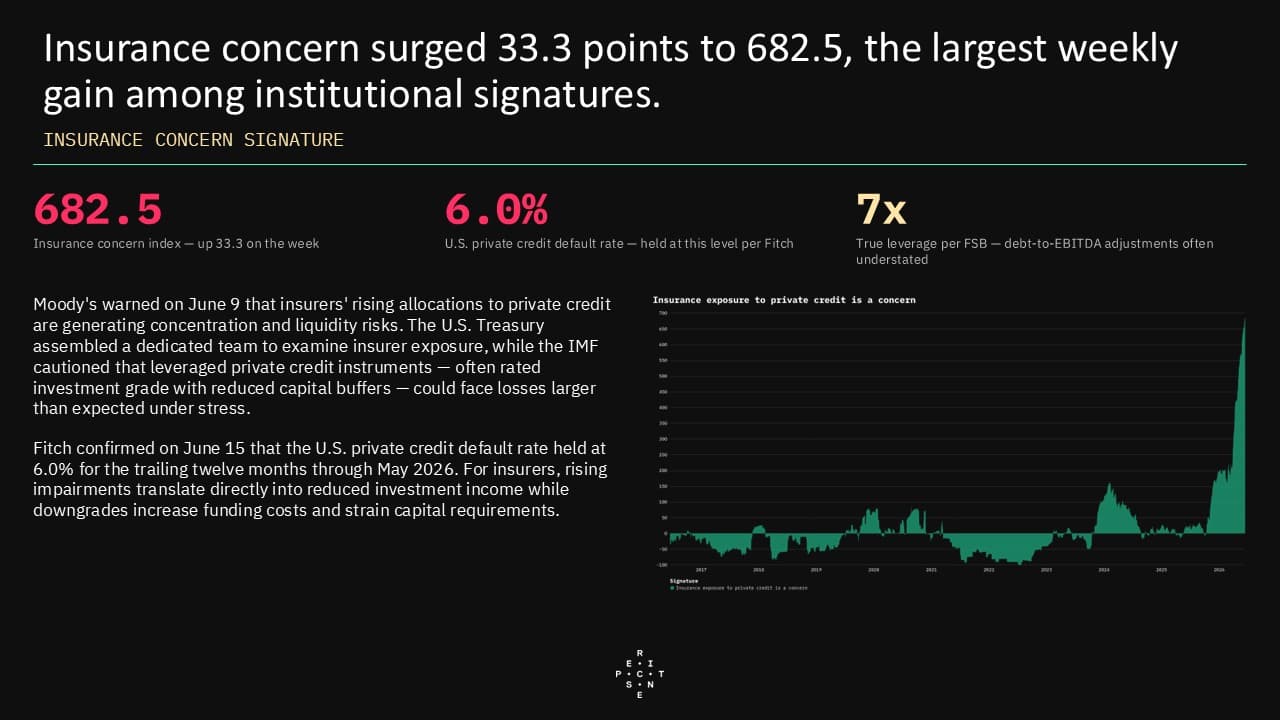
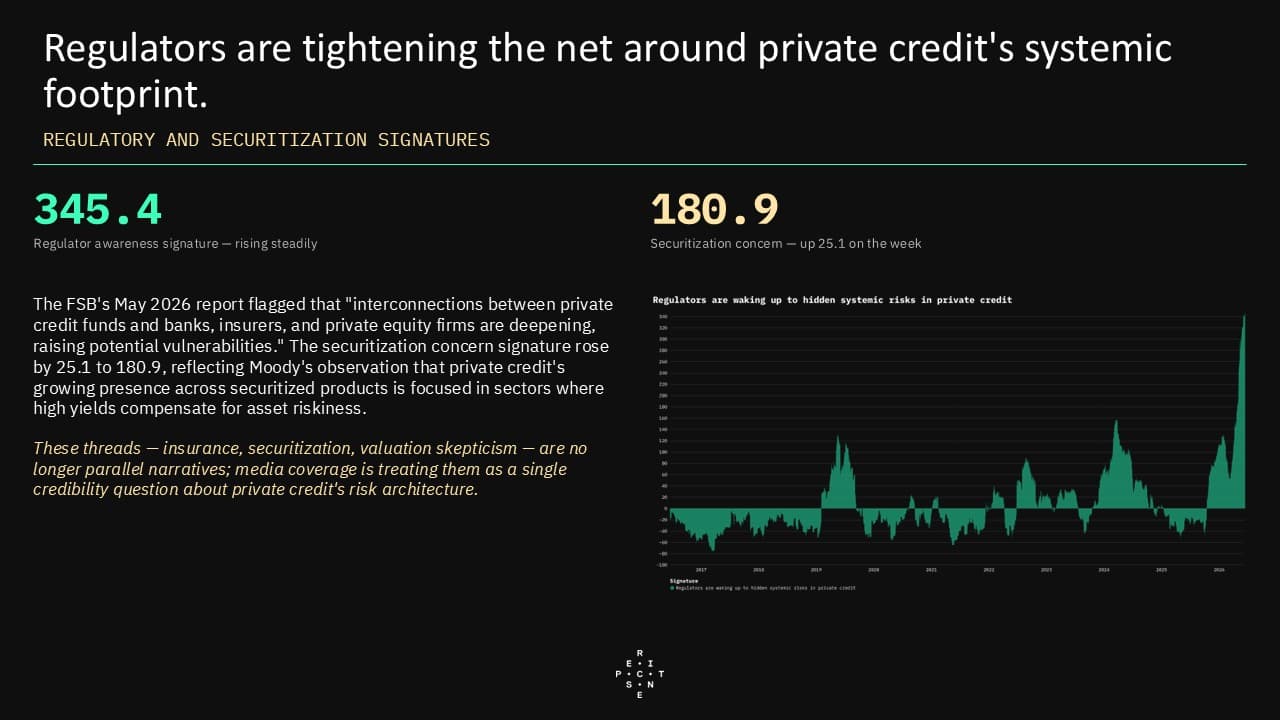
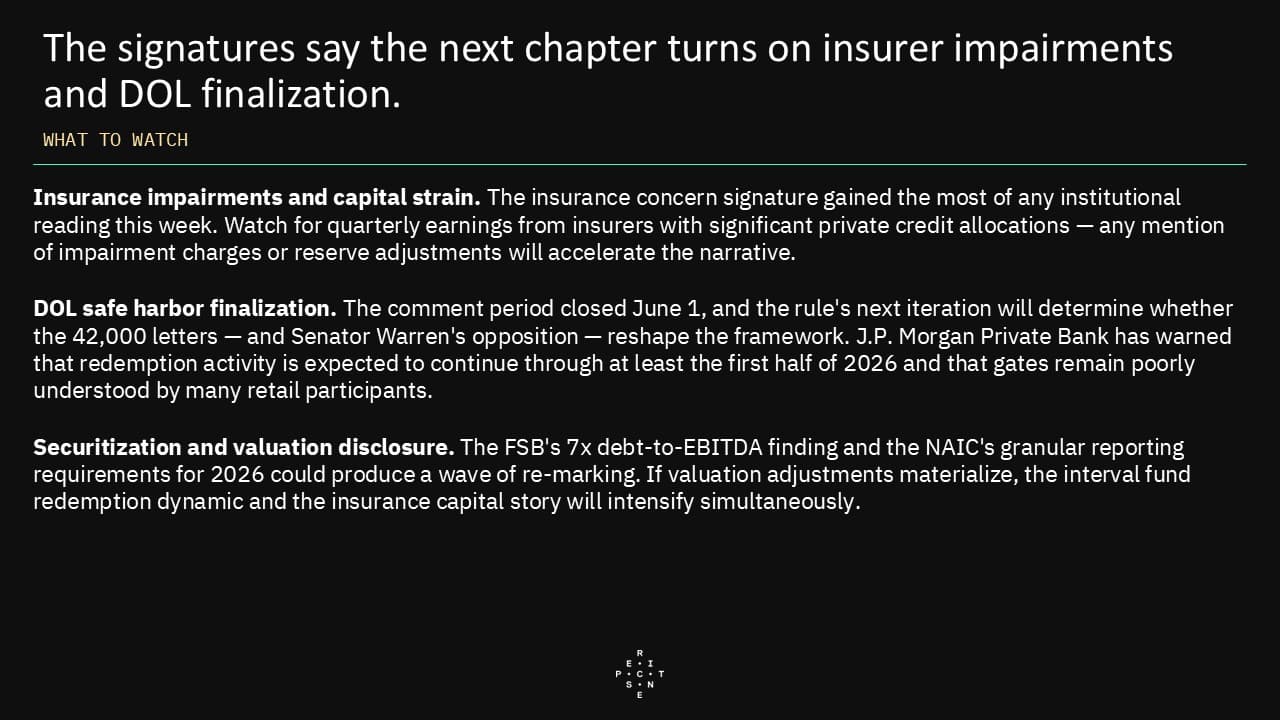
  • Insurance company exposure to private credit has become the fastest-intensifying strand of systemic concern in financial media, fed by the same record default rates weighing on interval fund and BDC sentiment. Moody's warnings about concentration and liquidity risk, a dedicated U.S. Treasury review team, and the FSB's observation that true leverage may approach 7x debt-to-EBITDA have converged with Fitch's report that the U.S. private credit default rate held at a record 6.0% in May 2026—creating a media environment in which insurer impairments and capital strain are treated as the primary channel through which private credit stress could become systemic.
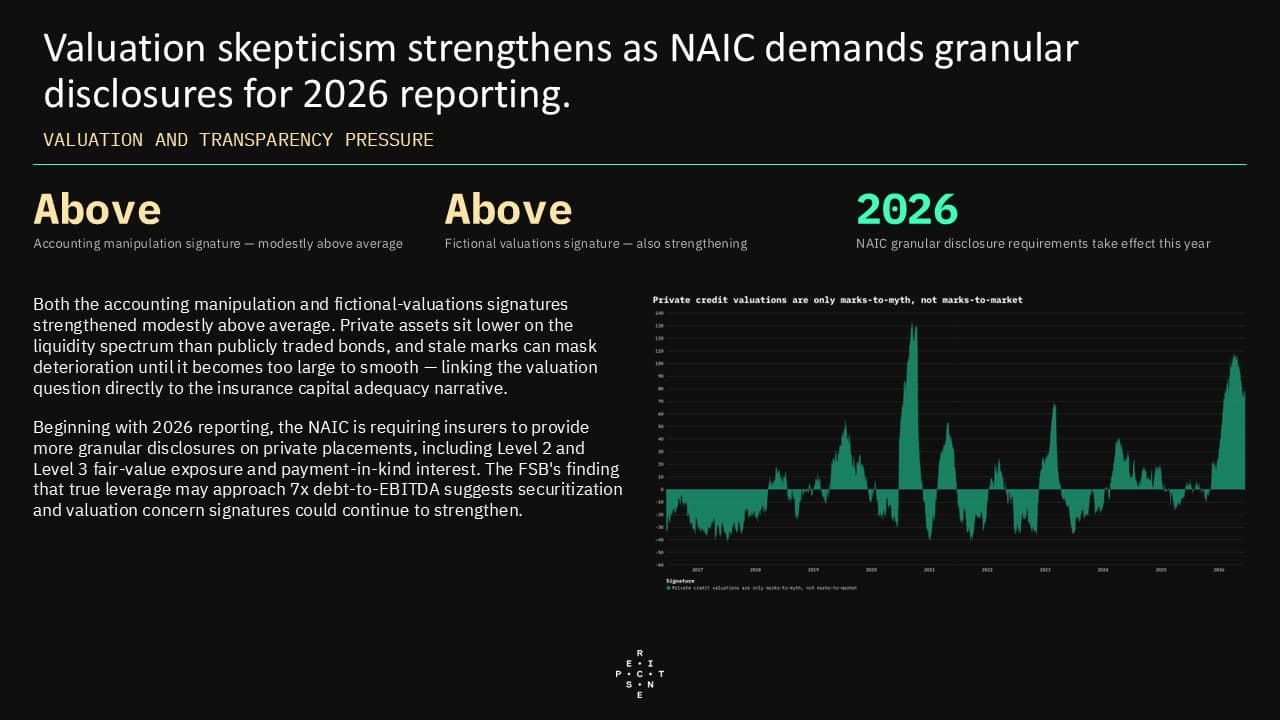
  • Valuation skepticism and securitization concern language is strengthening modestly but persistently, linking the insurance and interval fund narratives into a broader credibility question. Media coverage increasingly ties stale marks and opaque securitized structures to both the insurance capital adequacy question and the redemption pressure facing semi-liquid vehicles, while the NAIC's new granular disclosure requirements for 2026 reporting may themselves be generating additional scrutiny.
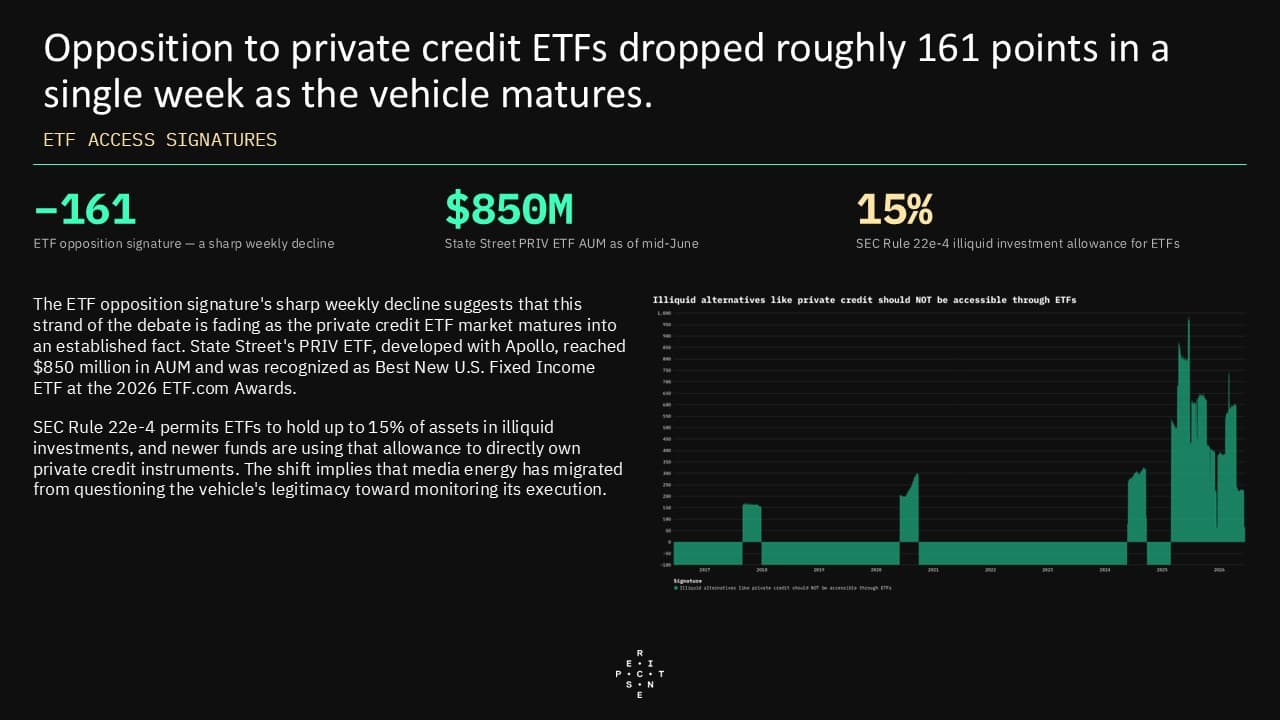
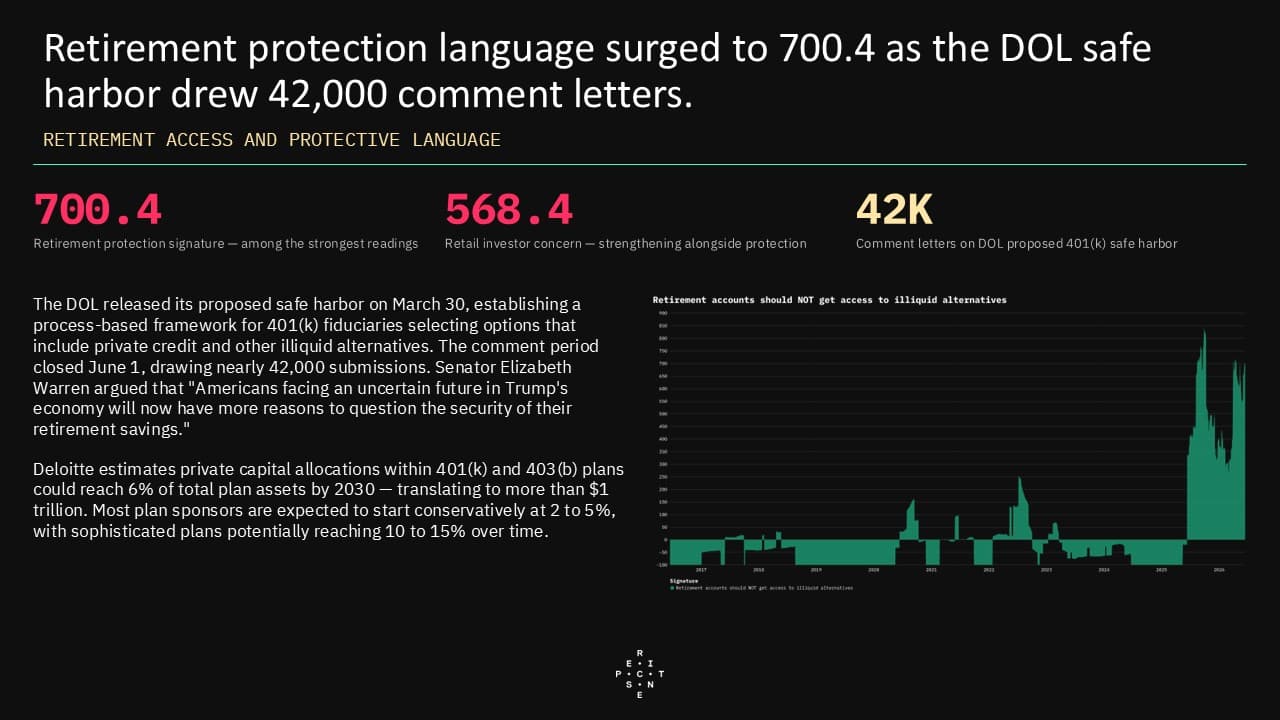
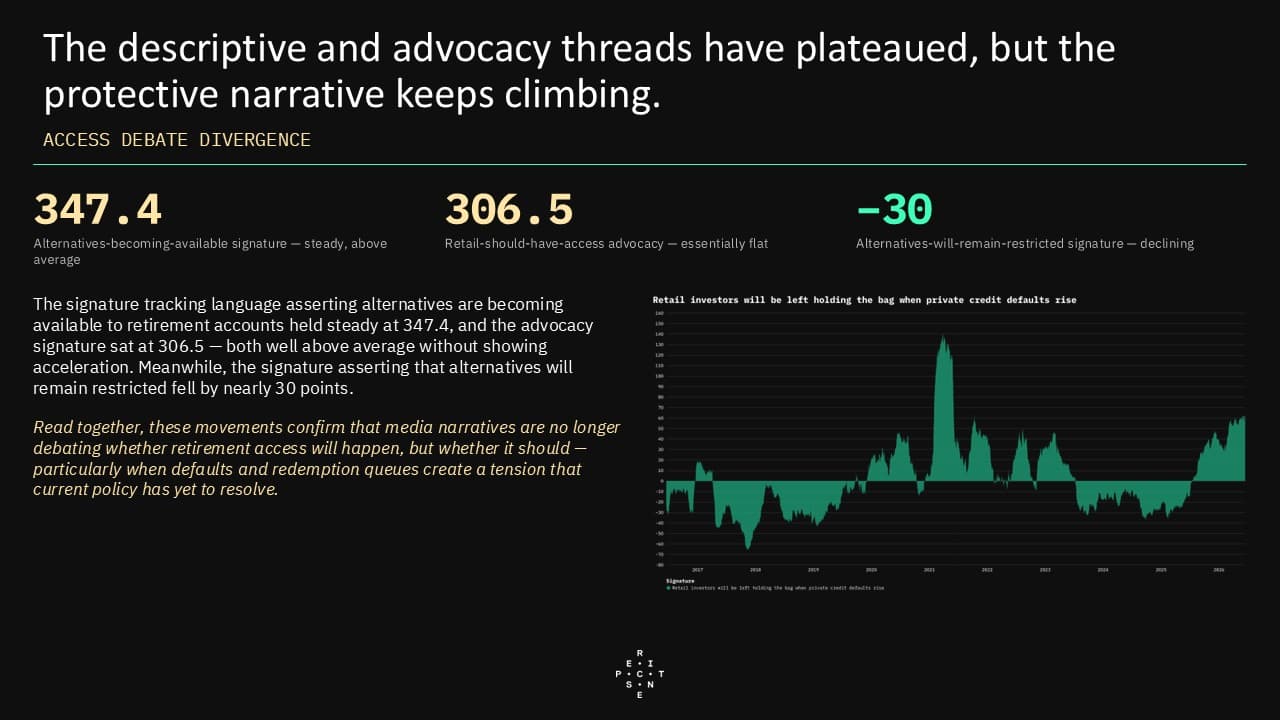
  • The retail and retirement access debate has fractured into distinct and diverging threads: opposition to private credit ETFs is collapsing, while protective language about retirement account access is among the strongest in the dataset. The DOL's proposed safe harbor for 401(k) plans drew nearly 42,000 comment letters and sharp political opposition, and media coverage has largely moved past whether retirement access will happen to focus on whether it should—particularly given that record defaults and ongoing redemption queues create a tension that the current policy trajectory has yet to resolve.

Recent Pulses

Markets PulseWeeklySep 22, 2026

Markets Pulse September 15, 2026

The regime-change story arrives without any accompanying fear language. Every flight-to-safety signature — Treasurys, Swiss franc, yen, gold, money market funds — sits deep in negative territory, geopolitical and monetary policy uncertainty signatures were flat, and risk-on and risk-off readings have converged to nearly the same level just below zero. Media are narrating a supply shock, a five-percent ten-year, and a first hike since 2023 while conspicuously declining to counsel defensive positioning. Election-season transfer proposals collided with a hardening sovereign-risk story, and media asserted both outcomes at once. The helicopter-money signature registered the largest single move in the file, and stimulus-check predictions rose with it, yet signatures tracking debt paydown, deficit reduction, and austerity legislation also strengthened in the same week, while fiscal policy uncertainty remained flat. Commentators are expressing conviction about incompatible fiscal futures rather than doubt. Simultaneously, signatures tying runaway spending to higher Treasury yields, and those linking bond weakness to deficits and unfunded tax cuts, all gained, and claims that Treasurys are pricing genuine default risk moved into positive territory. Taken together, Sections 1 and 2 describe a media framework in which monetary and fiscal policy are pulling in opposite directions. Coverage pairs a hawkish Fed responding to oil-driven inflation with a proposed trillion-dollar household giveaway, and the reserve-currency channel sharpened alongside it: the signature tying dollar-status threats specifically to debt sustainability rose while the generic version held flat. Claims that White House pressure on foreign Treasury holders is deterring buyers remain the densest reading in the entire file, even as it eased slightly, and official-sector gold substitution language stayed elevated without accelerating further. Tariff politics are running in reverse, and the war has been absorbed into the same affordability argument. The signature tracking broad public opposition to tariffs climbed to one of the highest standings in the file while claims of public support weakened further, and the stated rationale rotated decisively: reshoring-manufacturing arguments dropped hard while "make other countries pay their fair share" and negotiating-leverage framings gained. Directional language turned two-sided for the first time in months. Bridging Sections 1 and 3, voter coverage now treats tariffs and the conflict as a single price story, which the K-shaped-economy framing organizes into a midterm affordability fight — notably, the market version of that bifurcation narrative eased even as chip stocks sold off, and the argument that investors have no alternative to US large-cap growth has effectively vanished from coverage.

Markets PulseWeeklySep 22, 2026

Markets Pulse

Next release: September 29, 2026

Private Credit PulseBiweeklySep 22, 2026

Private Credit Pulse

Next release: October 06, 2026