Private Credit Pulse
BiweeklyAugust 11, 2026

Private Credit Pulse July 28, 2026

7.28PrivateCreditPulse1.jpg1
7.28PrivateCreditPulse2.jpg1
7.28PrivateCreditPulse3.jpg
7.28PrivateCreditPulse4.jpg
7.28PrivateCreditPulse5.jpg
7.28PrivateCreditPulse6.jpg
7.28PrivateCreditPulse7.jpg
7.28PrivateCreditPulse8.jpg
7.28PrivateCreditPulse9.jpg
7.28PrivateCreditPulse10.jpg
7.28PrivateCreditPulse11.jpg
7.28PrivateCreditPulse12.jpg
7.28PrivateCreditPulse13.jpg
7.28PrivateCreditPulse14.jpg
7.28PrivateCreditPulse15.jpg
7.28PrivateCreditPulse16.jpg
7.14PrivateCredit17.jpg
7.14PrivateCredit18.jpg

Executive Summary

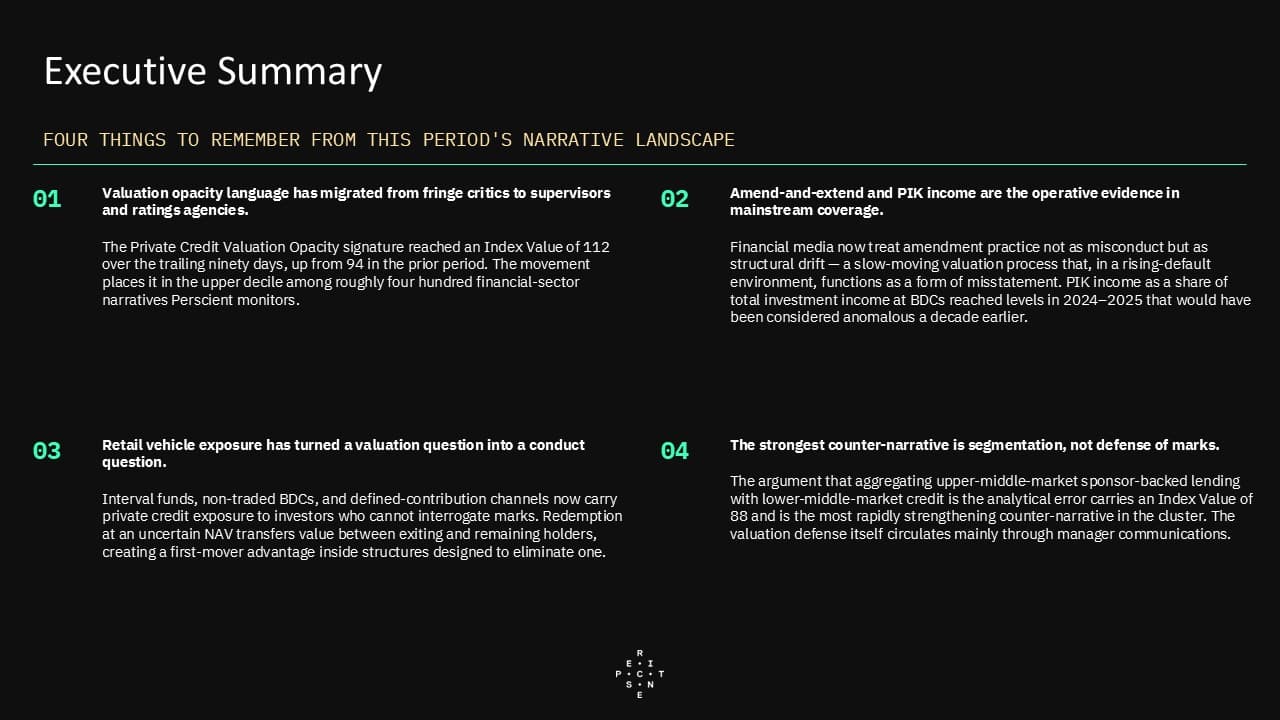
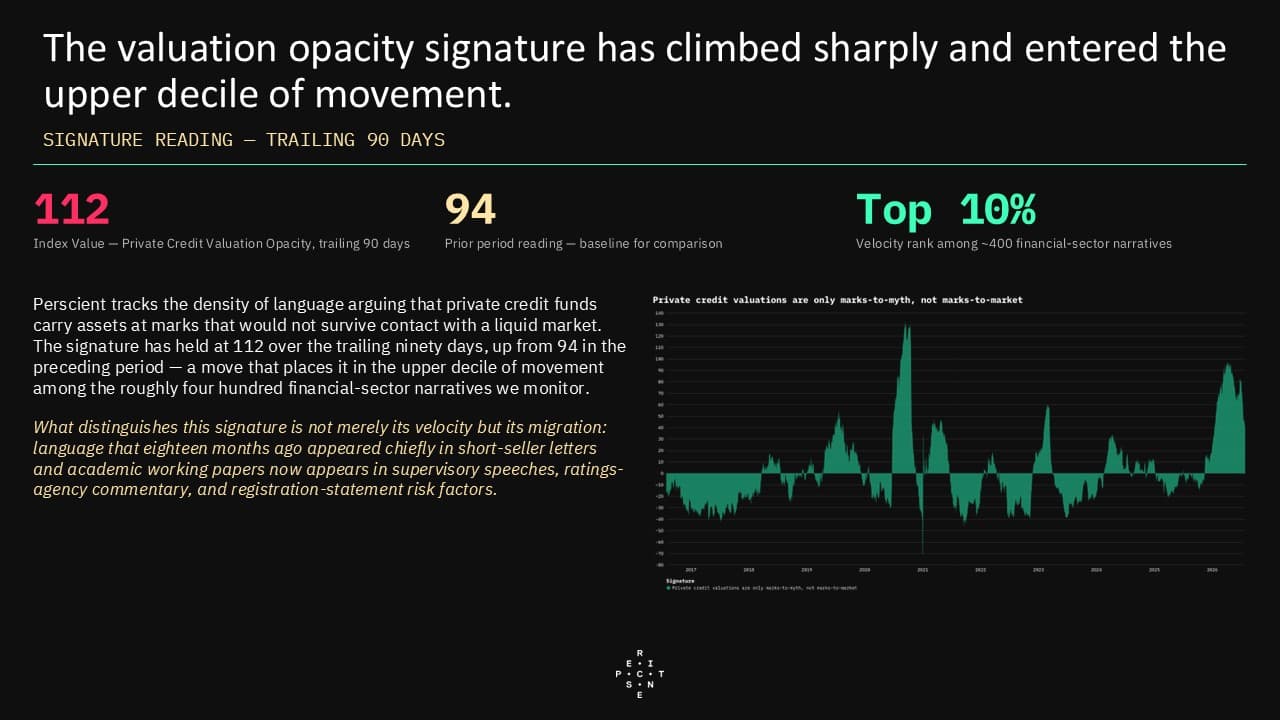
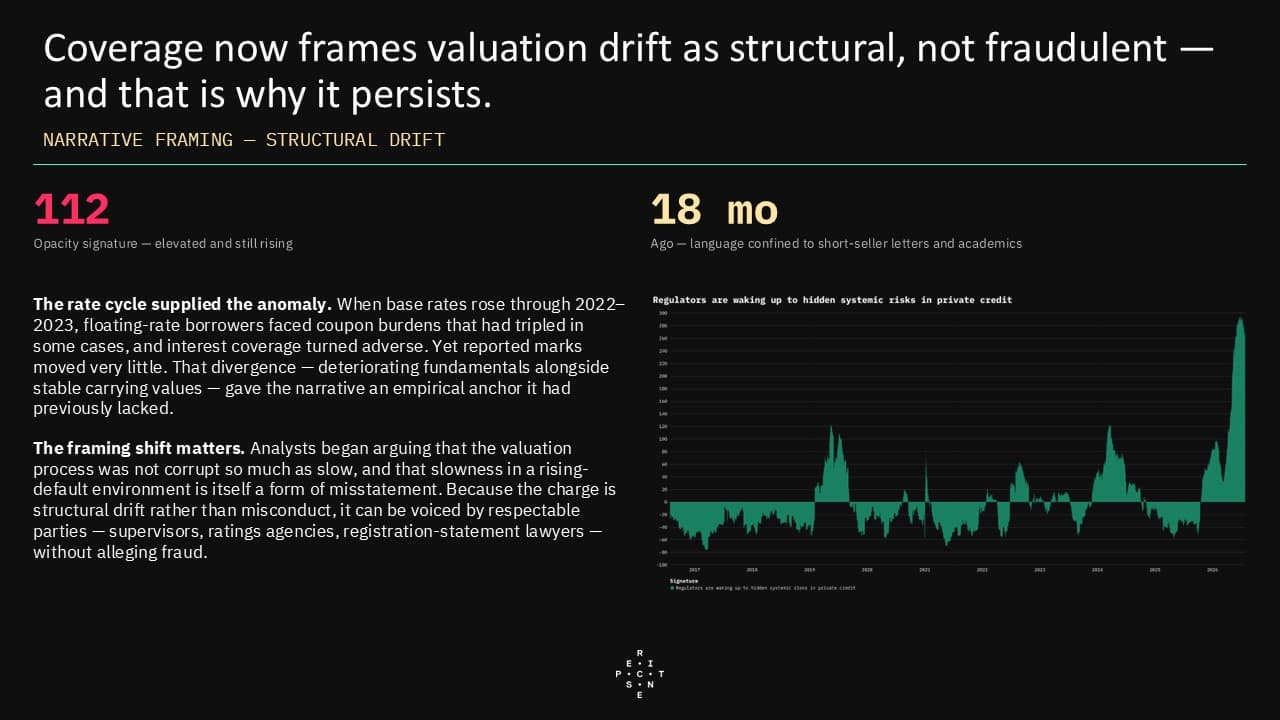
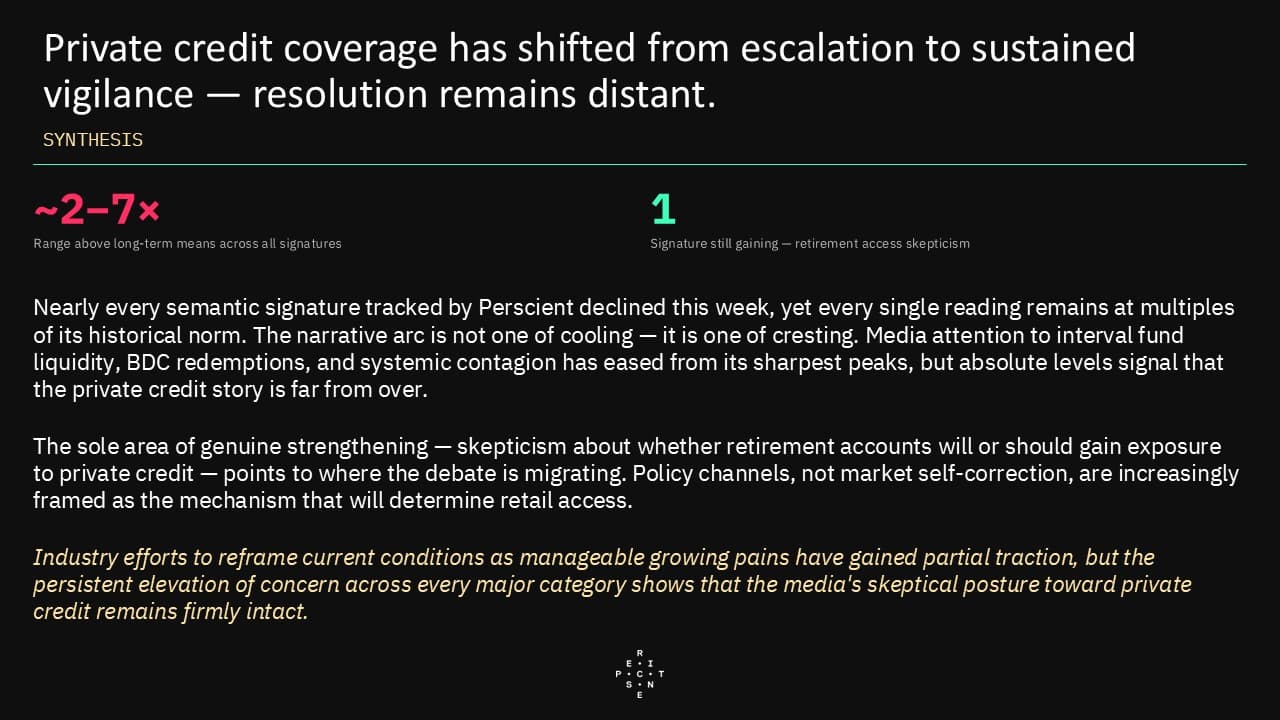
  • The defining media development of the past two weeks is not louder criticism but more respectable criticism: our semantic signature tracking the density of language arguing that private credit marks would not survive contact with a liquid market has migrated out of short-seller letters and academic working papers and into supervisory speeches, ratings-agency commentary, and registration-statement risk factors. Coverage now treats valuation reliability as a standing supervisory question rather than an adversarial claim.
  • Financial media have converged on a framing of structural drift rather than misconduct, which explains the narrative's staying power. The rate cycle supplied the anomaly that commentary needed — deteriorating borrower coverage alongside barely moving carrying values — and the resulting story permits mainstream analysts to voice the criticism without alleging fraud.
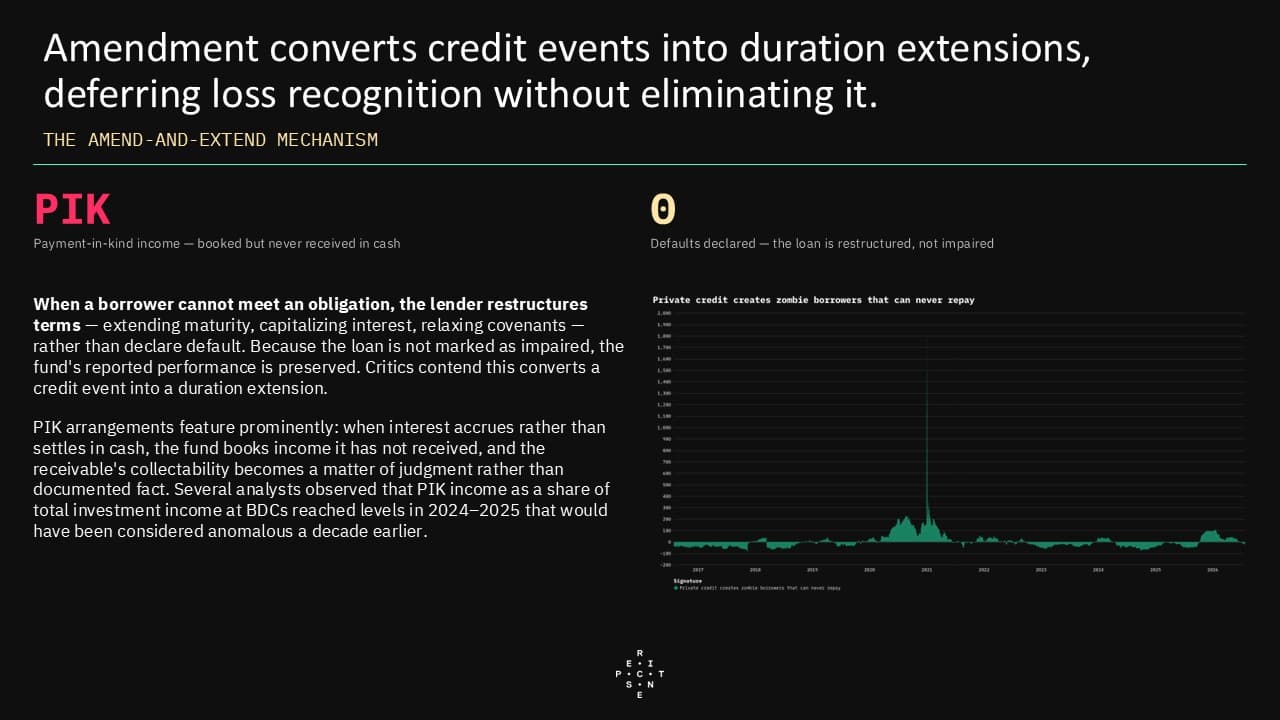
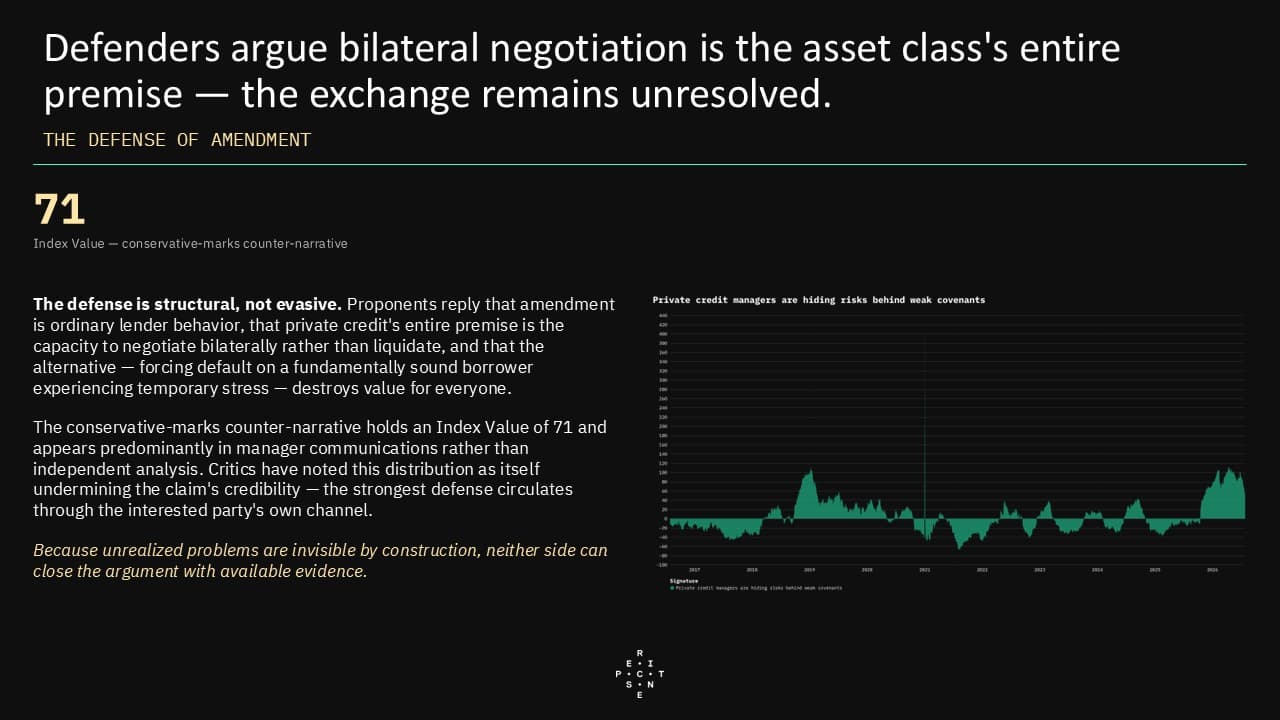
  • Amend-and-extend practice and payment-in-kind income have become the operative evidence in this coverage, cited as mechanisms that convert credit events into duration extensions and book income never received. Defenders are given space in the same articles, arguing that bilateral negotiation is the asset class's entire premise, so the exchange remains unresolved rather than settled.
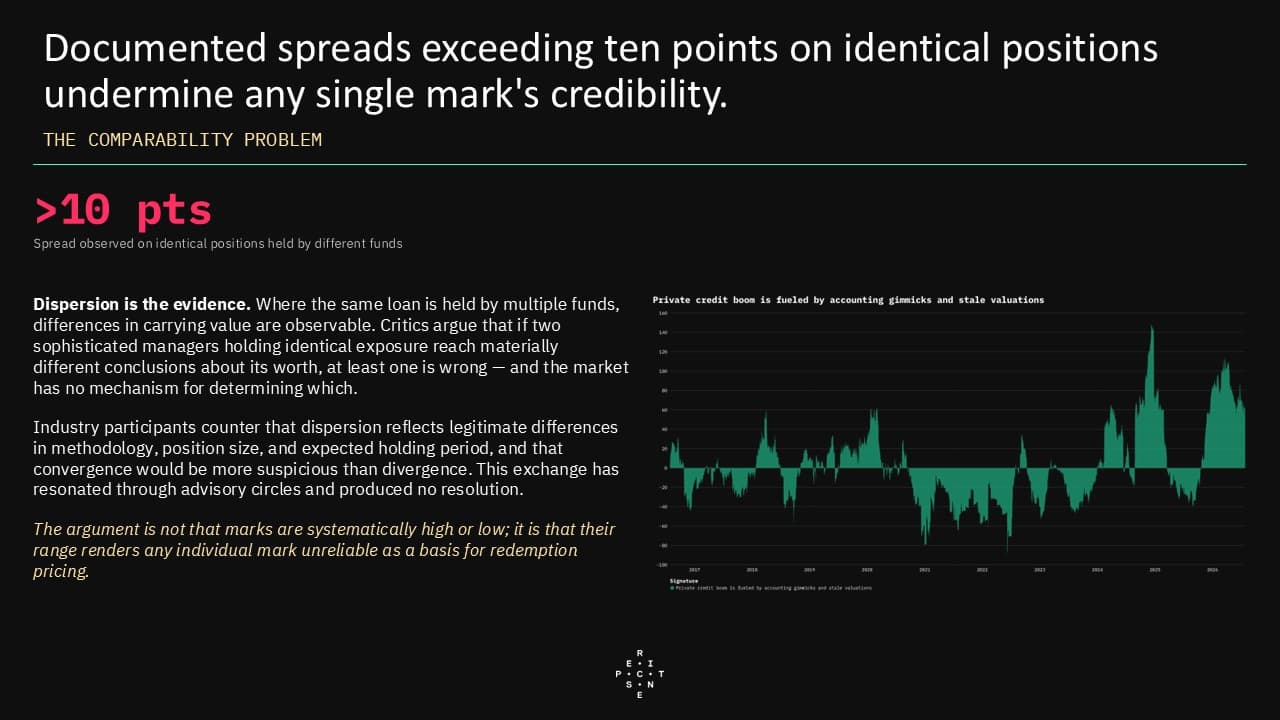
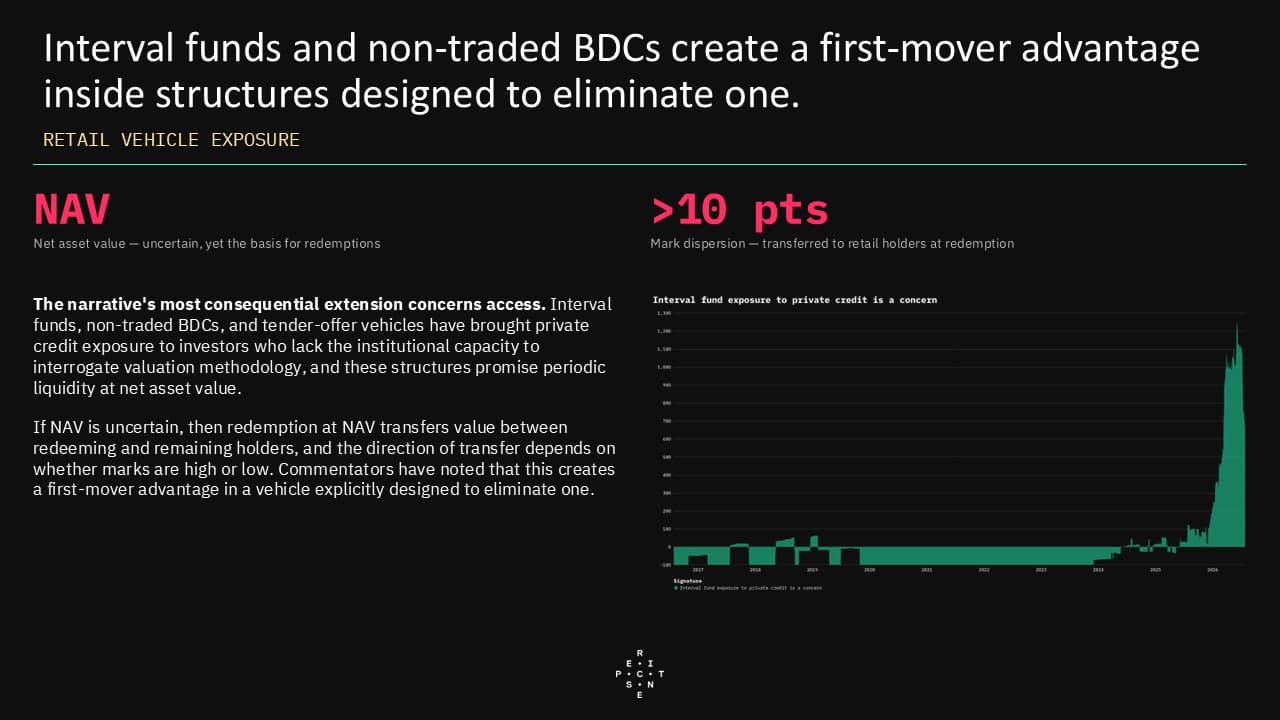
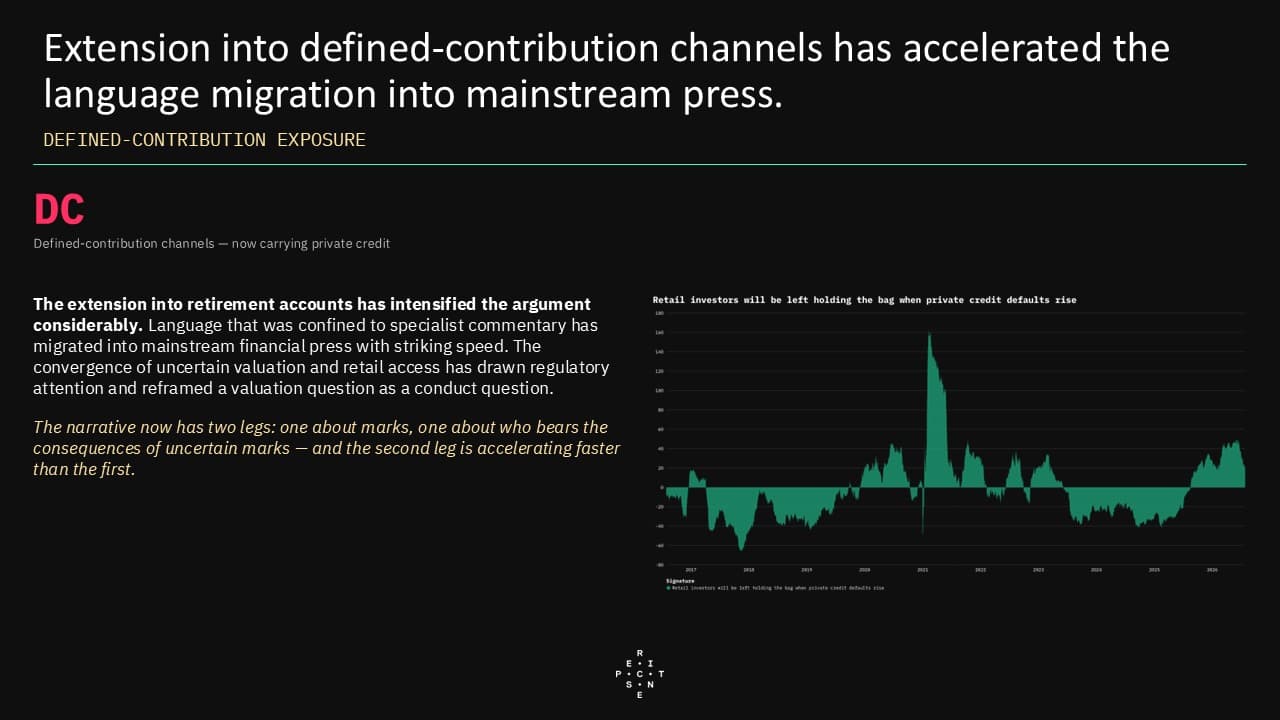
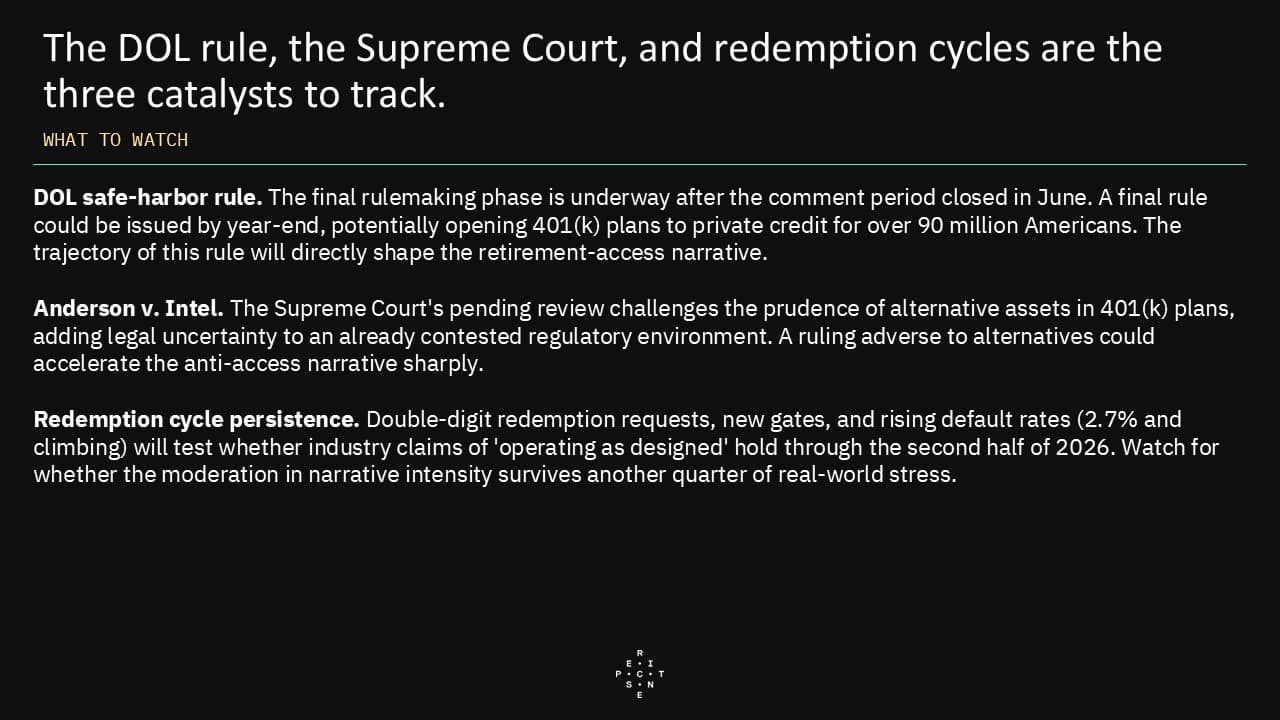
  • Two threads reinforce each other in the press: documented spreads on identical positions held by different funds, and the extension of exposure to interval funds, non-traded BDCs, and defined-contribution channels. Together they produce the argument that redemption at an uncertain net asset value transfers value between exiting and remaining holders, creating a first-mover advantage inside structures designed to remove one.
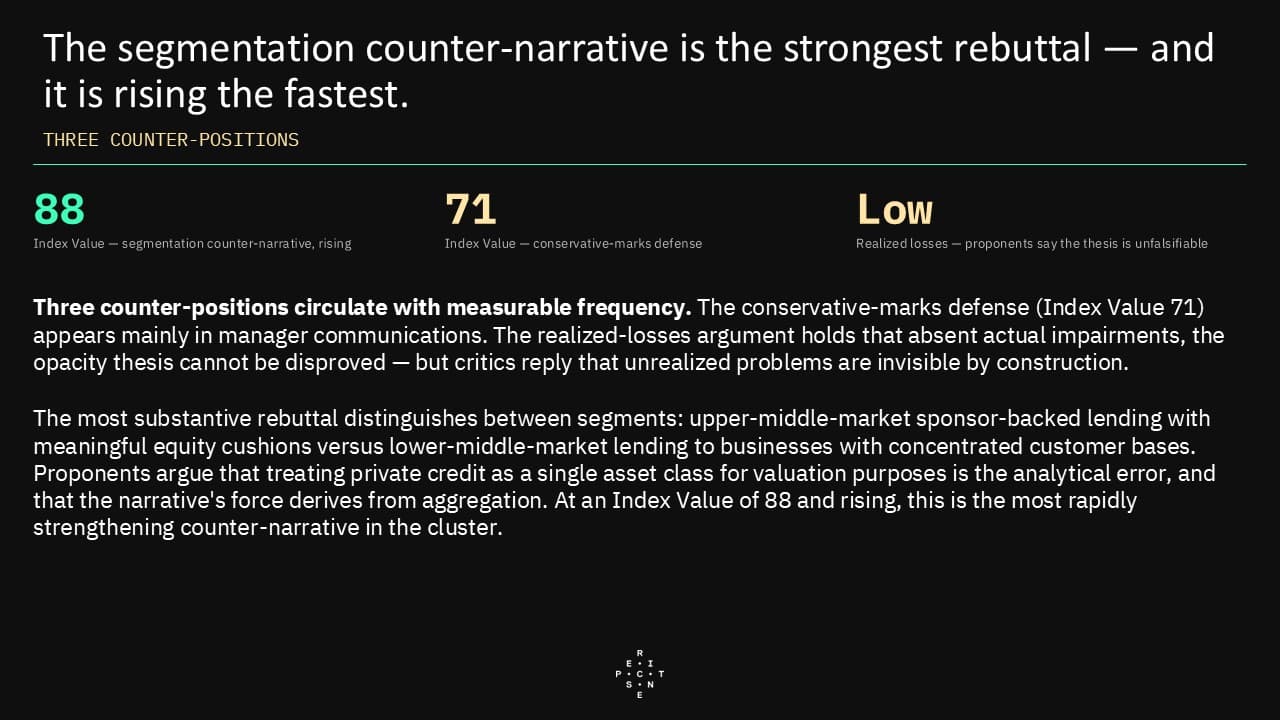
  • Counter-narratives are not absent but are unevenly credible in the coverage. The claim that managers mark conservatively circulates mainly through manager communications, a distribution critics themselves point out; the strongest and fastest-strengthening rebuttal instead argues that aggregating upper-middle-market sponsor-backed lending with lower-middle-market credit is the analytical error. Because unrealized problems are invisible in principle, neither side can close the argument, and institutional carriers of the critique — supervisors, ratings agencies, and the plaintiffs' bar — ensure that it persists in some form regardless of whether losses arrive.

Recent Pulses

Markets PulseWeeklySep 22, 2026

Markets Pulse September 15, 2026

The regime-change story arrives without any accompanying fear language. Every flight-to-safety signature — Treasurys, Swiss franc, yen, gold, money market funds — sits deep in negative territory, geopolitical and monetary policy uncertainty signatures were flat, and risk-on and risk-off readings have converged to nearly the same level just below zero. Media are narrating a supply shock, a five-percent ten-year, and a first hike since 2023 while conspicuously declining to counsel defensive positioning. Election-season transfer proposals collided with a hardening sovereign-risk story, and media asserted both outcomes at once. The helicopter-money signature registered the largest single move in the file, and stimulus-check predictions rose with it, yet signatures tracking debt paydown, deficit reduction, and austerity legislation also strengthened in the same week, while fiscal policy uncertainty remained flat. Commentators are expressing conviction about incompatible fiscal futures rather than doubt. Simultaneously, signatures tying runaway spending to higher Treasury yields, and those linking bond weakness to deficits and unfunded tax cuts, all gained, and claims that Treasurys are pricing genuine default risk moved into positive territory. Taken together, Sections 1 and 2 describe a media framework in which monetary and fiscal policy are pulling in opposite directions. Coverage pairs a hawkish Fed responding to oil-driven inflation with a proposed trillion-dollar household giveaway, and the reserve-currency channel sharpened alongside it: the signature tying dollar-status threats specifically to debt sustainability rose while the generic version held flat. Claims that White House pressure on foreign Treasury holders is deterring buyers remain the densest reading in the entire file, even as it eased slightly, and official-sector gold substitution language stayed elevated without accelerating further. Tariff politics are running in reverse, and the war has been absorbed into the same affordability argument. The signature tracking broad public opposition to tariffs climbed to one of the highest standings in the file while claims of public support weakened further, and the stated rationale rotated decisively: reshoring-manufacturing arguments dropped hard while "make other countries pay their fair share" and negotiating-leverage framings gained. Directional language turned two-sided for the first time in months. Bridging Sections 1 and 3, voter coverage now treats tariffs and the conflict as a single price story, which the K-shaped-economy framing organizes into a midterm affordability fight — notably, the market version of that bifurcation narrative eased even as chip stocks sold off, and the argument that investors have no alternative to US large-cap growth has effectively vanished from coverage.

Markets PulseWeeklySep 22, 2026

Markets Pulse

Next release: September 29, 2026

Private Credit PulseBiweeklySep 22, 2026

Private Credit Pulse

Next release: October 06, 2026