Private Credit PulseBiweeklyNov 3, 2026
Private Credit Pulse
Next release: November 17, 2026

Next release: November 17, 2026
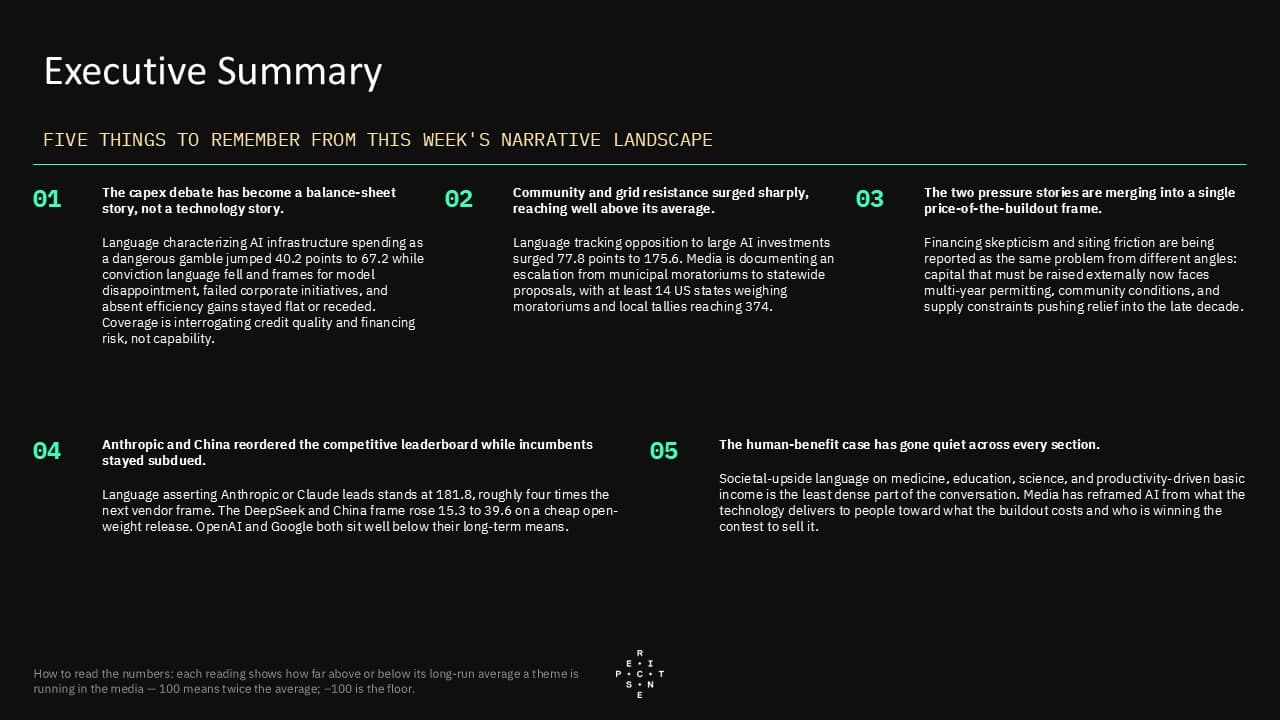
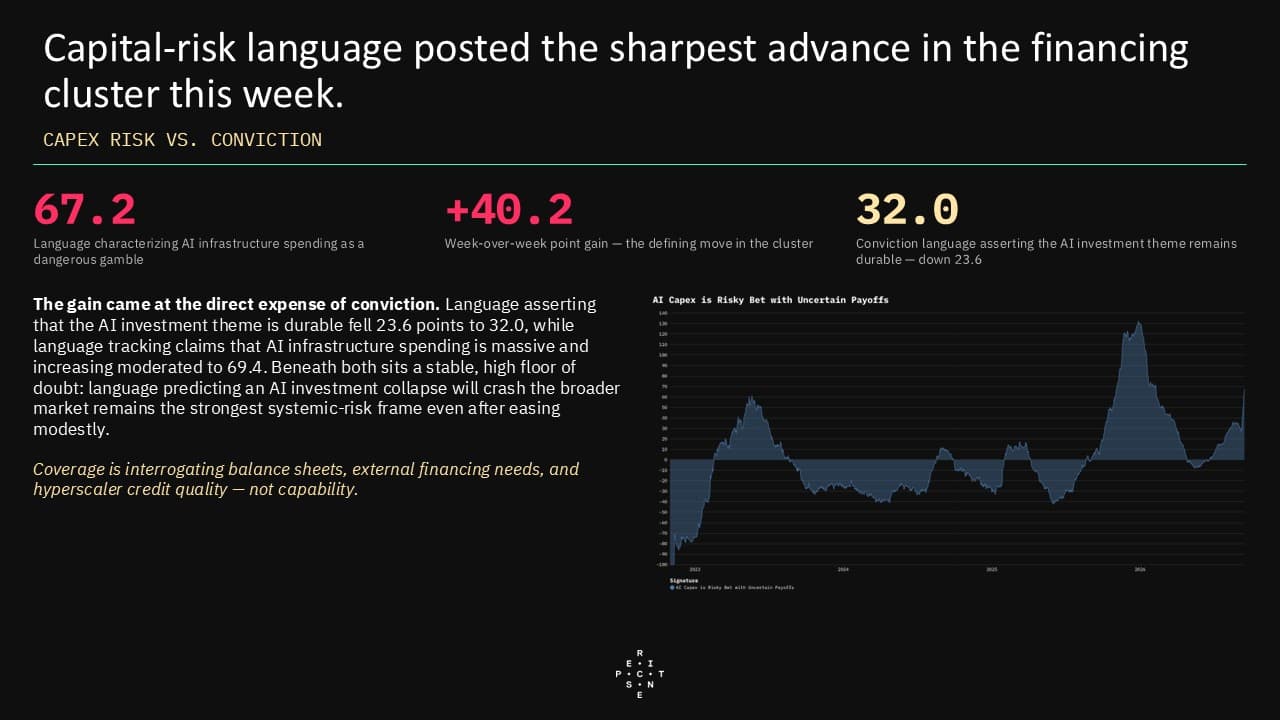
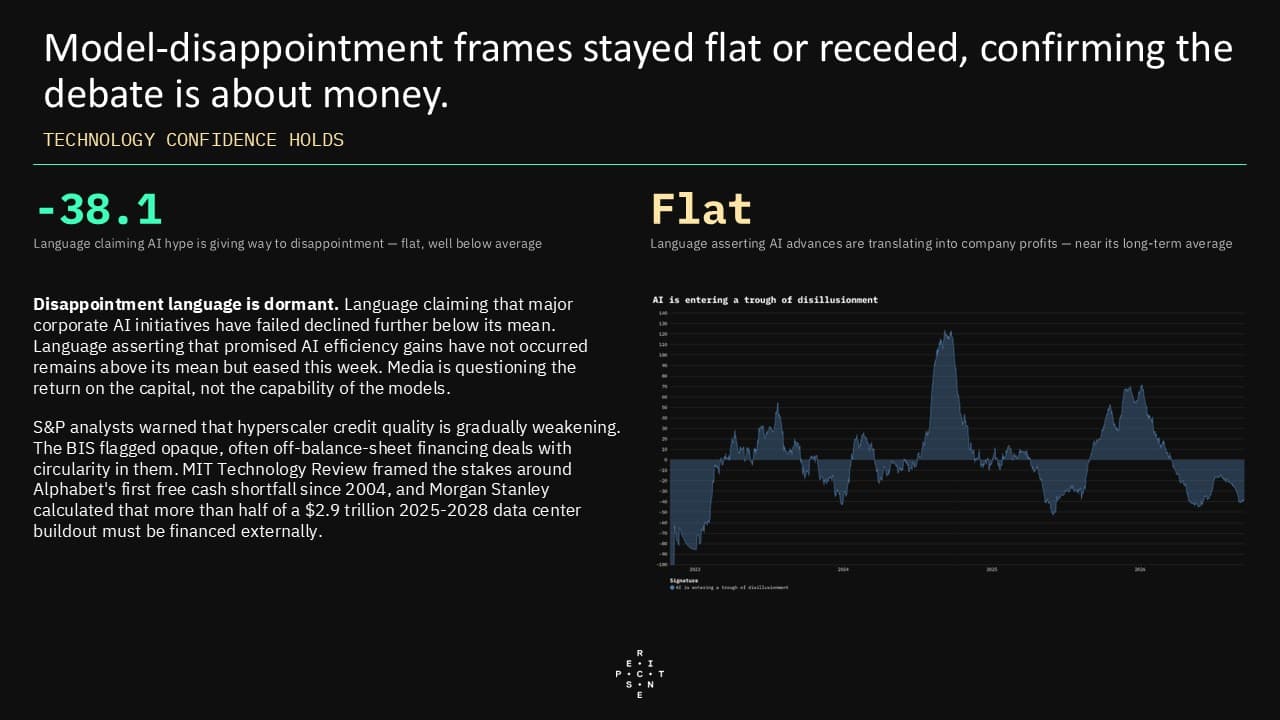
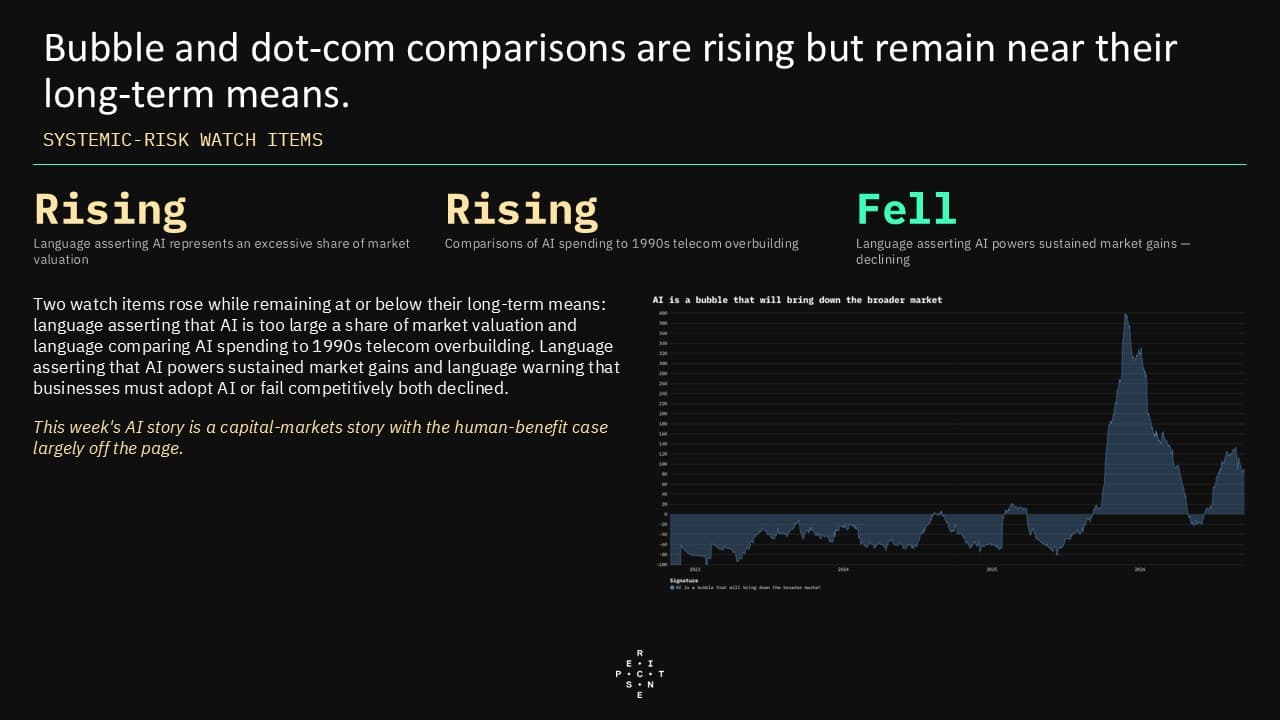
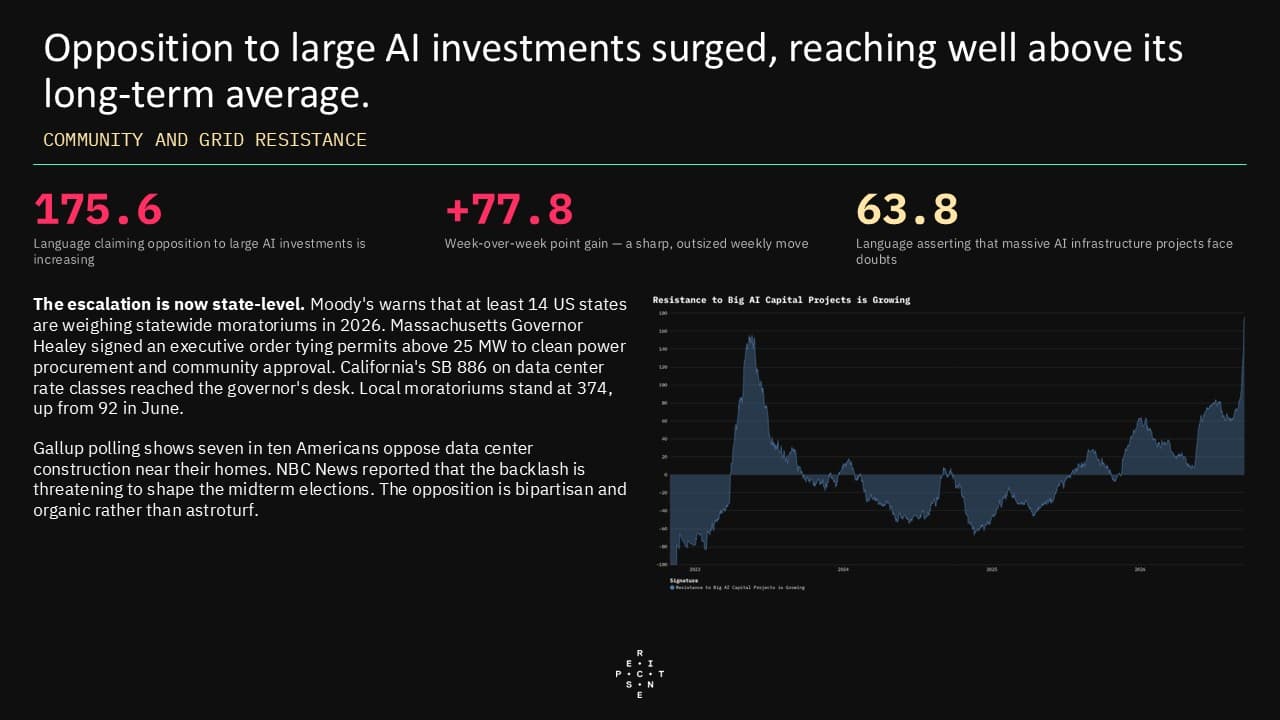
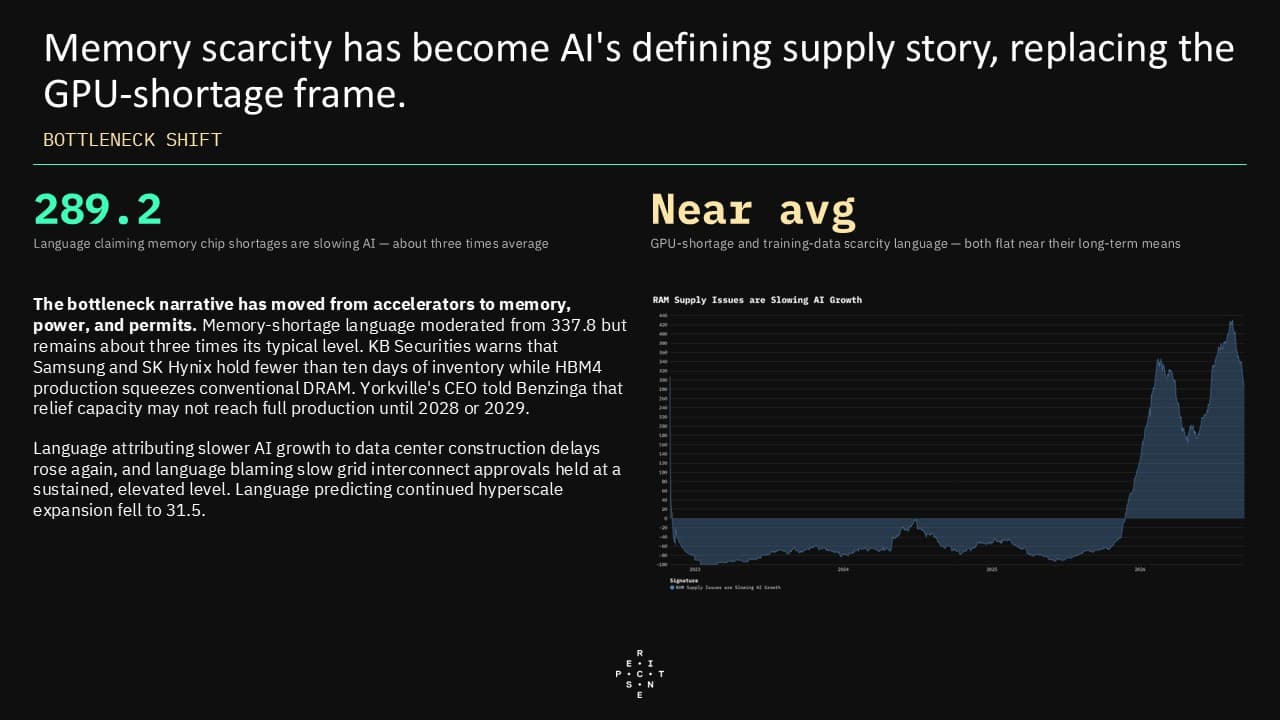
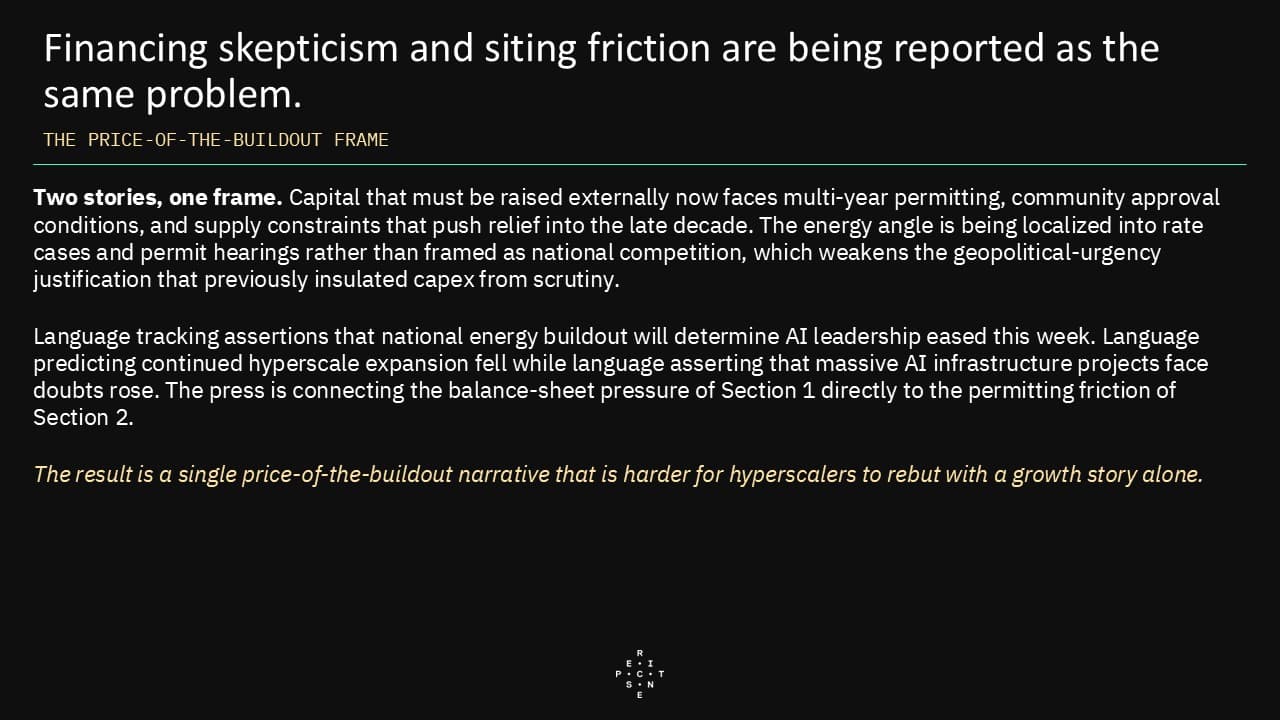
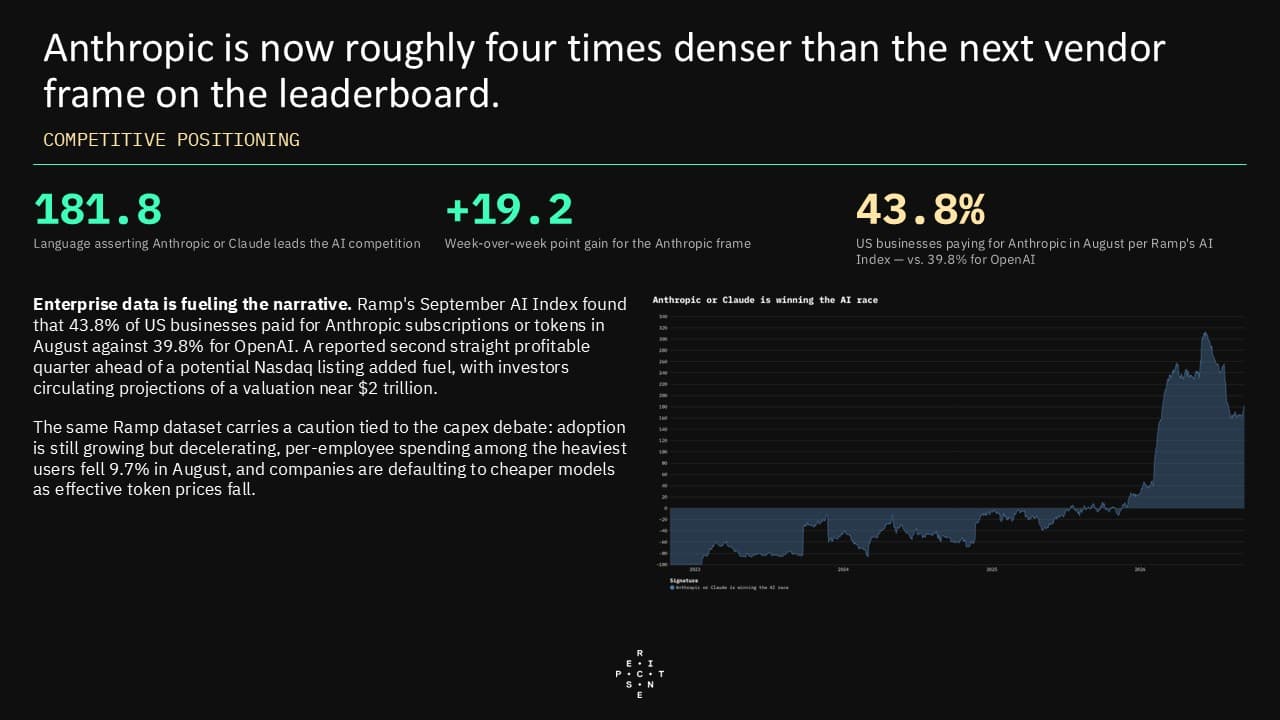
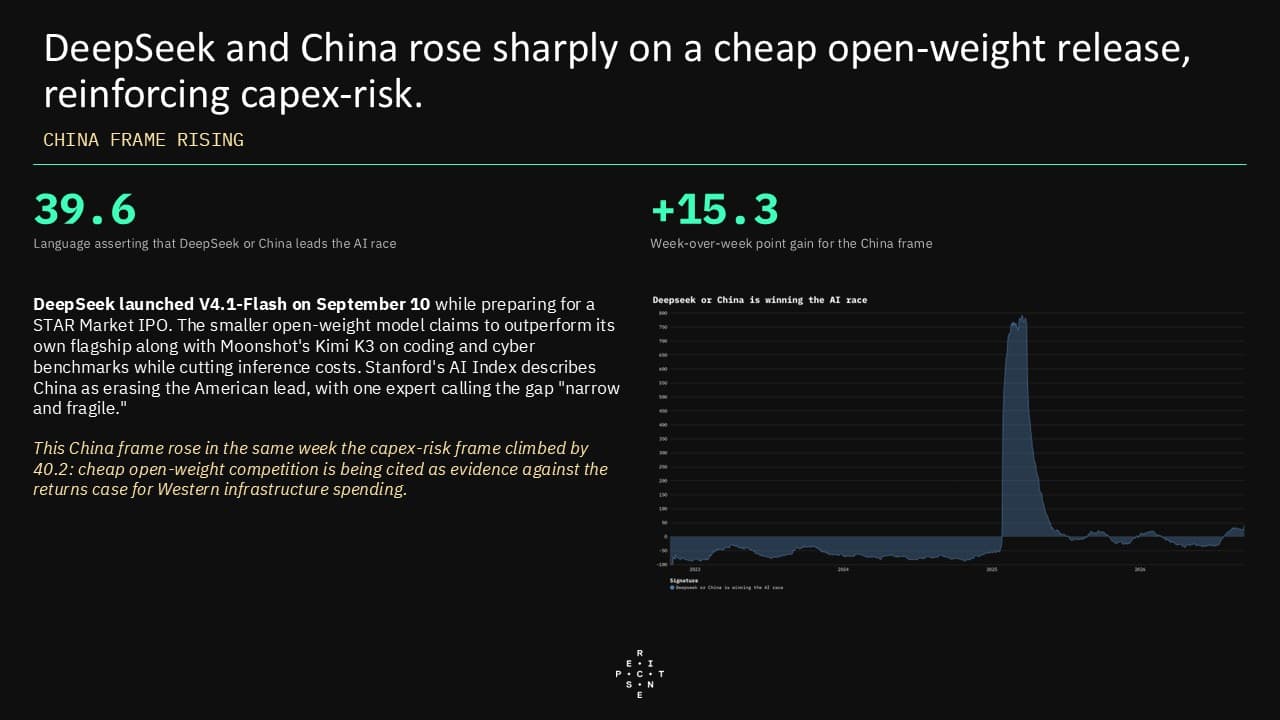
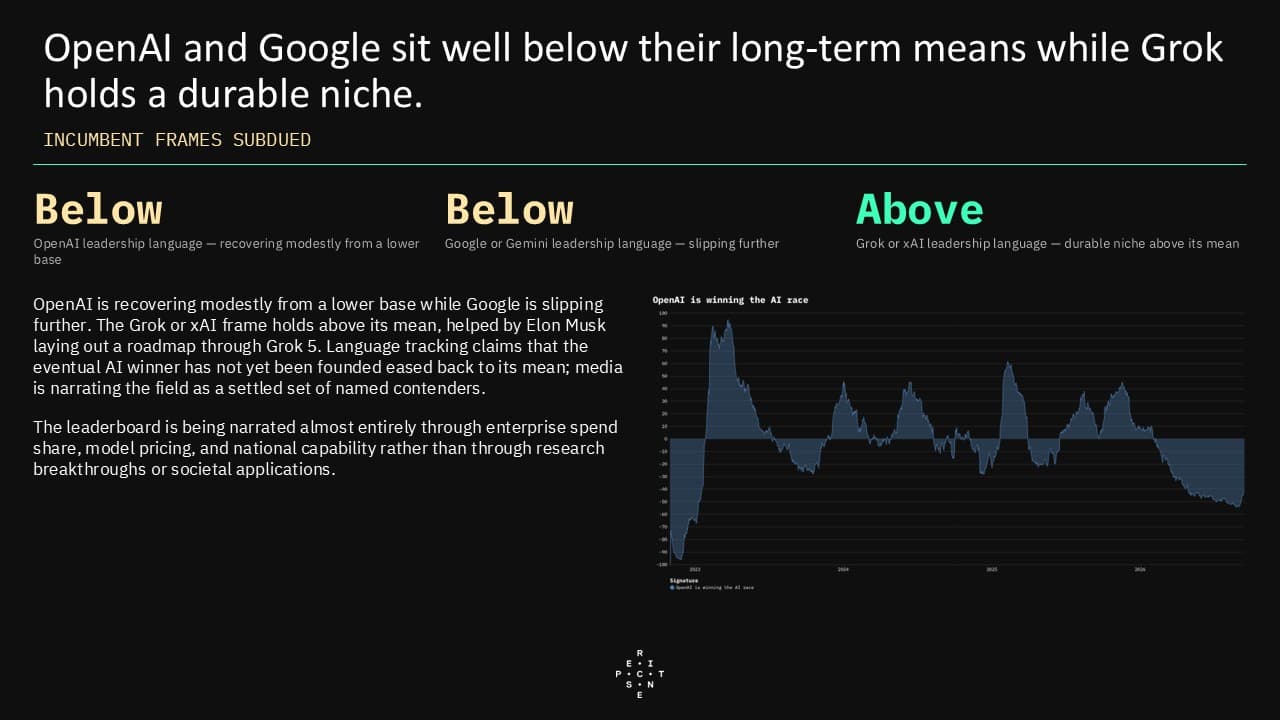
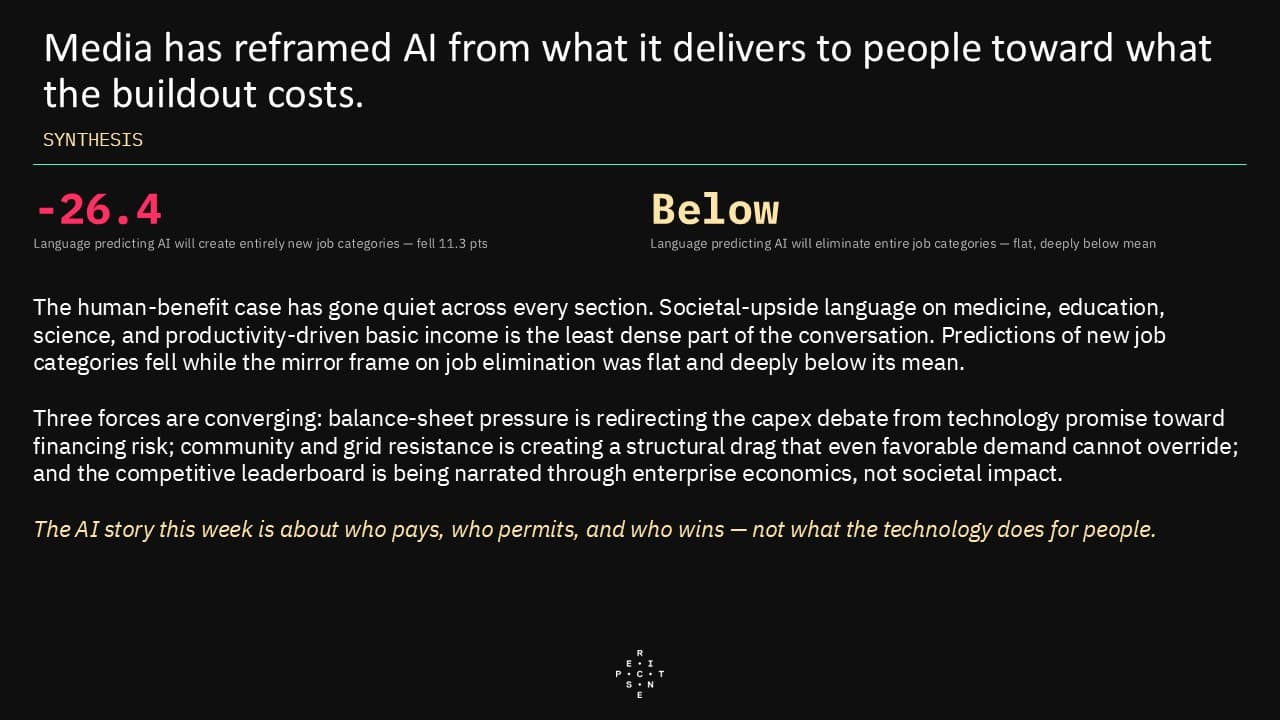
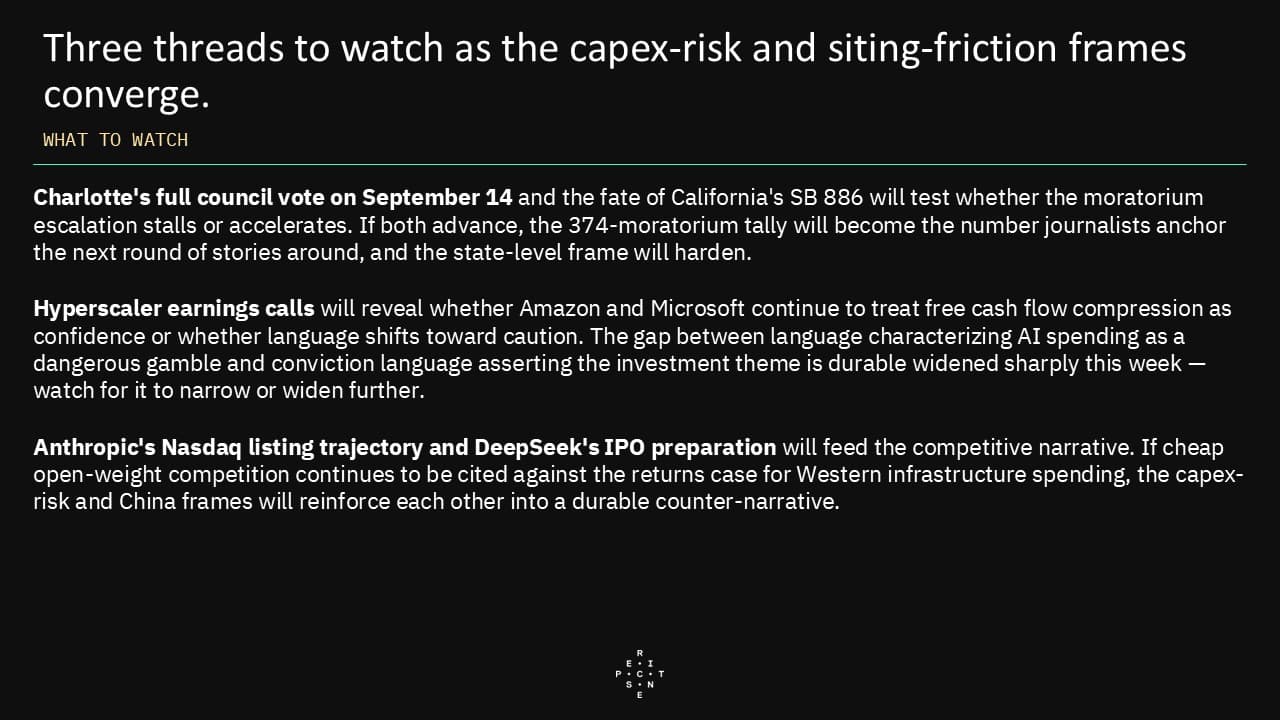
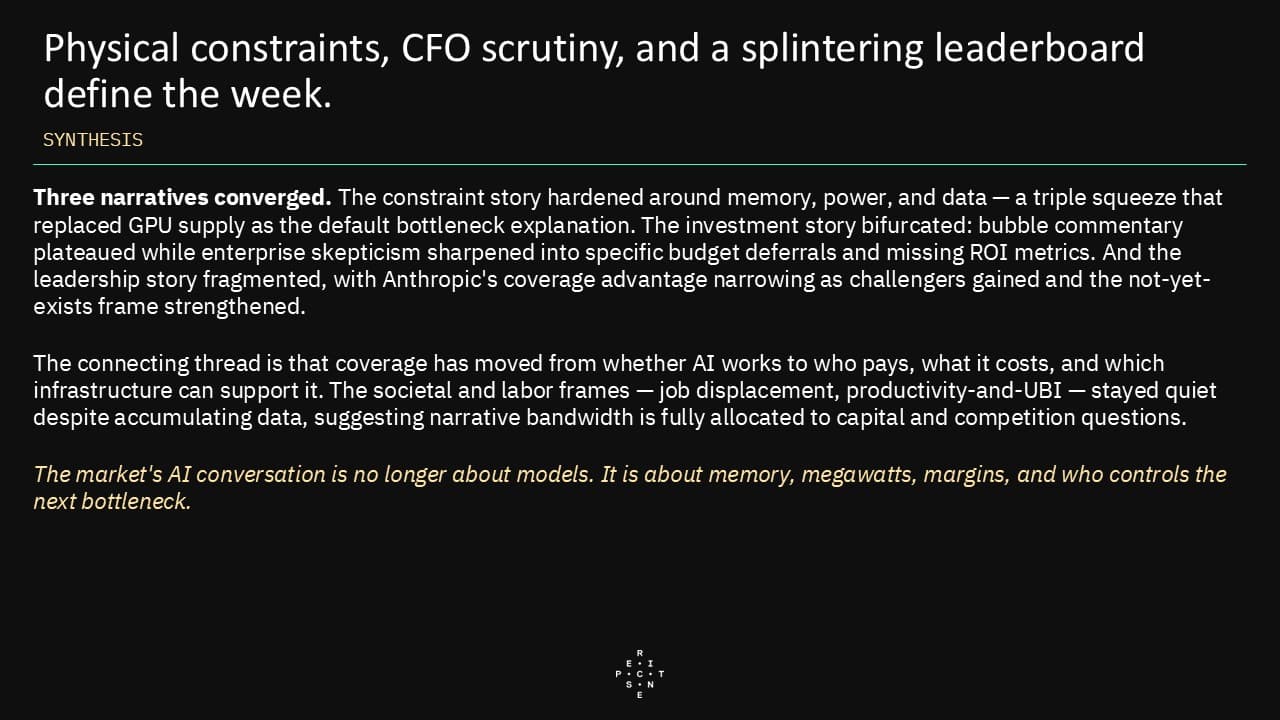
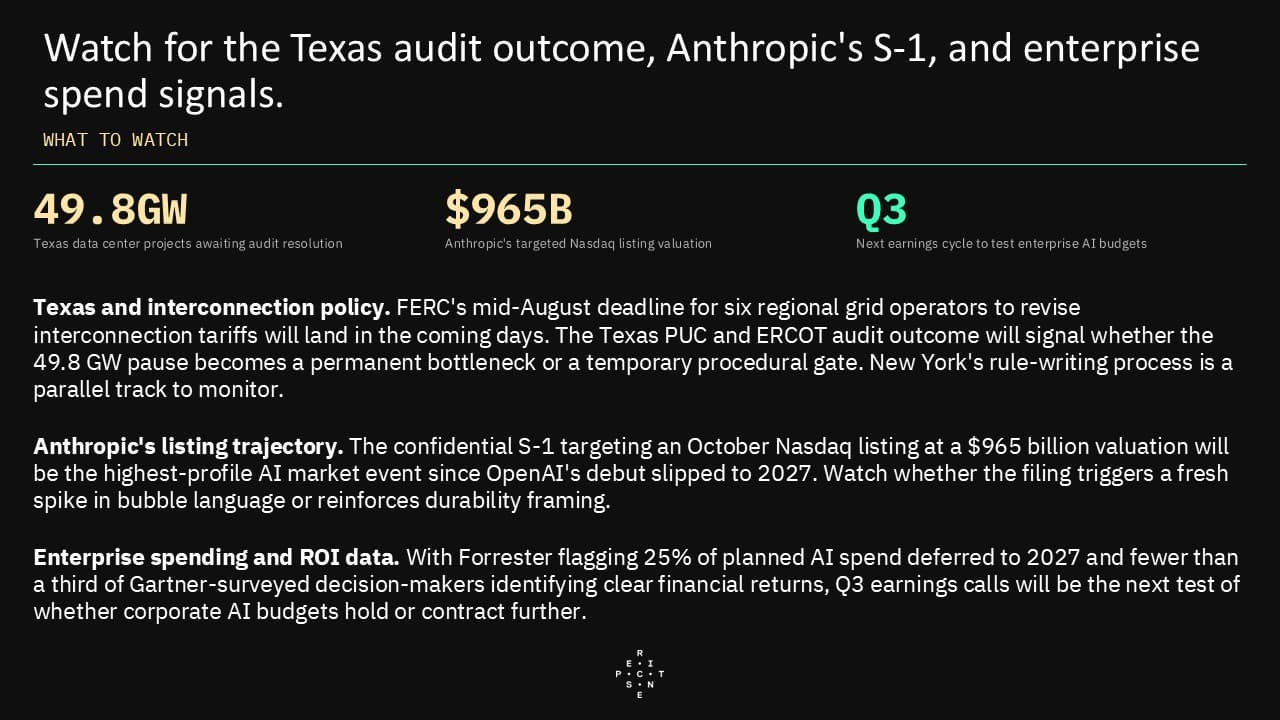
Coverage has relocated the bear case from technology to finance. Perscient's semantic signature tracking the density of language predicting that an AI investment collapse will crash overall markets posted the largest gain among market-framing signatures, carried by the IMF's stability warning, Dalio's "classic bubble" language, and the circular-financing critique now reaching Capitol Hill. Yet the signature tracking claims that AI hype is giving way to disappointment stayed flat and negative, which indicates that reporters are questioning who earns a return rather than whether the technology works. Conviction and alarm are growing simultaneously, not sequentially. The signature tracking language predicting a long-term AI investment supercycle recorded the single largest weekly gain in the entire set, moving out of negative territory at the same moment bubble language climbed. The press is staging a genuine two-sided argument heading into the Alphabet, Amazon and Apple prints, where the sell-side test has moved from growth to cash conversion. The bottleneck vocabulary has migrated from silicon to permission, power and memory. Language tracking GPU scarcity as a growth constraint sat below its long-term mean and has effectively left the conversation, while claims that opposition to large AI investments is increasing produced the highest reading in the entire set, powered by Oregon's statewide pause, Charlotte's extended moratorium and a flood of California local measures. Memory-shortage language cooled sharply on the week even though IDC and Michael Dell both describe worsening DRAM and HBM4 supply, suggesting that press attention is lagging the underlying constraint. Siting fights are still being covered as local disputes rather than a competitiveness emergency. The signature tracking arguments that national energy buildout will determine AI leadership rests near its long-term mean, which leaves a gap between the permitting friction documented in Section 2 and the geopolitical framing one might expect. Should interconnection queues and moratoriums persist, that gap is the most likely place for a new narrative to form. The leaderboard story has narrowed to one name while buyers are portrayed as disciplined rather than disillusioned.Anthropic's October 26 S-1 pushed the signature tracking claims of Claude's competitive lead to the dominant position, with OpenAI and Google framings both flat and negative; the filing's $80.7 billion half-year loss headline simultaneously feeds the risky-bet language described in Section 1. Meanwhile, the signature tracking corporate doubt about large AI spending strengthened even as claims of outright project failure weakened, and predictions about job destruction or creation remain deep in negative territory, leaving the week's coverage almost wholly financial and infrastructural.
Growth remains the most prevalent way financial media frames private credit, but the celebratory register has changed character: the expansion story is now told increasingly through retail and wealth-channel distribution — interval funds, retail BDCs, evergreen vehicles — and the vocabulary of democratization has begun to crowd in alongside the older institutional framing. Perscient's semantic signature tracking the density of language around opacity and systemic risk shows the strongest momentum of any frame in circulation, and its distinguishing claim is epistemic rather than empirical: the assertion is not that assets are impaired but that verification is impossible. Official-sector commentary from the IMF, the Bank of England, and the Financial Stability Board has lent this frame a credibility that journalistic skepticism alone would not have produced. The fastest-moving element of the entire discourse is a sub-narrative rather than a parent frame — the argument that bank balance sheets remain exposed to private credit through subscription lines, NAV facilities, and fund-level leverage, making the migration of risk out of the banking system partly illusory. Its trajectory suggests that it may soon stand as a dominant frame in its own right. Credit quality coverage has grown denser while remaining deliberately measured. First Brands and Tricolor function in the discourse as recurring proof points rather than isolated incidents, yet the governing adjective is still "idiosyncratic," and the clinical vocabulary of PIK ratios, amendments, and non-accruals keeps the framing forensic rather than alarmist. The most structurally interesting feature is that the growth, competition, credit quality, and risk frames are built from the same underlying facts and are increasingly held simultaneously by the same observers — articles open in one frame and close in another. Combined with the absence of any meaningful crisis language, this pattern reads as accumulated concern rather than acute alarm, and as genuine uncertainty rather than partisan division.