Private Credit PulseBiweeklyOct 20, 2026
Private Credit Pulse
Next release: November 03, 2026

Next release: November 03, 2026
The dominant frame has been rebuilt from growth to pressure. Coverage that once treated private credit as a yield story filling the void left by bank retrenchment now organizes itself around refinancing obligations, deferred cash interest, and redemption mechanics. Perscient's Semantic Signature tracking this cluster has become considerably denser over the trailing ninety days, and the movement comes primarily from the speed at which the pressure framing has reached outlets that previously covered the asset class through a returns lens. The maturity wall has acquired both a number and a harder vocabulary. Reporting has attached a circulating range of refinancing figures to a story that previously lacked a numerical anchor, and it has moved from aggregate exposure toward borrower-level distress in specific sectors and vintages. Pressure-framing terms such as "wall," "cliff," and "crunch" have displaced neutral descriptors at roughly double their prior rate across both trade and mainstream outlets. Payment-in-kind has been converted from a credit structure into a diagnostic test, and it is spreading faster than the story that contains it. The density of language presenting PIK income ratios as evidence of concealed distress now exceeds that of the parent maturity-wall framing, which is characteristic of frames offering a single number purportedly revealing hidden deterioration. This sub-narrative has escaped its specialist origins and appears in outlets that do not ordinarily engage with credit mechanics. The three components function together as a reusable template rather than as separate arguments. Maturity wall, PIK accumulation, and the redemption mismatch at semi-liquid retail vehicles are deployed in consistent sequence, supported by an antagonist structure in which retail investors and distribution channels occupy identifiable roles and regulatory examination priorities are cited as validation. Source diversity has widened from credit trade press and sell-side research into general business, policy, and consumer-facing media, an expansion that typically precedes either regulatory action or a market event confirming the frame. The managers' rebuttal is not gaining ground, which compounds the durability problem. Perscient's measurement of the counter-narrative articulated by the largest alternative managers remains well below the pressure narrative and has been flat across the window, reflecting the harder rhetorical position of explaining why apparent warning signs are benign. Combined with the measured rather than alarmist tone of the pressure coverage, this asymmetry suggests the frame will persist through multiple news cycles, with contrary data points absorbed as exceptions rather than treated as refutation.
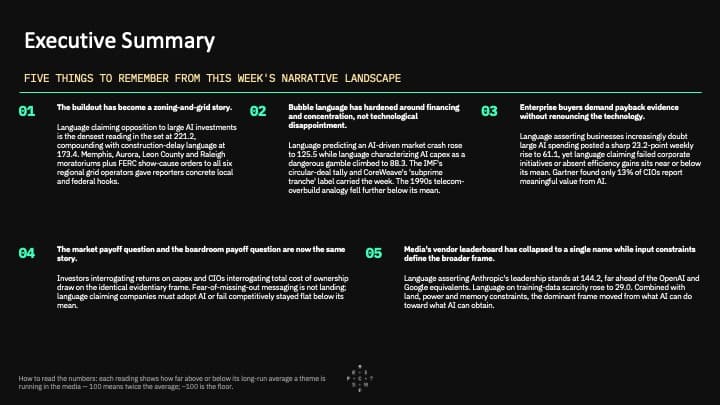
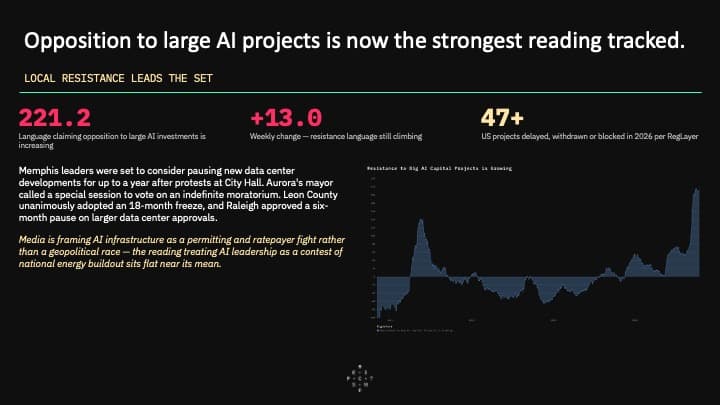
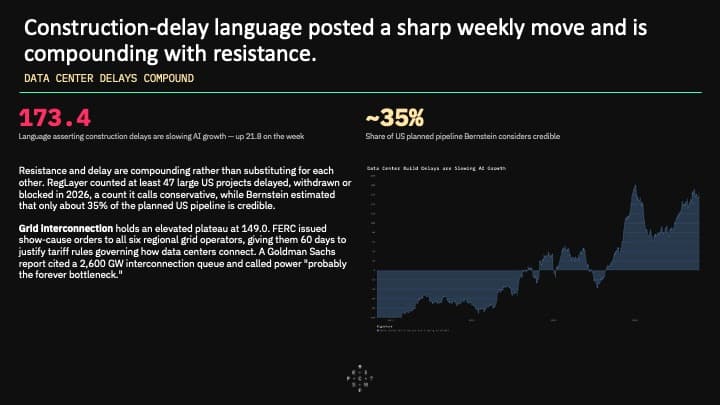
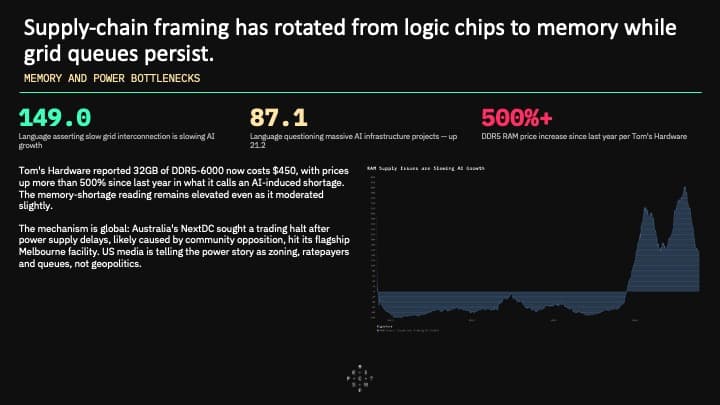
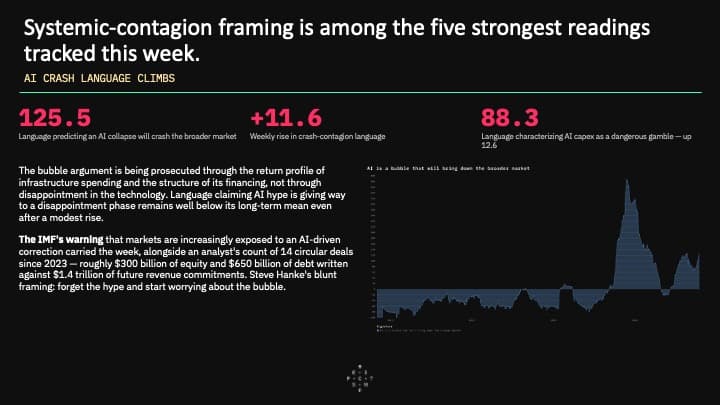
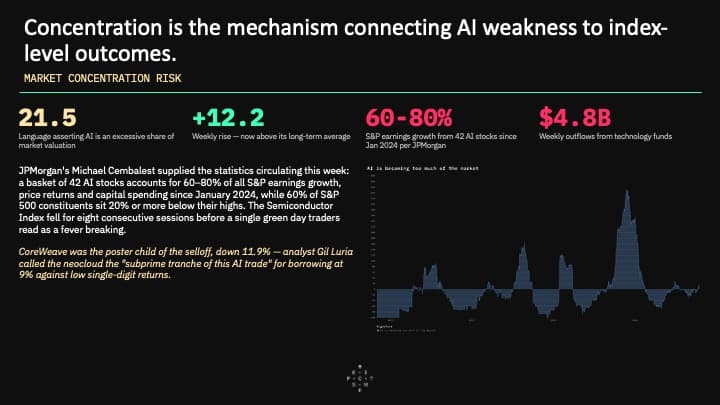
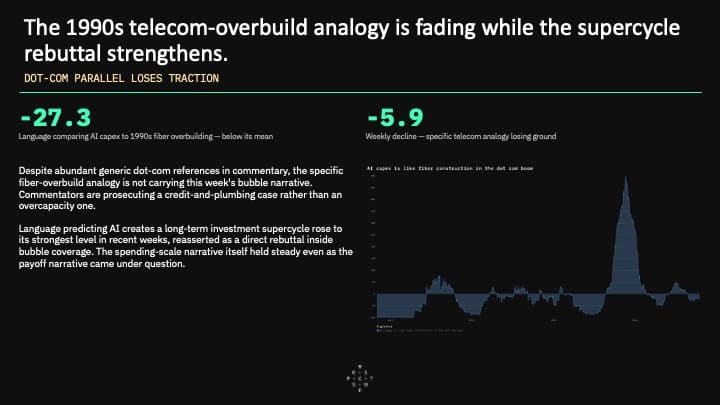
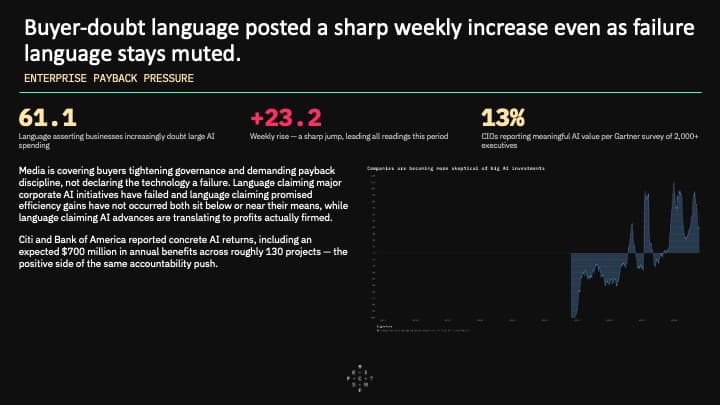
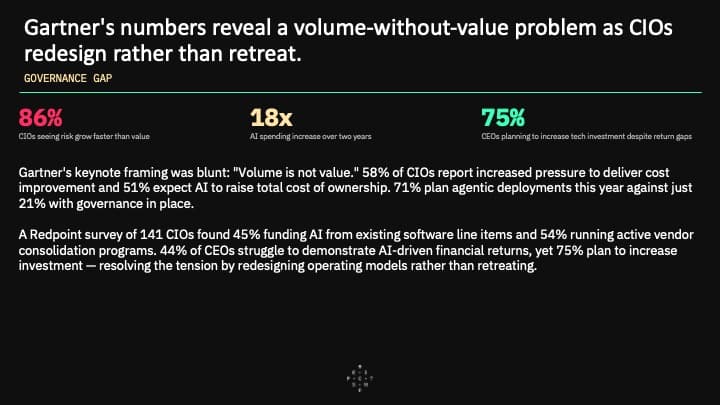
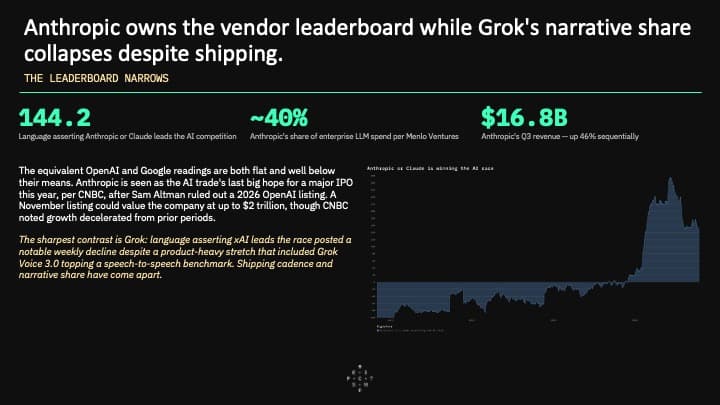
Coverage has recast AI as a balance-sheet story rather than a technology story. Perscient's semantic signature tracking language predicting that an AI investment collapse will crash overall markets posted the week's second-largest jump, and the signature tracking claims that AI makes up an excessive share of market valuation returned to its long-term norm. Journalists anchored this framing in the IMF's Global Financial Stability Report, hyperscaler debt issuance, and OpenAI's revised revenue disclosure. Crucially, the disappointment framing stayed dormant and claims that AI advances convert into company profits strengthened, which means reporters are questioning how the buildout is financed rather than whether the technology works. Faith in the long horizon is quietly thinning even while near-term enthusiasm holds. Signatures tracking the supercycle thesis and the durability of the AI investment theme both eased, and the comparison to 1990s telecom overbuilding registered no movement whatsoever. The press is reaching for systemic-contagion language instead of the familiar overbuild analogy, suggesting an emerging frame in which the risk is not wasted capital but a concentrated market that transmits a correction outward. Opposition to AI buildouts remains the loudest story in the entire signature set and has migrated into electoral politics.Coverage this week centered on gubernatorial campaign advertising, the Raleigh moratorium, the Texas permitting pause, and the New York statewide moratorium tour, alongside reporting that a quarter-trillion dollars of planned investment has been canceled this year. Siting decisions are now being written up as political contests rather than as construction milestones. The constraint story has moved from silicon to the grid, and the geopolitical framing of energy has collapsed into a local one. Only the grid-interconnection signature strengthened among the constraint set, GPU-shortage language sat flat and well below its norm, and the claim that national energy infrastructure will decide AI leadership recorded the sharpest single-week decline of any signature tracked. Taken together with the political coverage, energy is being narrated as a zoning, ratepayer, and queue problem inside American communities rather than a contest between nations. Leadership coverage is consolidating around fewer names, and training-data supply is emerging as the new technical dividing line. Claims that Anthropic leads the field remained the dominant leadership framing, OpenAI and Google leadership language stayed flat and subdued, and the suggestion that the eventual winner has not yet been founded fell further. Meanwhile, language asserting that limited access to high-quality novel datasets is slowing AI growth posted the largest gain among the input-constraint signatures. With transformation framings around jobs, medicine, education, and journalism all sitting below their norms, incumbent-versus-incumbent comparison through IPO season looks set to crowd out the broader societal storyline, and data provenance is the likeliest axis of that comparison.