Markets Pulse
WeeklyJuly 28, 2026

AI Pulse July 21, 2026

7.21AIPulse1.jpg
7.21AIPulse2.jpg
7.21AIPulse3.jpg
7.21AIPulse4.jpg
7.21AIPulse5.jpg
7.21AIPulse6.jpg
7.21AIPulse7.jpg
7.21AIPulse8.jpg
7.21AIPulse9.jpg
7.21AIPulse10.jpg
7.21AIPulse11.jpg
7.21AIPulse12.jpg
7.21AIPulse13.jpg
7.21AIPulse14.jpg
7.21AIPulse15.jpg
7.21AIPulse16.jpg
7.21AIPulse17.jpg
7.21AIPulse18.jpg

EXECUTIVE SUMMARY

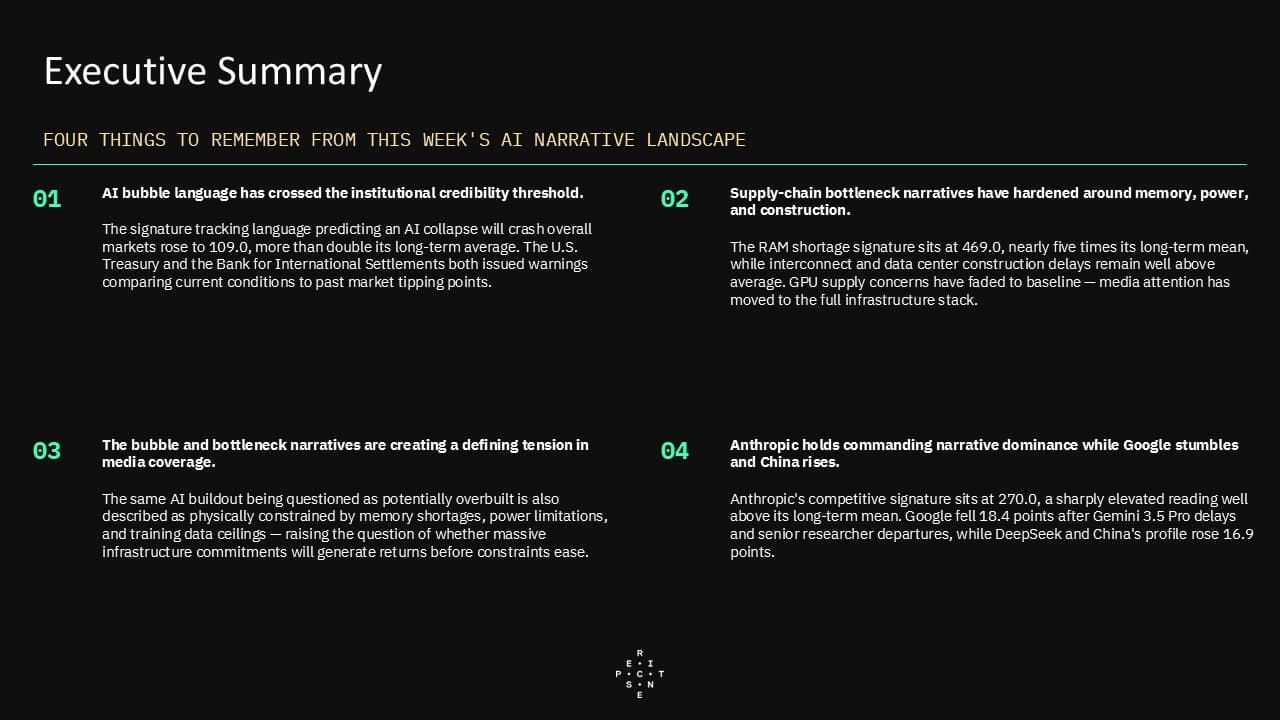
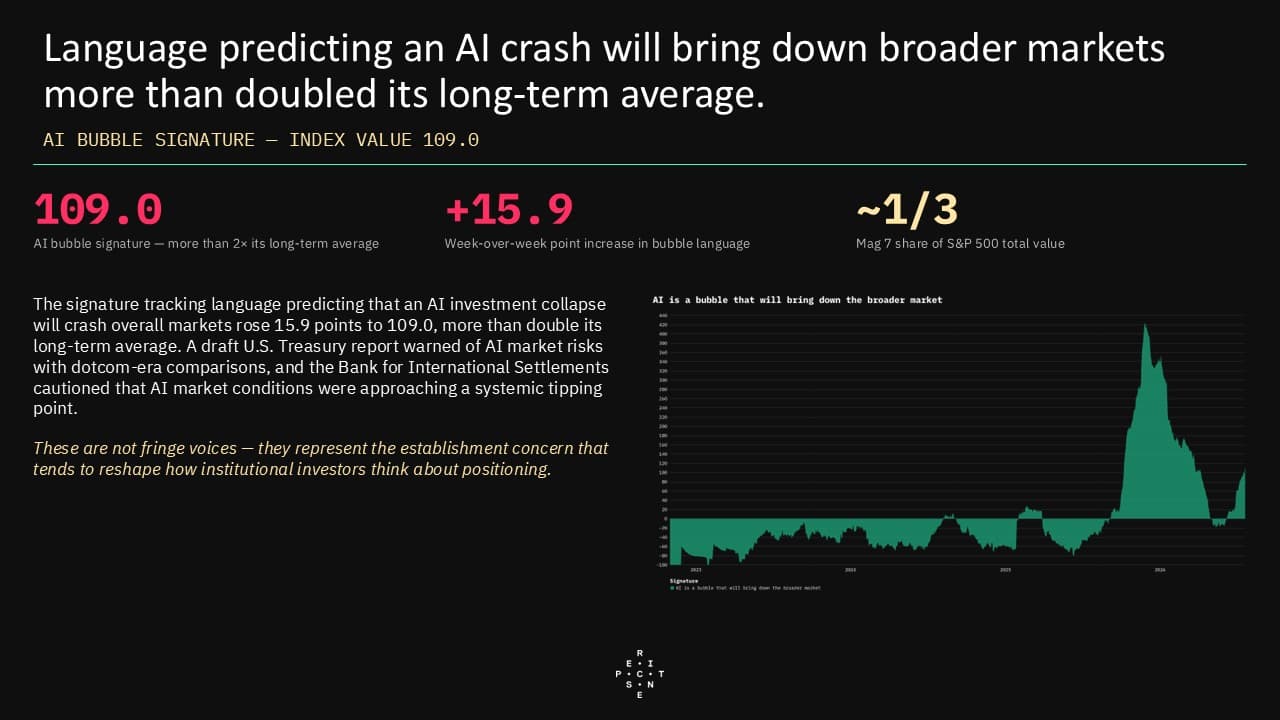
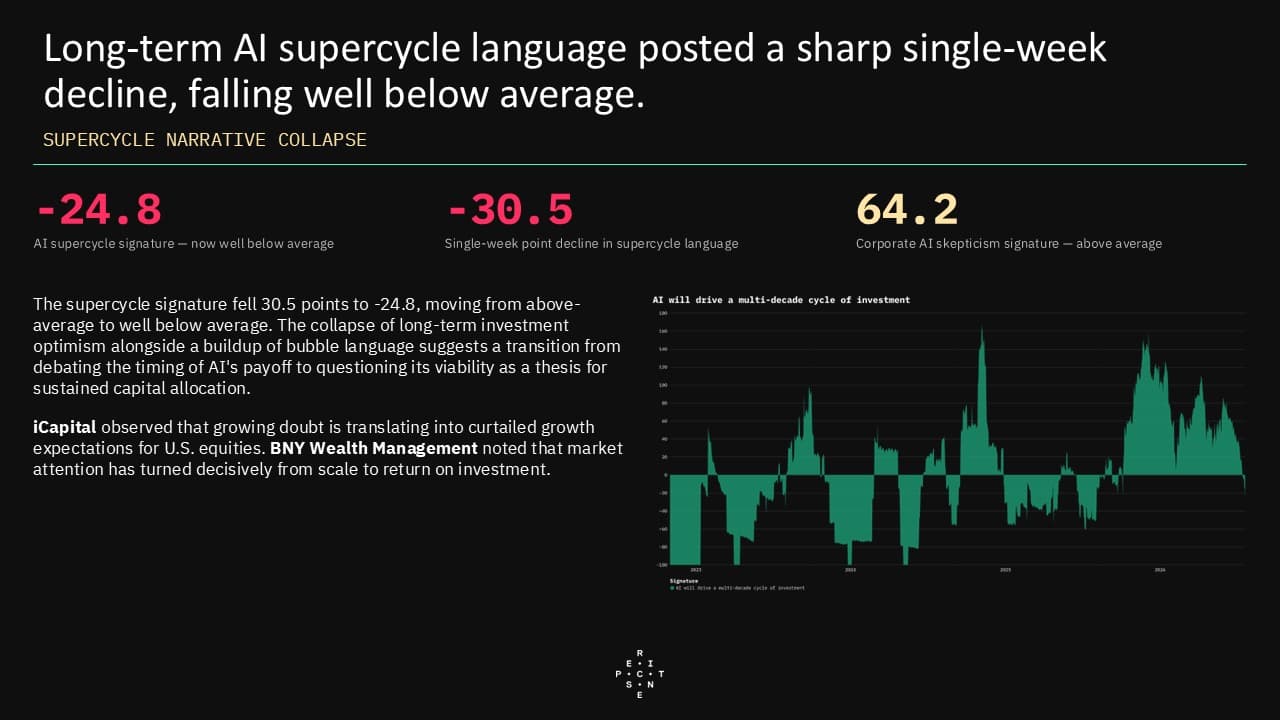
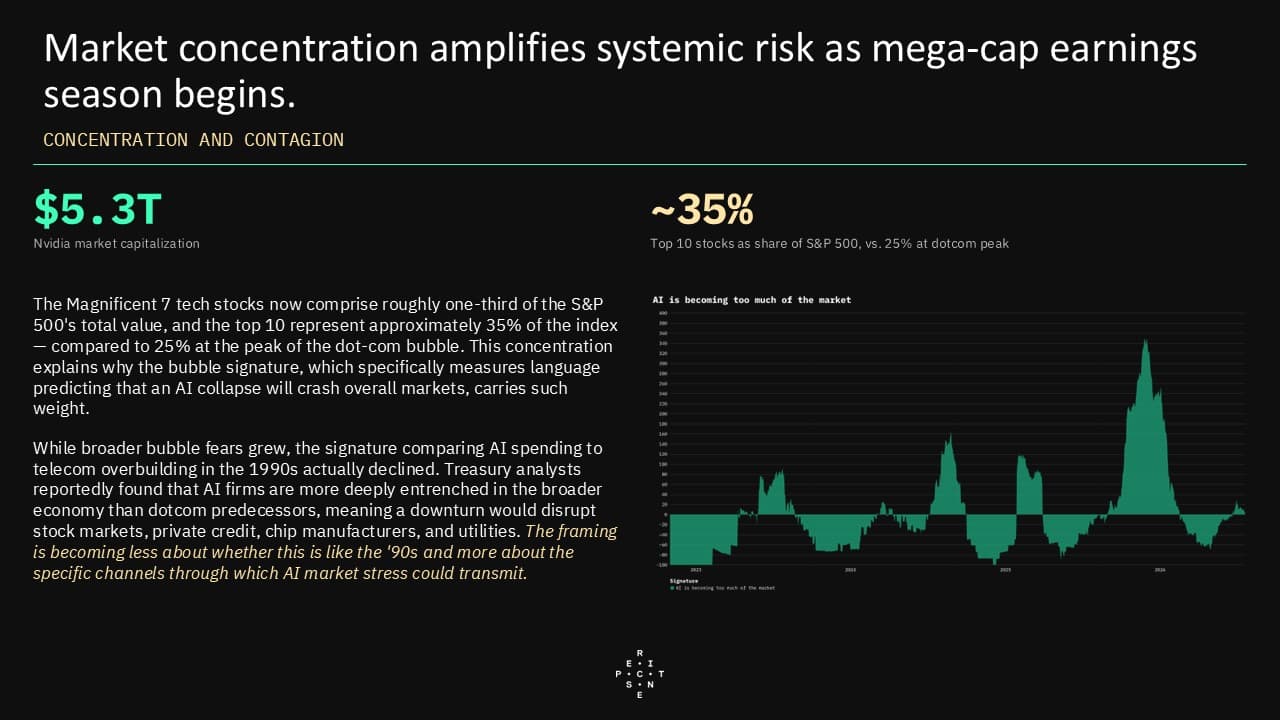
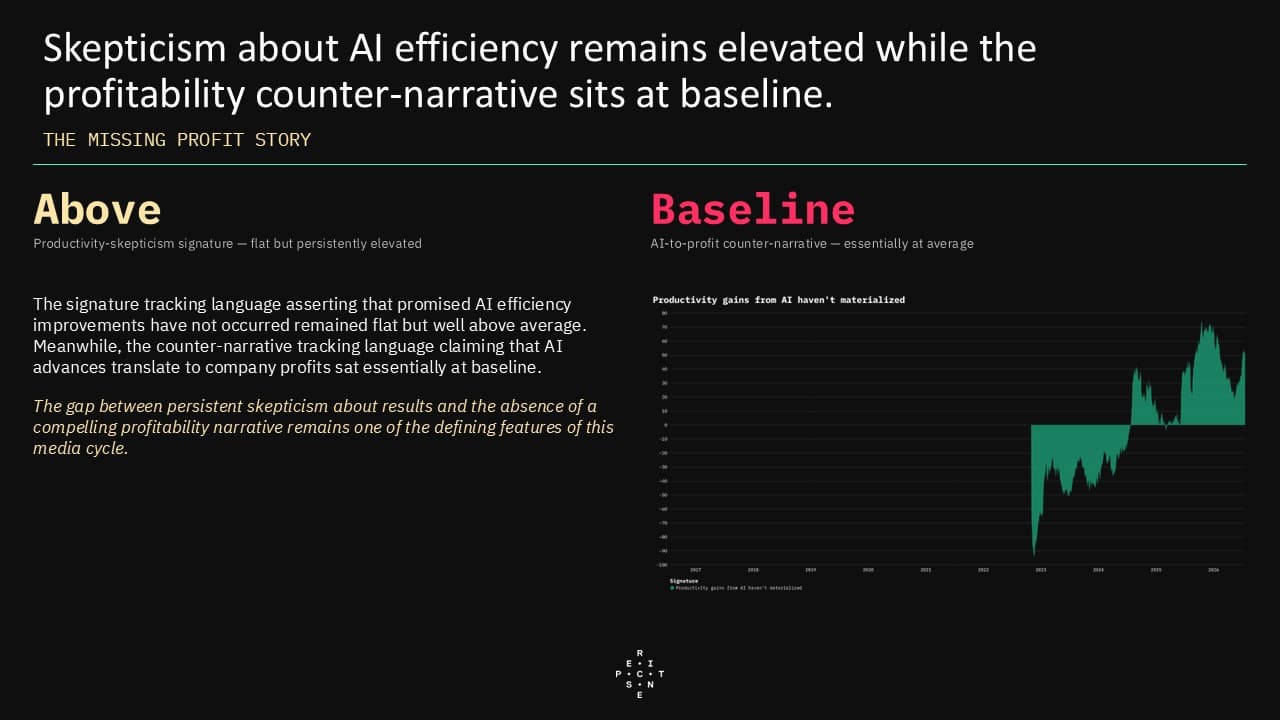
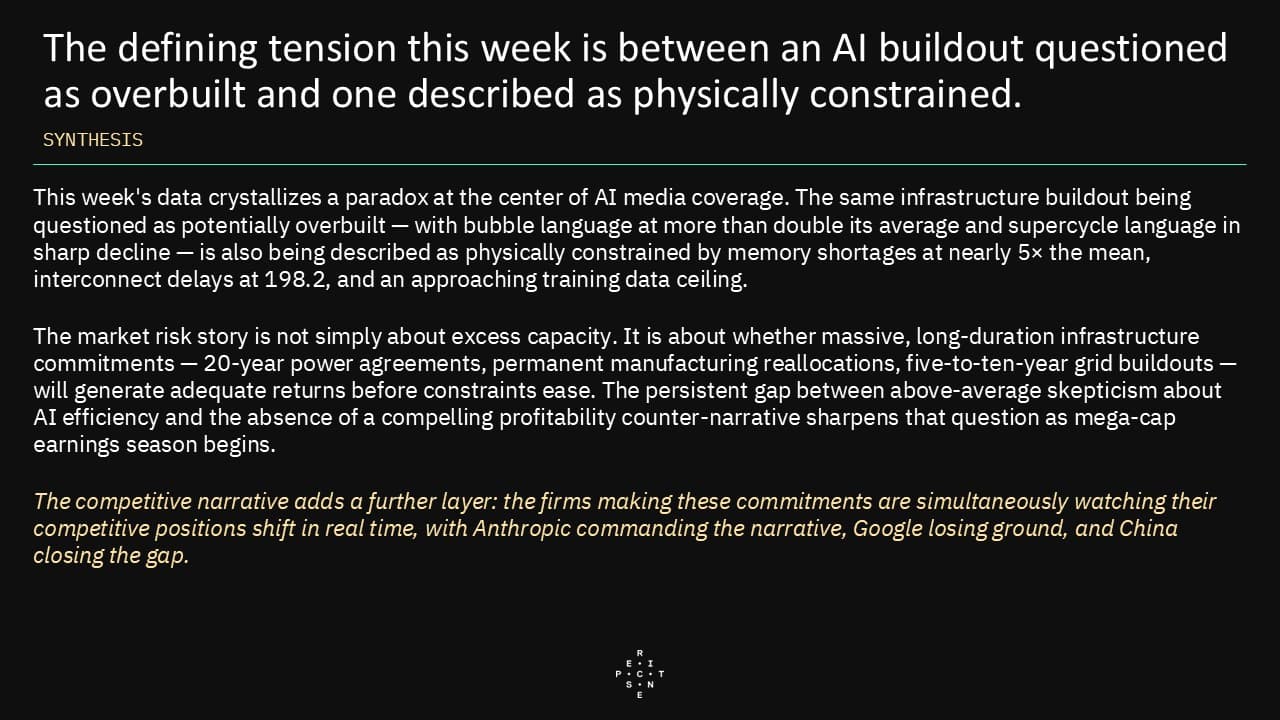
  • Media coverage of AI investment has shifted from debates about timing and valuation to structural doubt about the trade itself. Language predicting an AI-driven market crash rose sharply, while conviction that AI represents a durable multi-decade investment theme suffered the largest weekly collapse of any tracked narrative. Institutional alarm—from the Treasury Department, the Bank for International Settlements, and Bank of America's Fund Manager Survey—has broadened from isolated warnings to a coordinated framing of systemic fragility, even though dotcom-era analogies appear to be losing their hold in favor of forward-looking risk frameworks that treat AI concentration as potentially novel in its scale and financial entanglement.
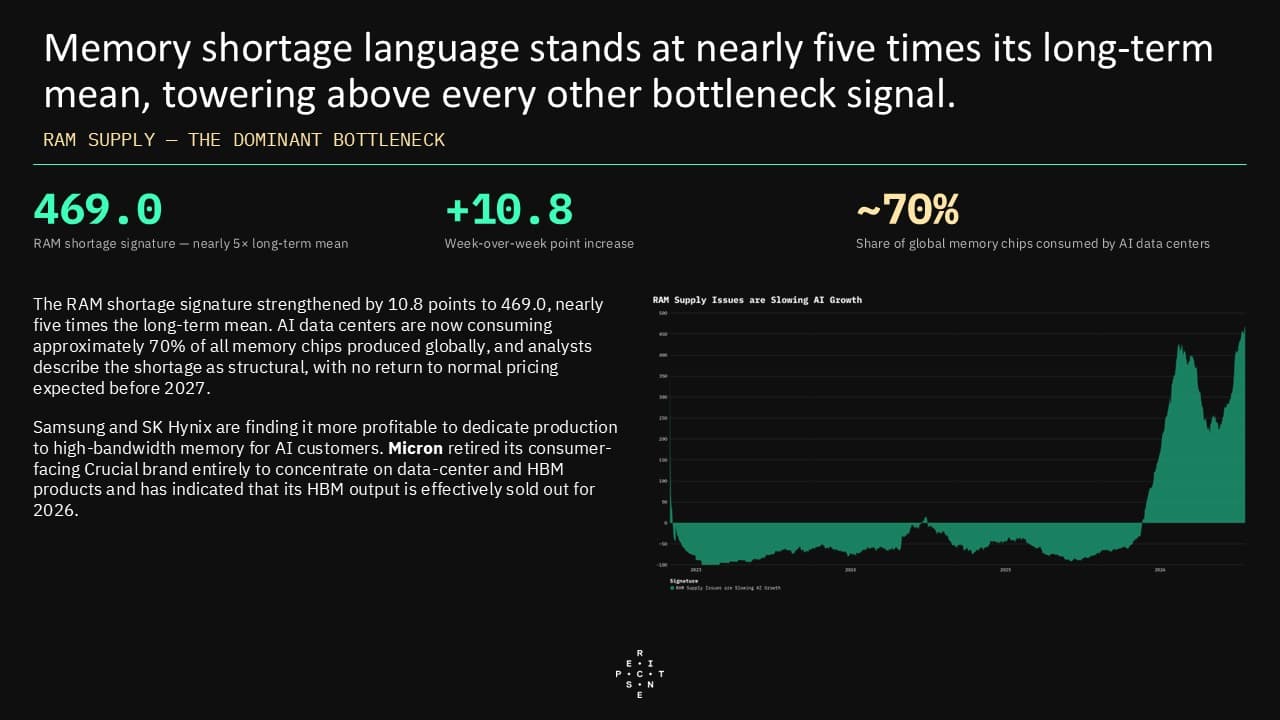
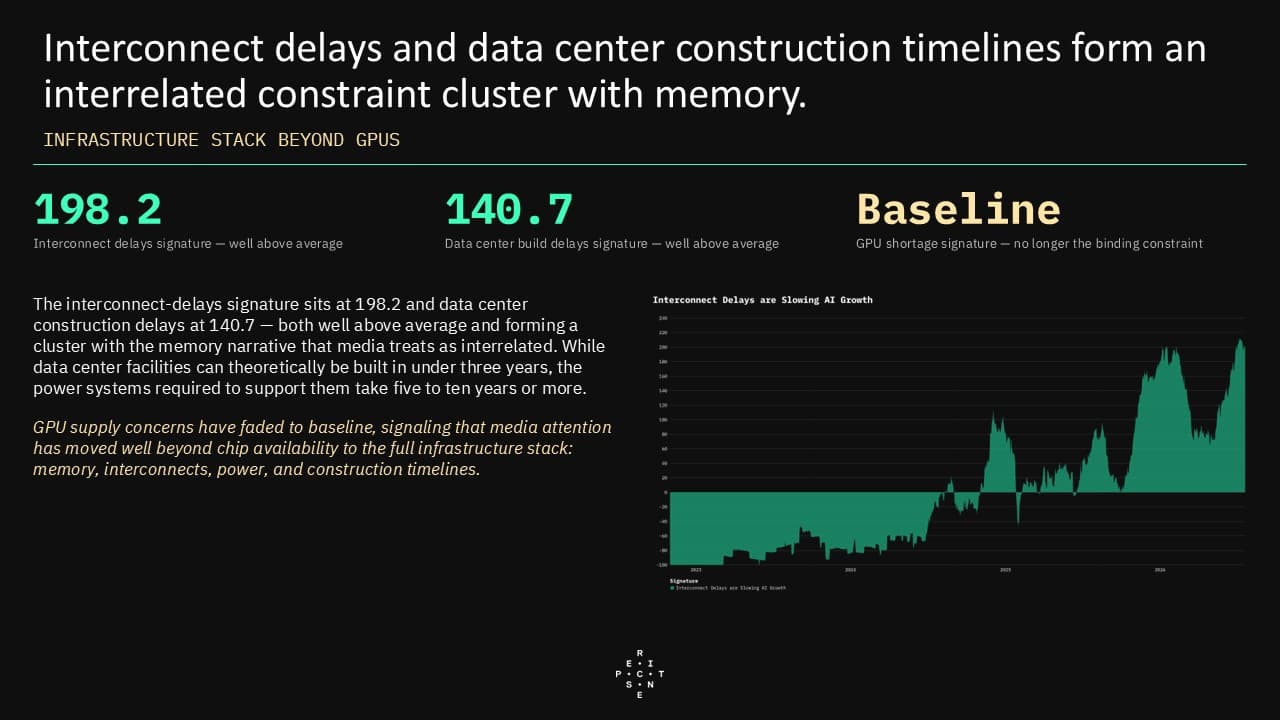
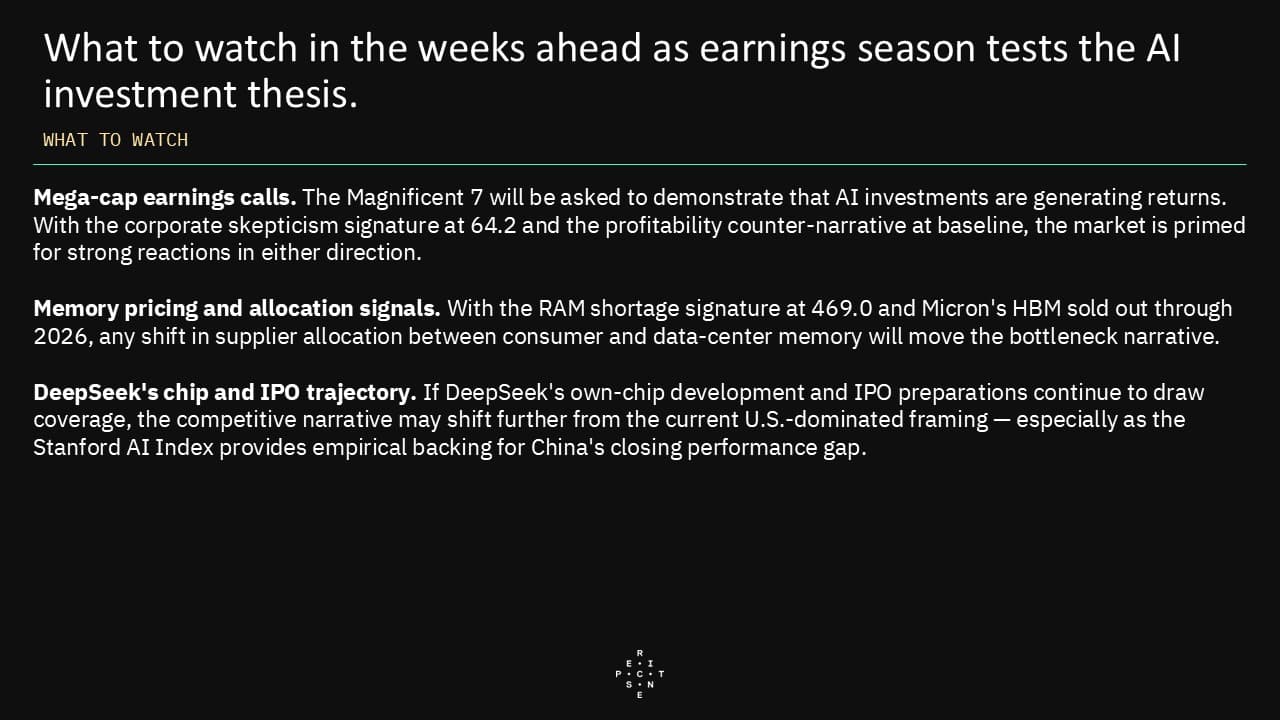
  • Three infrastructure bottleneck narratives—memory chip shortages, power grid interconnection delays, and data center construction slowdowns—form the most elevated cluster in the entire tracking universe, describing a widening gap between committed capital and the physical capacity needed to absorb it. GPU scarcity, once the dominant constraint narrative, has fallen to baseline levels, indicating that the binding constraints on AI deployment have moved decisively downstream from chips to power, memory, and grid infrastructure. Memory chip shortage language alone sits at nearly five times its long-term mean, reflecting structural supply reallocations and price increases of up to 419% year over year.
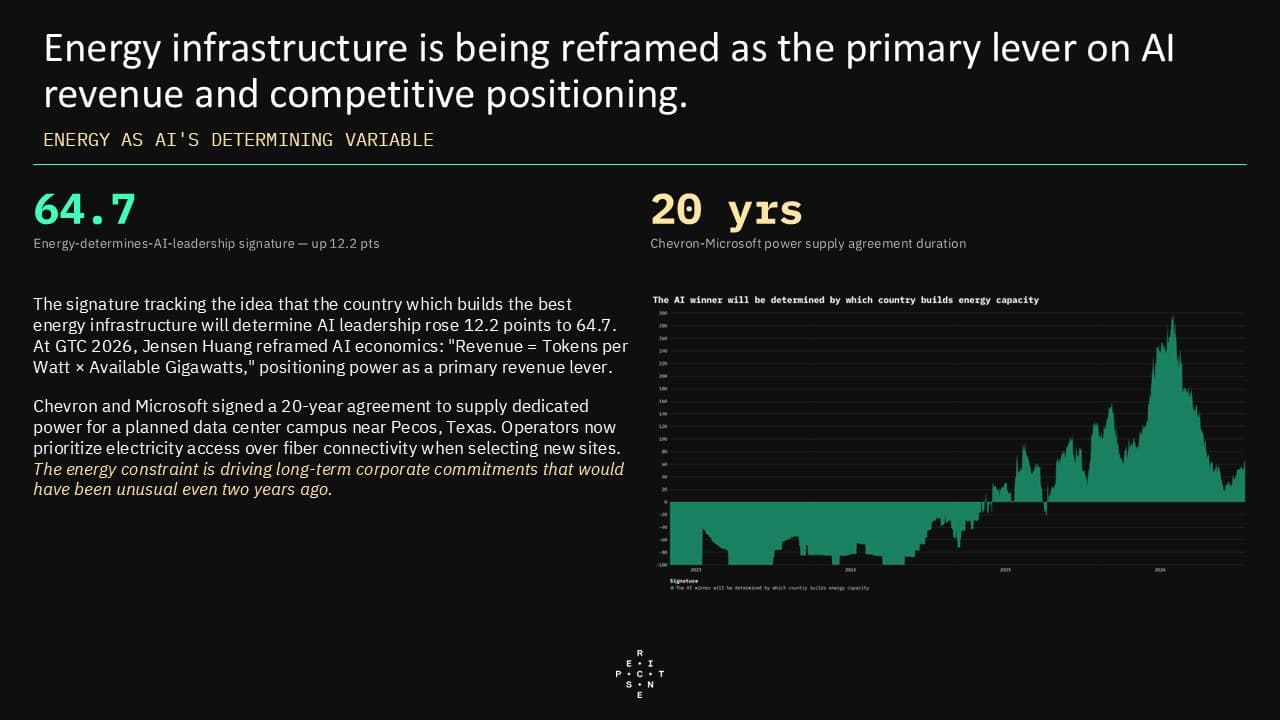
  • The convergence of rising bubble fears and persistent physical bottlenecks creates a compounding risk. Even if financial sentiment stabilizes, the multi-year timelines for transformer deliveries, grid interconnections, and fabrication plant construction mean that capital already committed may not translate into deployable capacity until well into 2028—a mismatch that could accelerate repricing if hyperscalers begin guiding down capital expenditure plans during this week's earnings reports. Growing language asserting that the country with the best energy infrastructure will determine AI leadership suggests that media coverage increasingly treats physical constraints as geopolitically decisive rather than merely logistical.
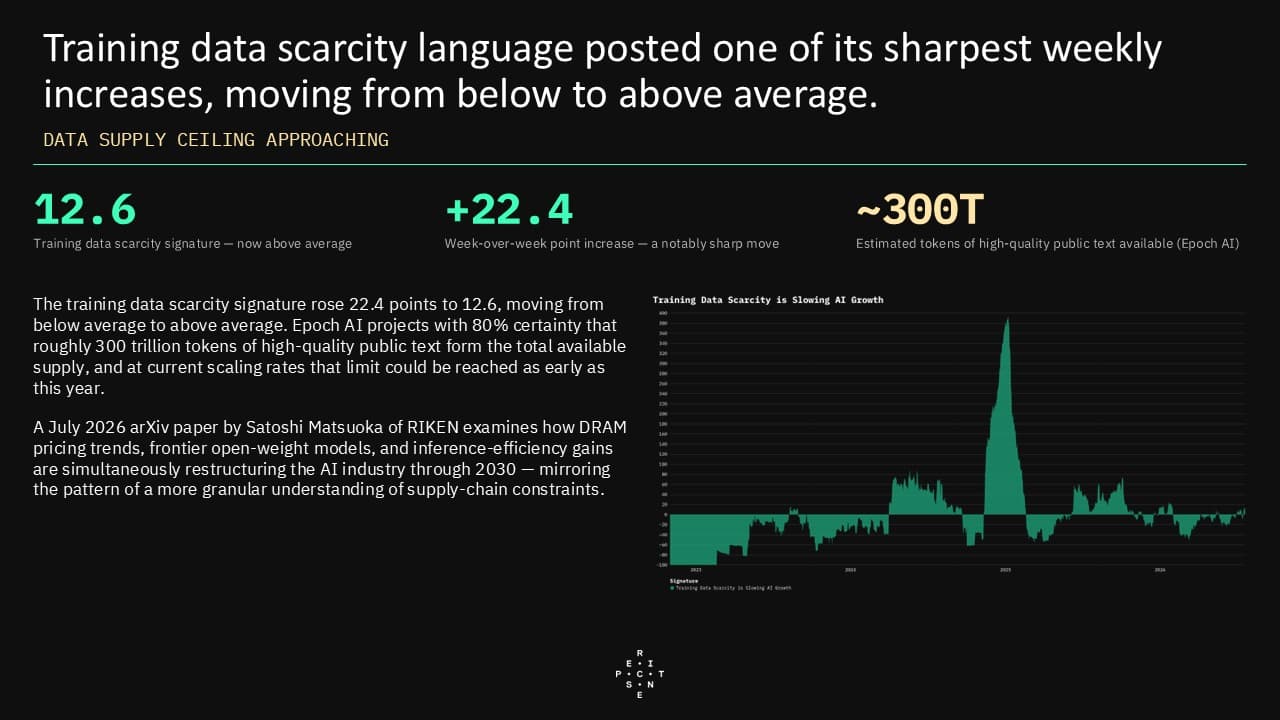
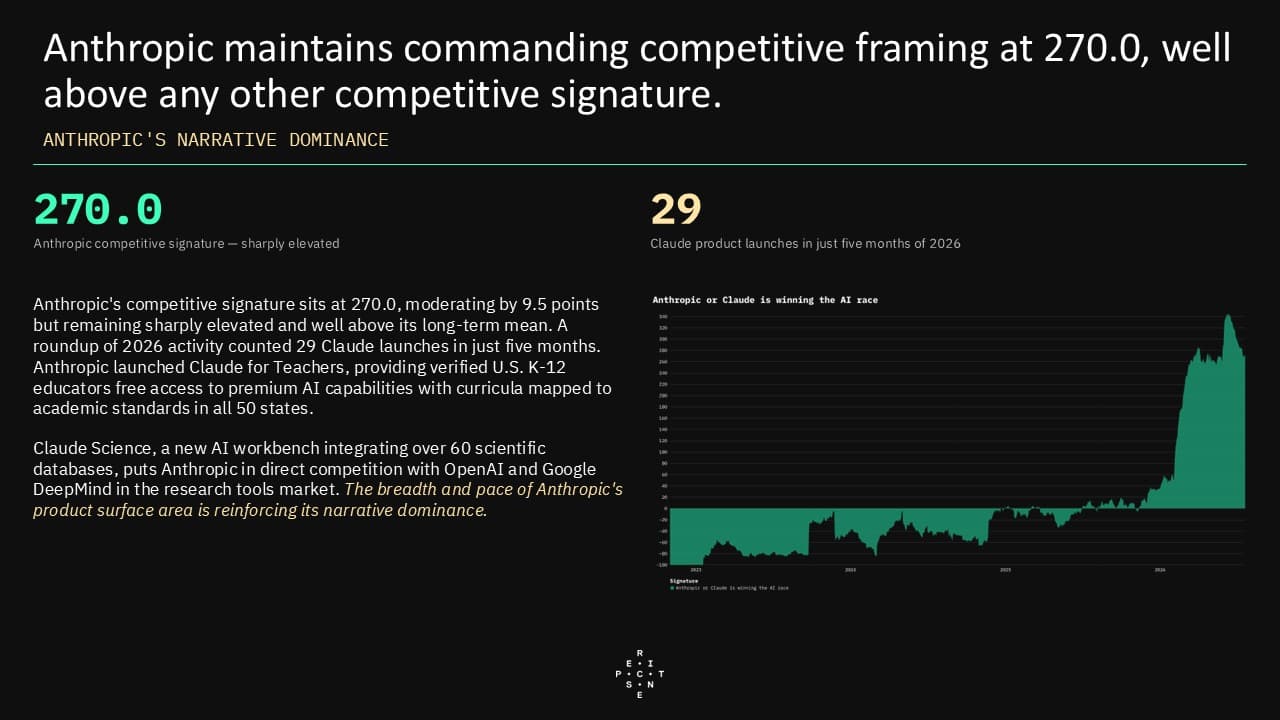
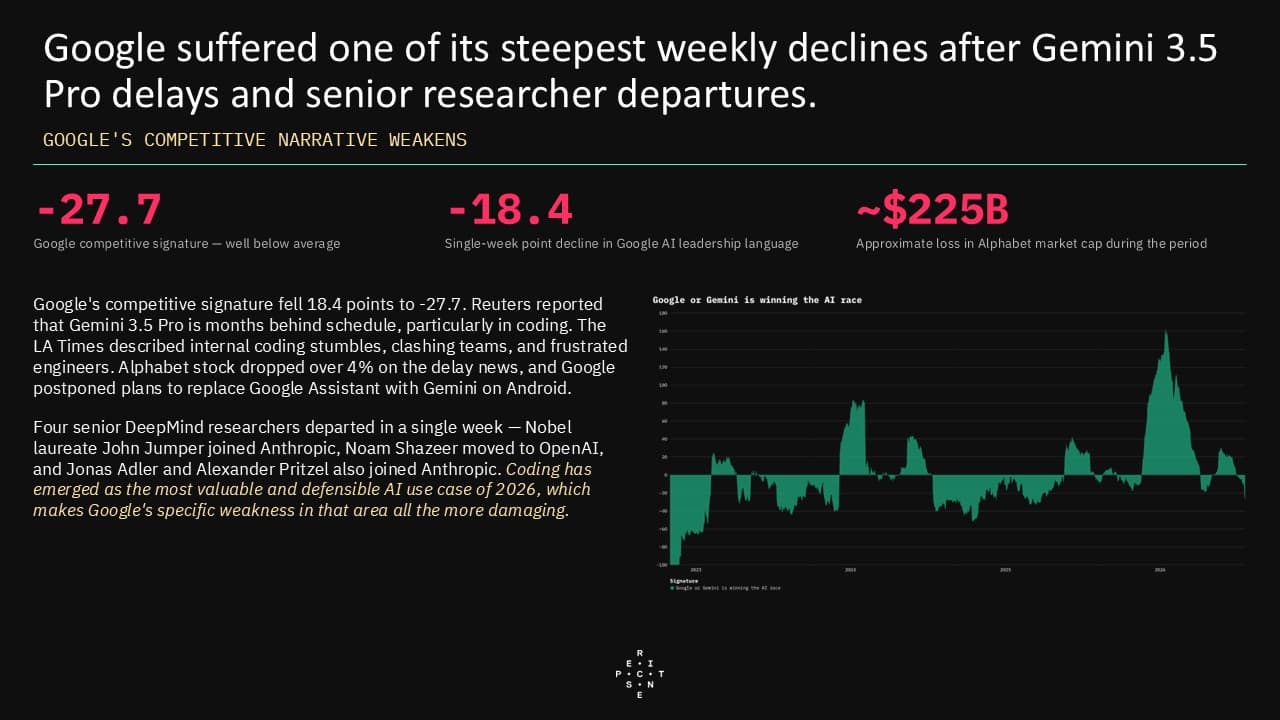
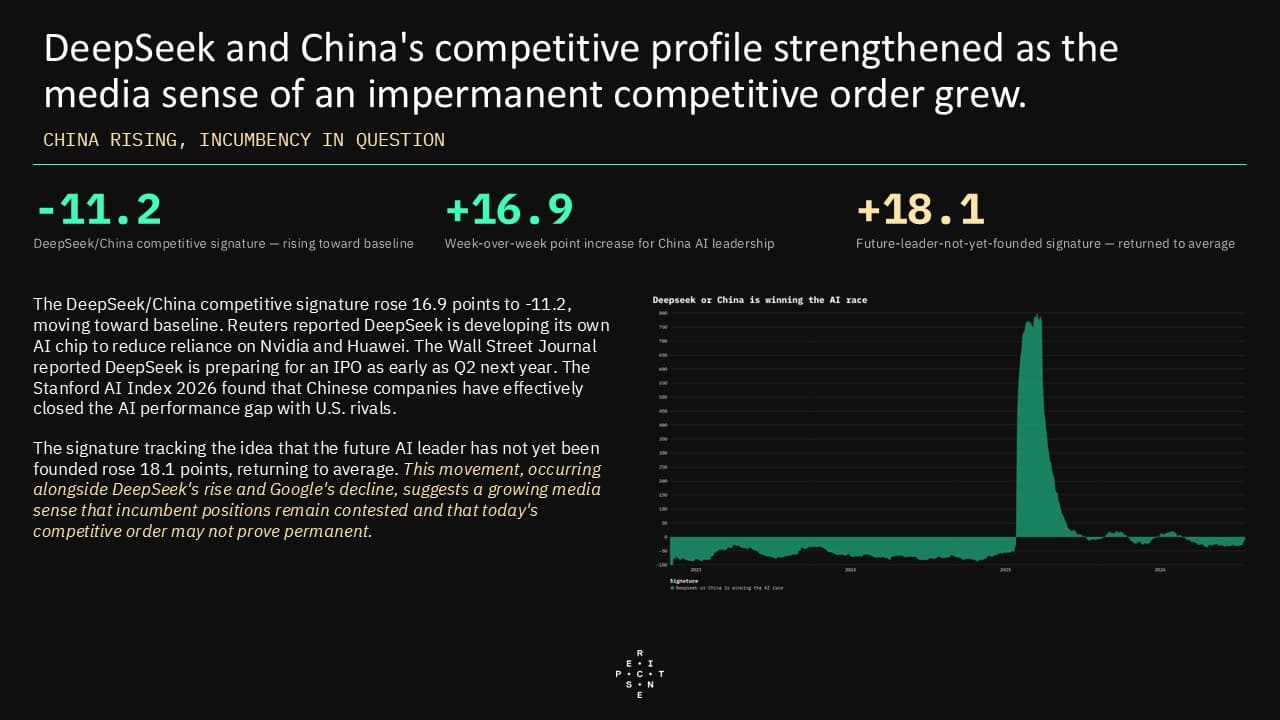
  • The competitive leadership narrative is undergoing a material reshuffling. Anthropic maintains dominant but slightly declining media positioning, Chinese competitors—particularly DeepSeek and Moonshot AI—are gaining ground rapidly, and Google's leadership narrative suffered one of the week's sharpest declines. Growing media sentiment that the eventual AI leader may not yet exist suggests that coverage increasingly treats the competitive field as contested rather than settled, a perception reinforced by the approaching exhaustion of high-quality training data, which could favor companies with proprietary data access over those reliant on scale alone.

Recent Pulses

Markets PulseWeeklySep 22, 2026

Markets Pulse September 15, 2026

The regime-change story arrives without any accompanying fear language. Every flight-to-safety signature — Treasurys, Swiss franc, yen, gold, money market funds — sits deep in negative territory, geopolitical and monetary policy uncertainty signatures were flat, and risk-on and risk-off readings have converged to nearly the same level just below zero. Media are narrating a supply shock, a five-percent ten-year, and a first hike since 2023 while conspicuously declining to counsel defensive positioning. Election-season transfer proposals collided with a hardening sovereign-risk story, and media asserted both outcomes at once. The helicopter-money signature registered the largest single move in the file, and stimulus-check predictions rose with it, yet signatures tracking debt paydown, deficit reduction, and austerity legislation also strengthened in the same week, while fiscal policy uncertainty remained flat. Commentators are expressing conviction about incompatible fiscal futures rather than doubt. Simultaneously, signatures tying runaway spending to higher Treasury yields, and those linking bond weakness to deficits and unfunded tax cuts, all gained, and claims that Treasurys are pricing genuine default risk moved into positive territory. Taken together, Sections 1 and 2 describe a media framework in which monetary and fiscal policy are pulling in opposite directions. Coverage pairs a hawkish Fed responding to oil-driven inflation with a proposed trillion-dollar household giveaway, and the reserve-currency channel sharpened alongside it: the signature tying dollar-status threats specifically to debt sustainability rose while the generic version held flat. Claims that White House pressure on foreign Treasury holders is deterring buyers remain the densest reading in the entire file, even as it eased slightly, and official-sector gold substitution language stayed elevated without accelerating further. Tariff politics are running in reverse, and the war has been absorbed into the same affordability argument. The signature tracking broad public opposition to tariffs climbed to one of the highest standings in the file while claims of public support weakened further, and the stated rationale rotated decisively: reshoring-manufacturing arguments dropped hard while "make other countries pay their fair share" and negotiating-leverage framings gained. Directional language turned two-sided for the first time in months. Bridging Sections 1 and 3, voter coverage now treats tariffs and the conflict as a single price story, which the K-shaped-economy framing organizes into a midterm affordability fight — notably, the market version of that bifurcation narrative eased even as chip stocks sold off, and the argument that investors have no alternative to US large-cap growth has effectively vanished from coverage.

Markets PulseWeeklySep 22, 2026

Markets Pulse

Next release: September 29, 2026

Private Credit PulseBiweeklySep 22, 2026

Private Credit Pulse

Next release: October 06, 2026