Markets Pulse
WeeklyJuly 14, 2026

AI Pulse July 07, 2026

7.01AIPulse1.jpg
7.01AIPulse2.jpg
7.01AIPulse3.jpg
7.01AIPulse4.jpg
7.01AIPulse5.jpg
7.01AIPulse6.jpg
7.01AIPulse7.jpg
7.01AIPulse8.jpg
7.01AIPulse9.jpg
7.01AIPulse10.jpg
7.01AIPulse11.jpg
7.01AIPulse12.jpg
7.01AIPulse13.jpg
7.01AIPulse14.jpg
7.01AIPulse15.jpg
7.01AIPulse16.jpg
6.30AIPulse17.jpg
6.16AIPulse18.jpg

EXECUTIVE SUMMARY

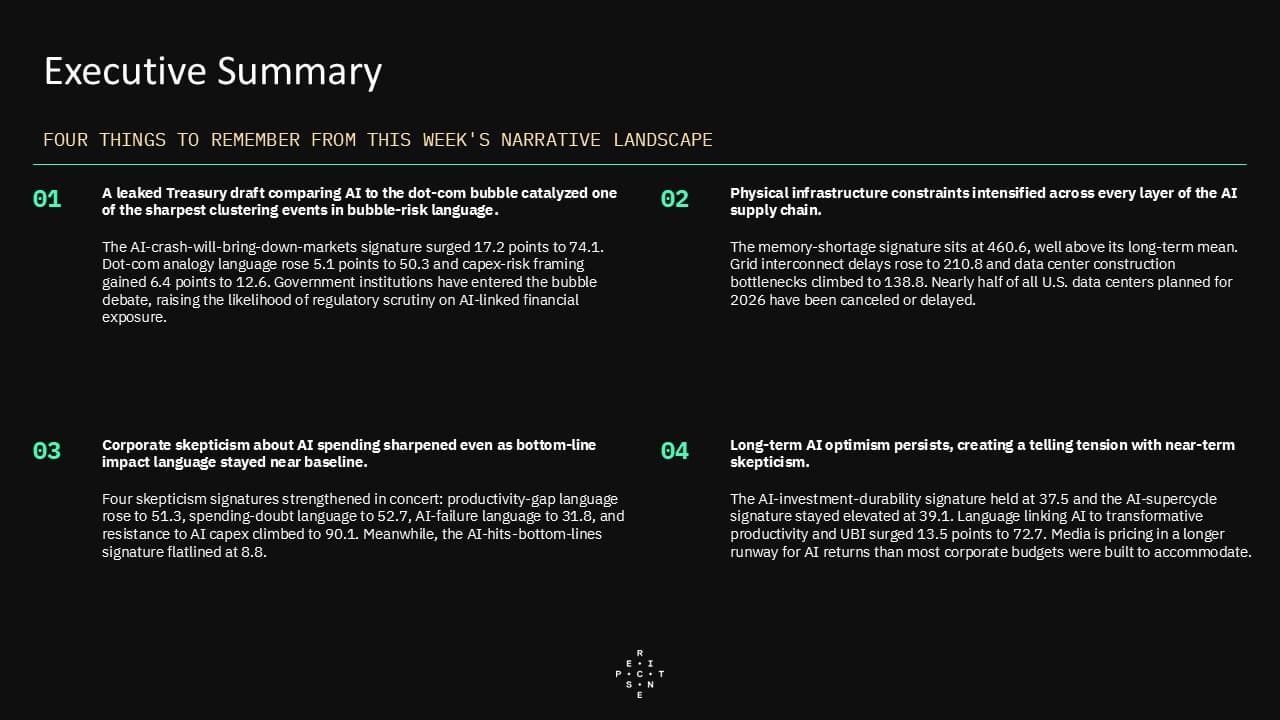
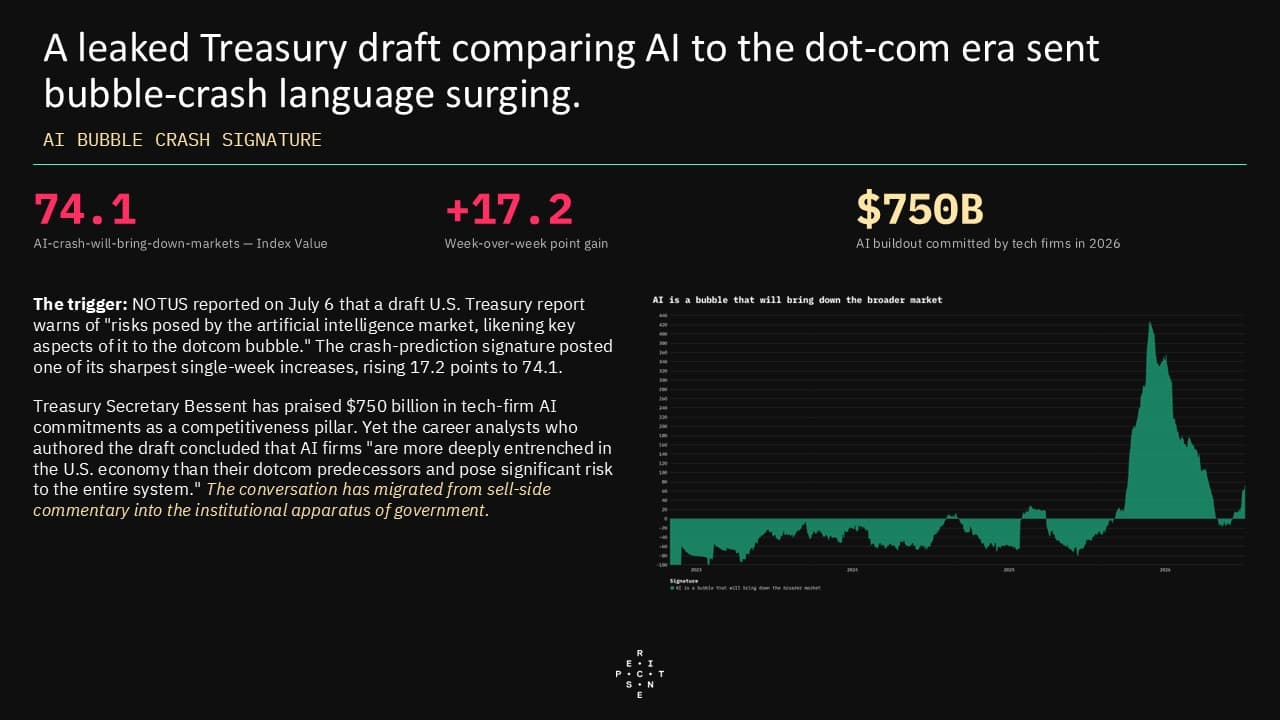
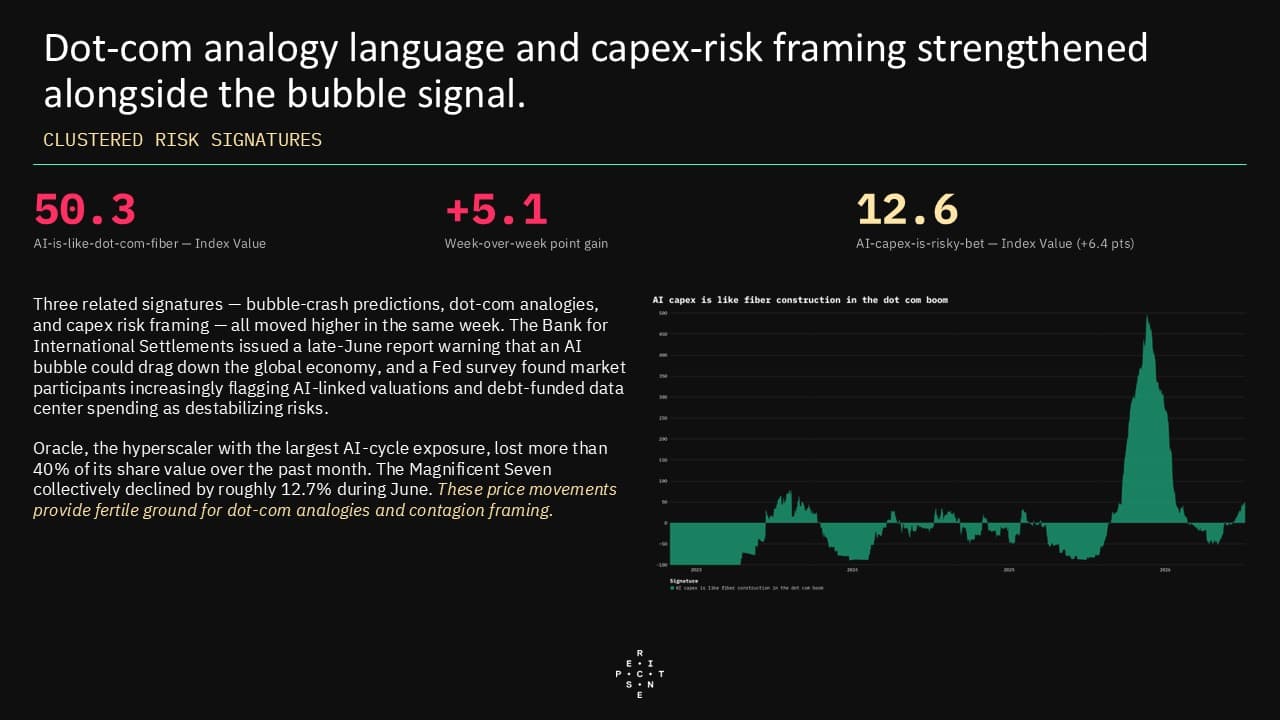
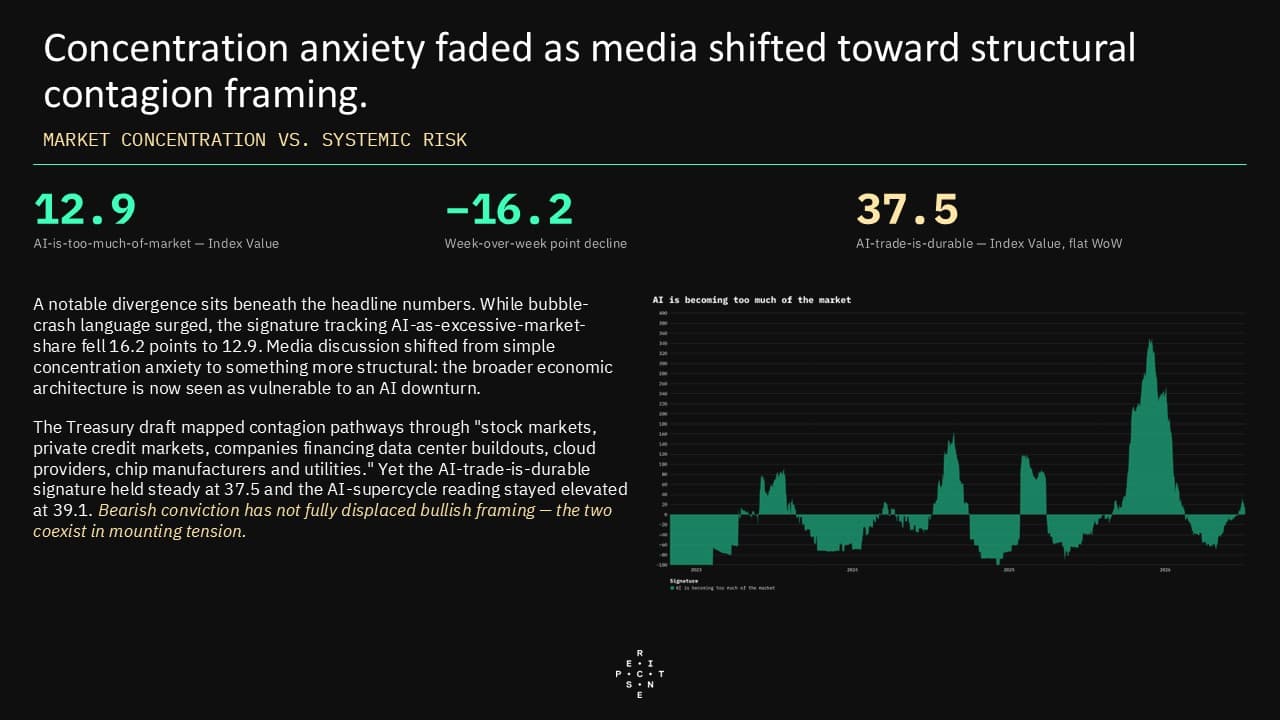
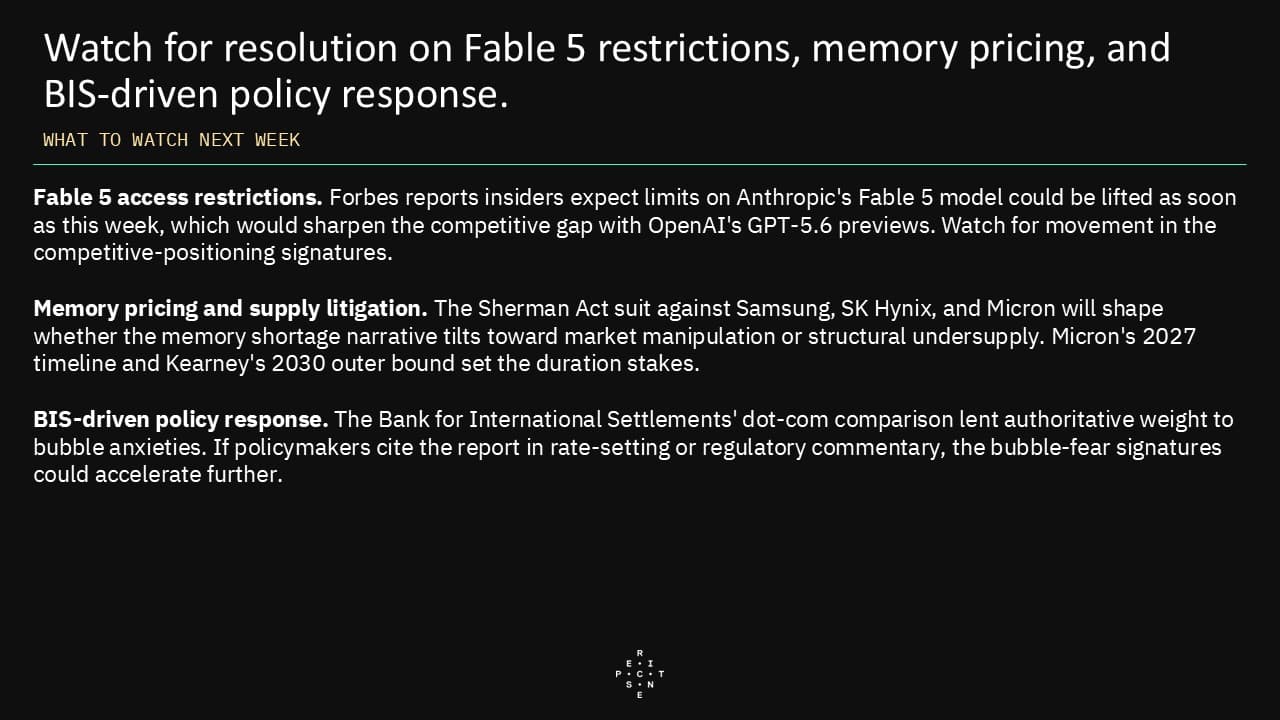
  • A leaked U.S. Treasury draft report comparing key aspects of the AI market to the dot-com bubble catalyzed a sharp intensification of systemic risk language across AI media coverage. Multiple related semantic signatures—bubble-crash predictions, dot-com analogies, and capital expenditure risk framing—all strengthened simultaneously in one of the most concentrated clustering events Perscient has recorded. The conversation about AI financial risk has migrated from sell-side commentary into the institutional apparatus of government, raising the likelihood that regulatory attention to AI-linked financial exposure will follow.
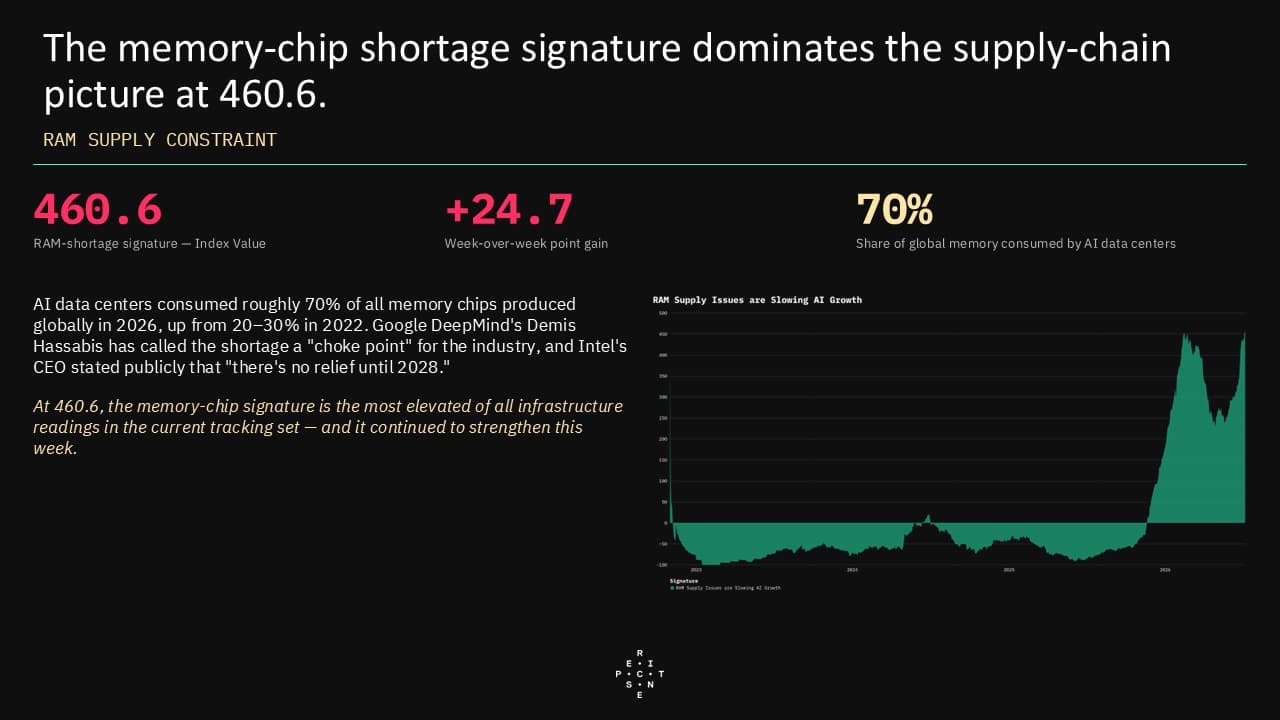
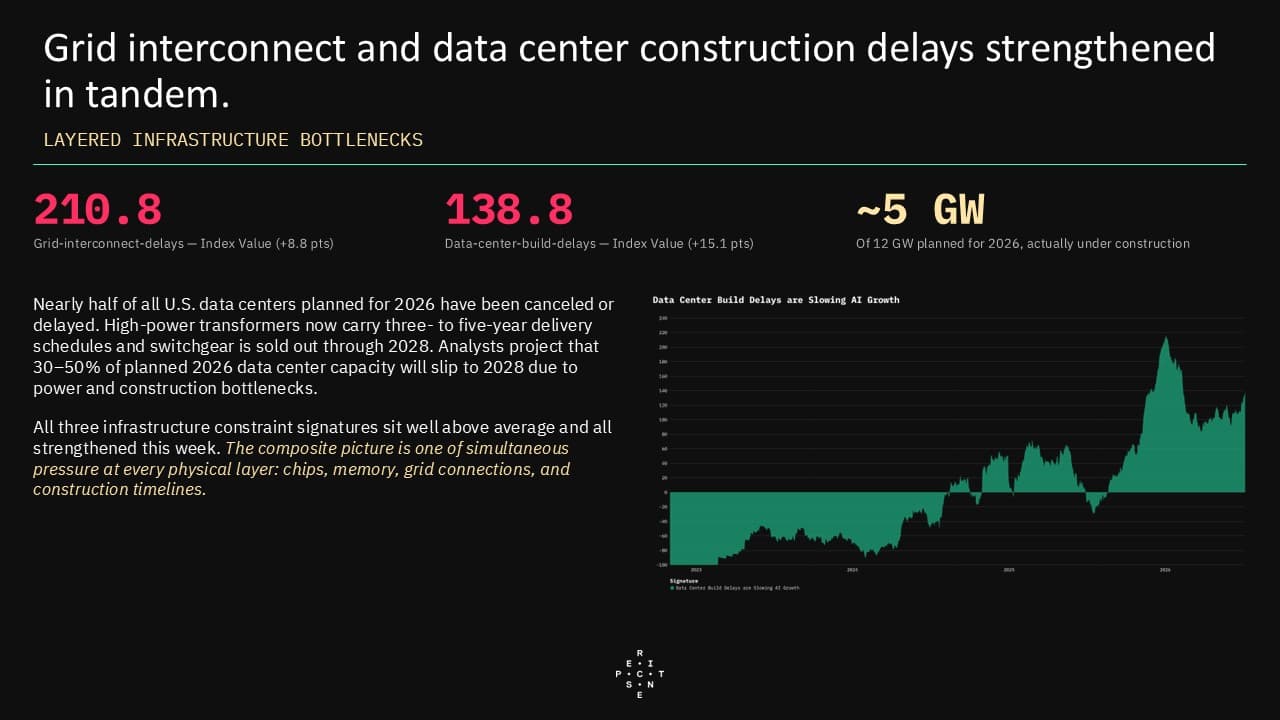
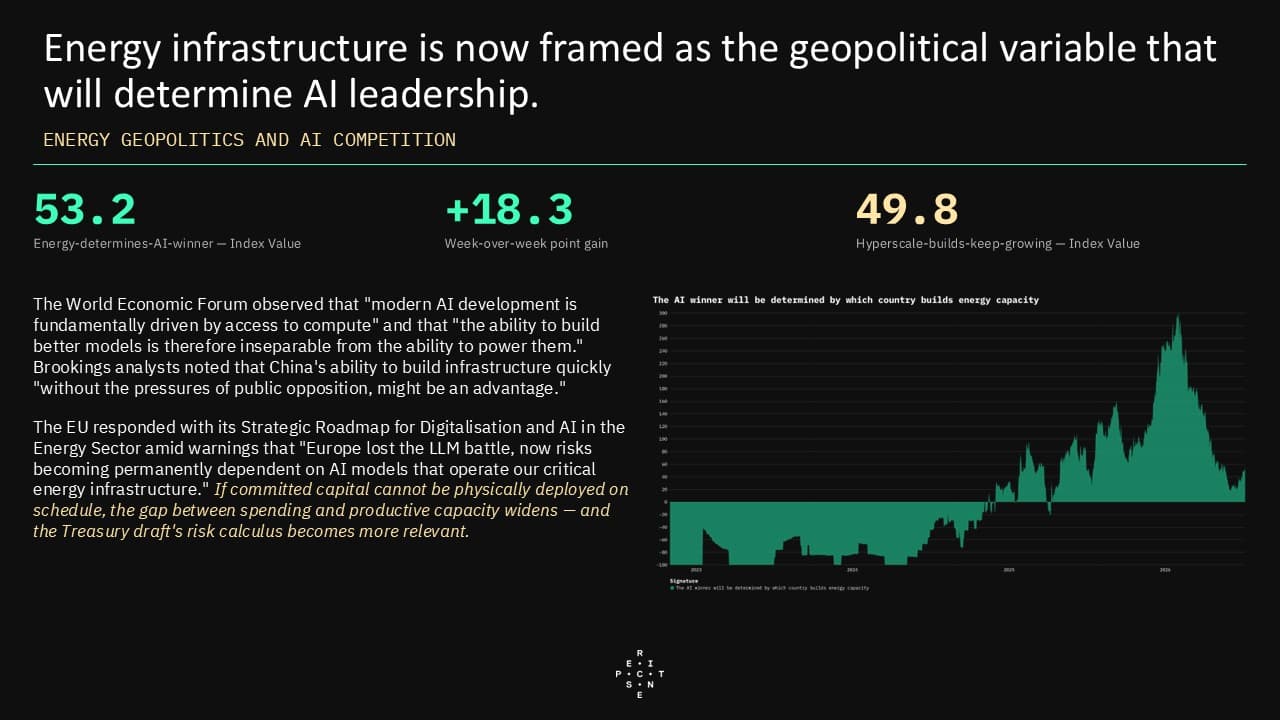
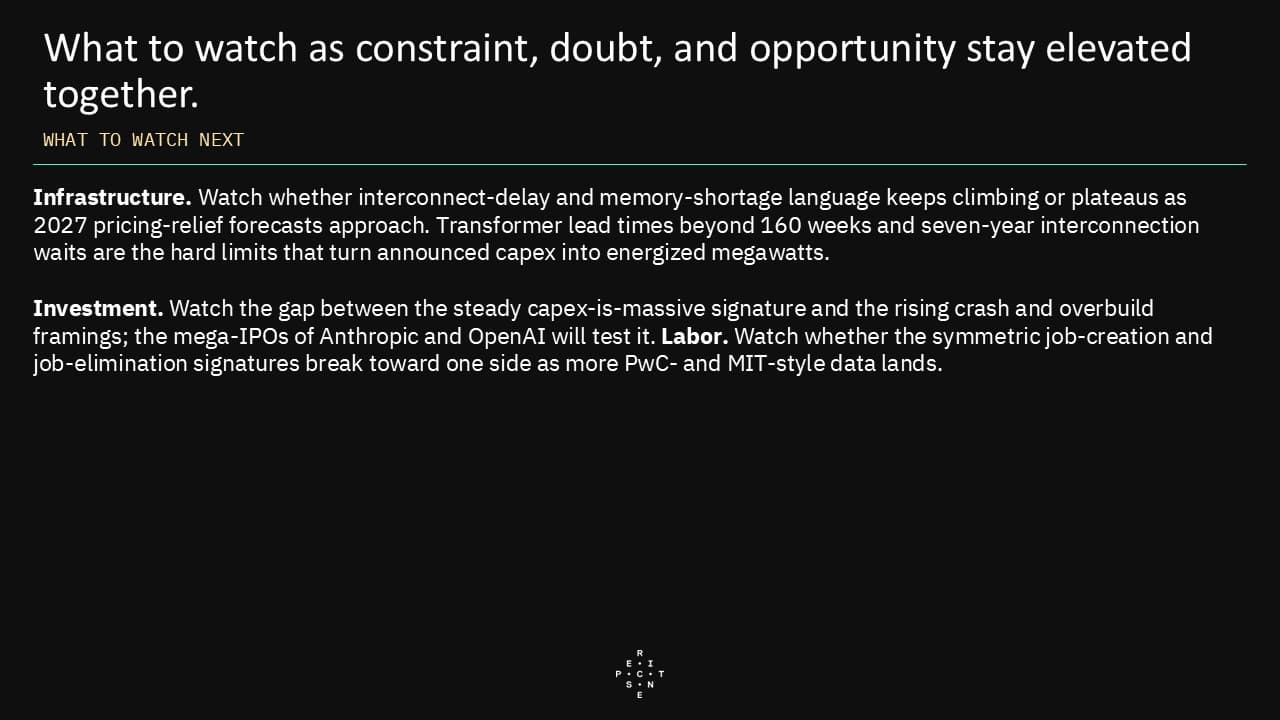
  • Physical infrastructure constraints have reached extreme intensity across every layer of the AI supply chain, compounding the financial risk narrative. The memory chip shortage signature sits at the highest value in the entire dataset, while grid interconnection delays and data center construction bottlenecks also strengthened. With nearly half of planned U.S. data centers for 2026 reportedly canceled or delayed and transformer lead times stretching to five years, the widening gap between committed capital and deliverable capacity feeds directly into both the bubble framing and an increasingly prominent geopolitical argument that energy infrastructure will determine AI leadership.
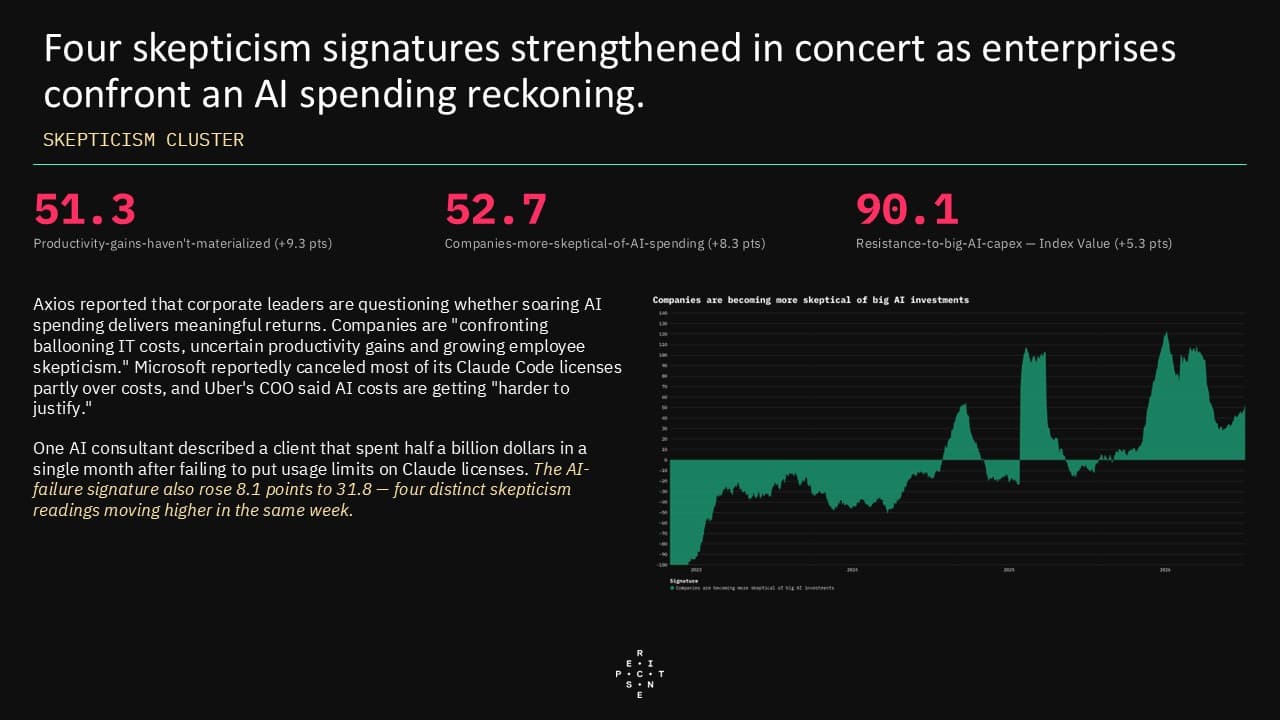
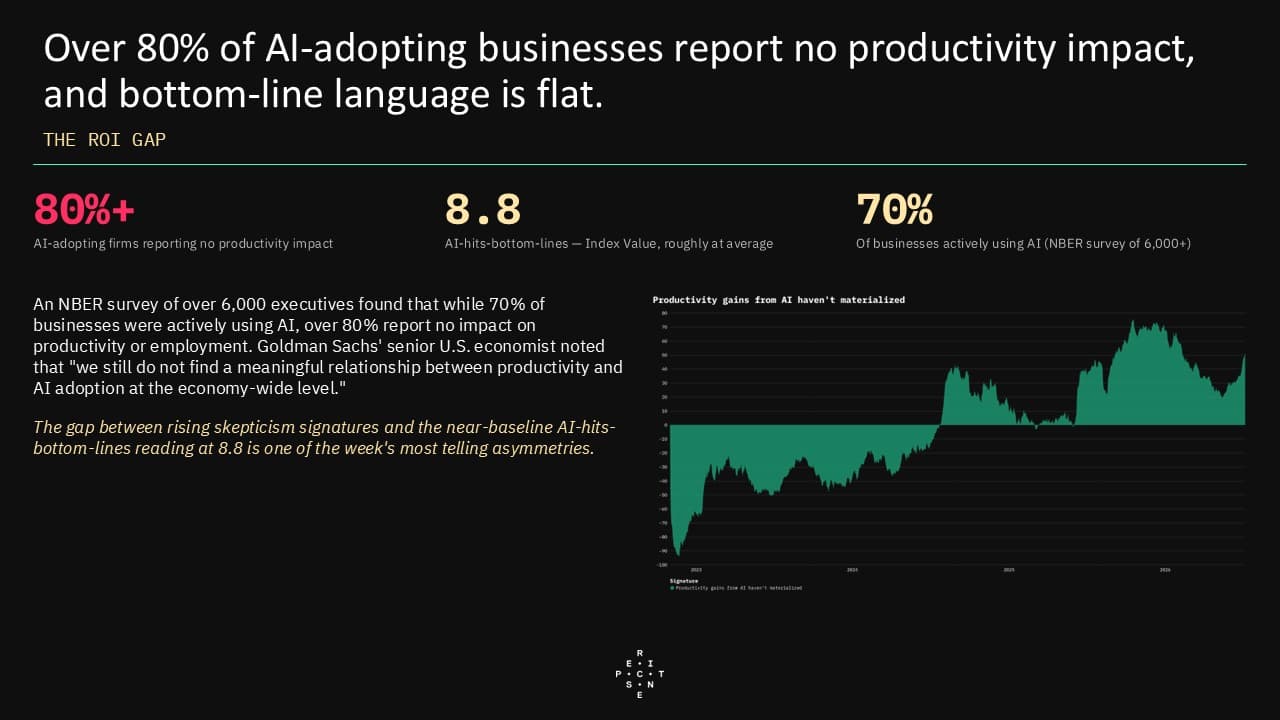
  • Corporate skepticism about AI spending returns sharpened markedly, even though language connecting AI to bottom-line profits remains near baseline—one of the week's most telling asymmetries. Four distinct skepticism-related signatures all moved higher in concert, reflecting media reports that enterprises are confronting what outlets have called an "AI spending reckoning." Survey data indicating that over 80% of AI-adopting businesses report no productivity impact, combined with reports that major firms are cutting AI tool licenses over cost concerns, has given the skepticism cluster a broadening empirical foundation.
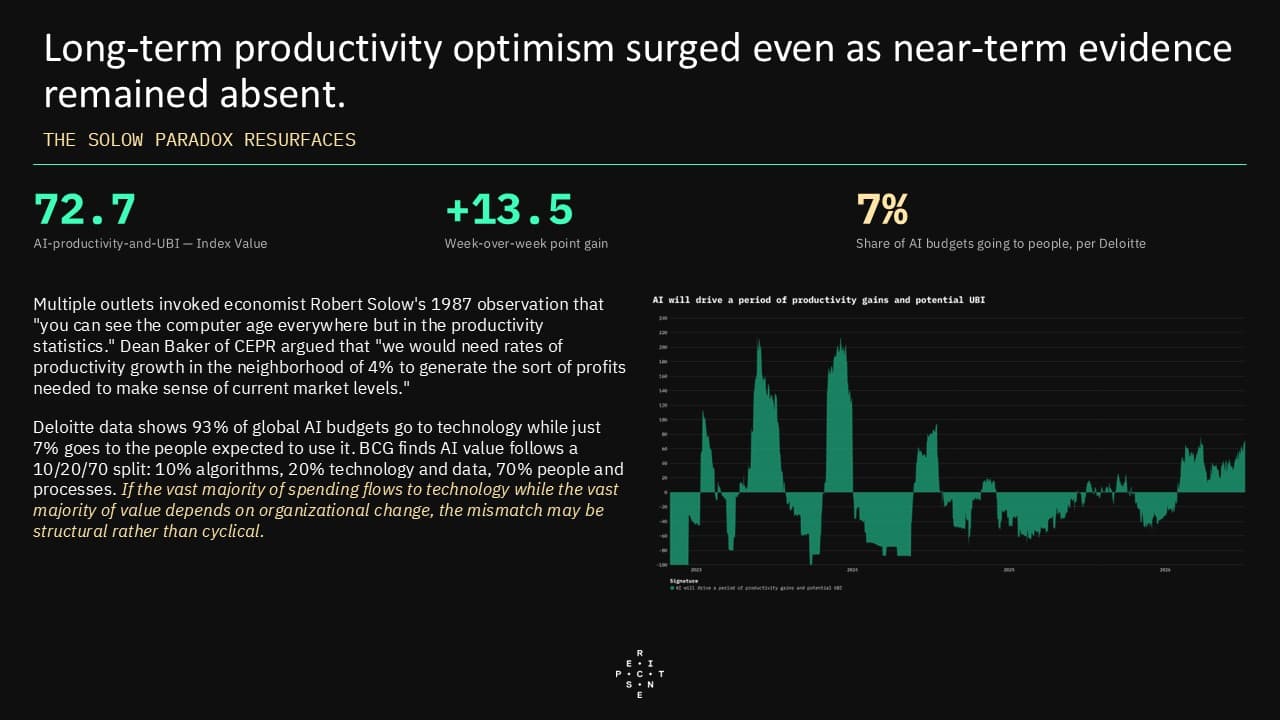
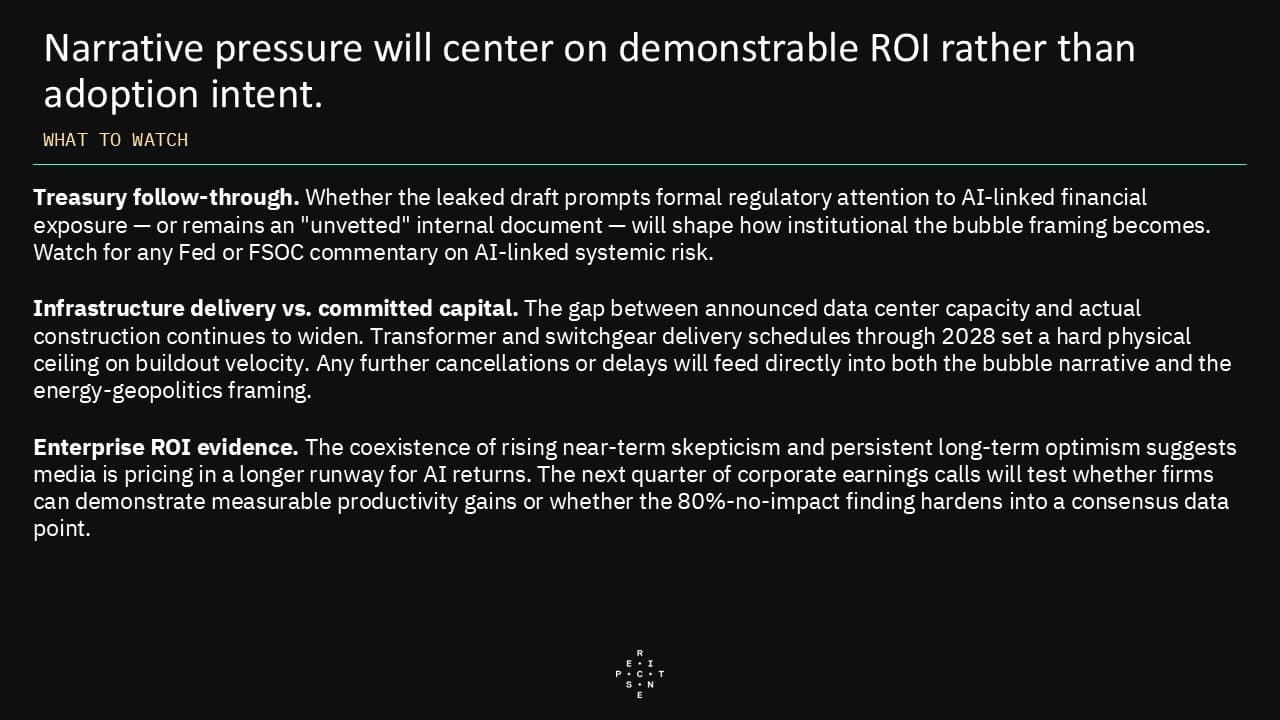
  • The media environment has not, however, reached consensus pessimism. Language asserting that the AI investment theme remains durable held steady above average, and discussion of AI's longer-term transformative productivity potential actually strengthened. The coexistence of rising near-term skepticism and persistent long-term optimism suggests that media is pricing in a longer runway for AI returns than many corporate budgets were designed to accommodate—a tension likely to keep pressure on firms to demonstrate measurable ROI rather than simply signal adoption intent.
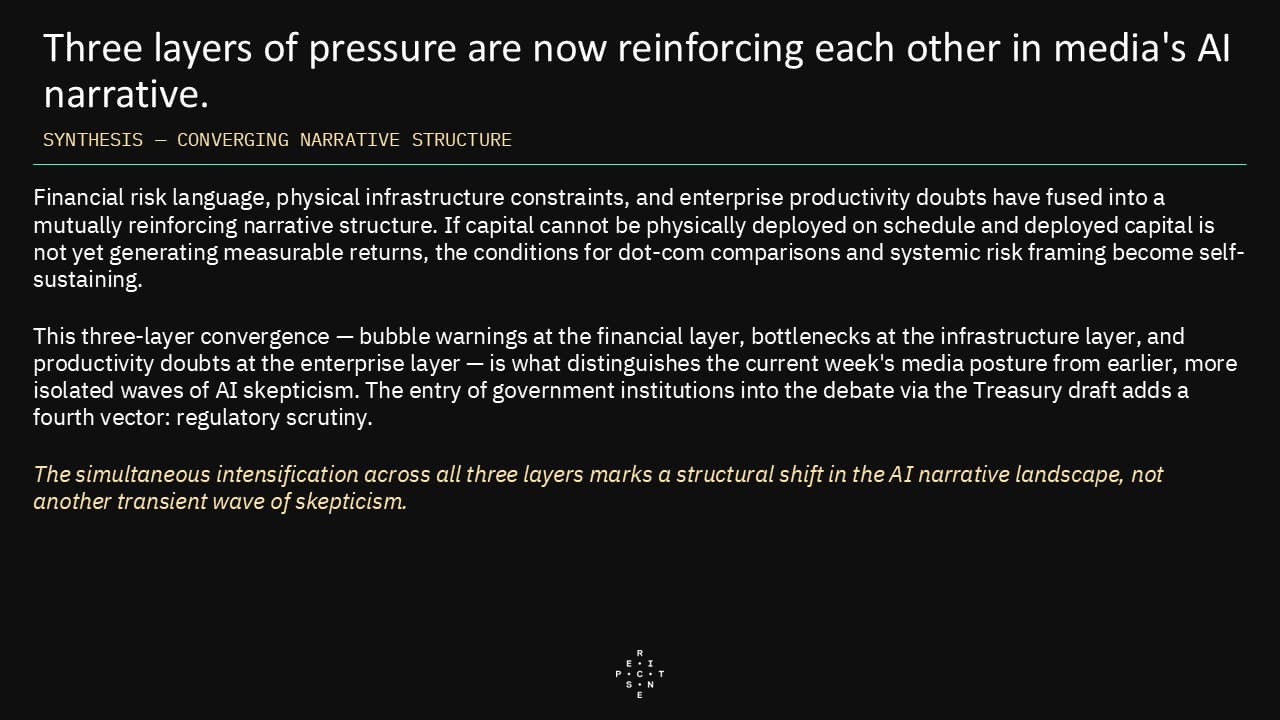
  • The simultaneous intensification of bubble warnings at the financial layer, physical bottlenecks at the infrastructure layer, and productivity doubts at the enterprise layer creates a mutually reinforcing narrative structure. If capital cannot be physically deployed on schedule and deployed capital is not yet generating measurable returns, the conditions for dot-com comparisons and systemic risk framing become self-sustaining. This three-layer convergence is what distinguishes the current week's media posture from earlier, more isolated waves of AI skepticism.

Recent Pulses

Markets PulseWeeklySep 22, 2026

Markets Pulse September 15, 2026

The regime-change story arrives without any accompanying fear language. Every flight-to-safety signature — Treasurys, Swiss franc, yen, gold, money market funds — sits deep in negative territory, geopolitical and monetary policy uncertainty signatures were flat, and risk-on and risk-off readings have converged to nearly the same level just below zero. Media are narrating a supply shock, a five-percent ten-year, and a first hike since 2023 while conspicuously declining to counsel defensive positioning. Election-season transfer proposals collided with a hardening sovereign-risk story, and media asserted both outcomes at once. The helicopter-money signature registered the largest single move in the file, and stimulus-check predictions rose with it, yet signatures tracking debt paydown, deficit reduction, and austerity legislation also strengthened in the same week, while fiscal policy uncertainty remained flat. Commentators are expressing conviction about incompatible fiscal futures rather than doubt. Simultaneously, signatures tying runaway spending to higher Treasury yields, and those linking bond weakness to deficits and unfunded tax cuts, all gained, and claims that Treasurys are pricing genuine default risk moved into positive territory. Taken together, Sections 1 and 2 describe a media framework in which monetary and fiscal policy are pulling in opposite directions. Coverage pairs a hawkish Fed responding to oil-driven inflation with a proposed trillion-dollar household giveaway, and the reserve-currency channel sharpened alongside it: the signature tying dollar-status threats specifically to debt sustainability rose while the generic version held flat. Claims that White House pressure on foreign Treasury holders is deterring buyers remain the densest reading in the entire file, even as it eased slightly, and official-sector gold substitution language stayed elevated without accelerating further. Tariff politics are running in reverse, and the war has been absorbed into the same affordability argument. The signature tracking broad public opposition to tariffs climbed to one of the highest standings in the file while claims of public support weakened further, and the stated rationale rotated decisively: reshoring-manufacturing arguments dropped hard while "make other countries pay their fair share" and negotiating-leverage framings gained. Directional language turned two-sided for the first time in months. Bridging Sections 1 and 3, voter coverage now treats tariffs and the conflict as a single price story, which the K-shaped-economy framing organizes into a midterm affordability fight — notably, the market version of that bifurcation narrative eased even as chip stocks sold off, and the argument that investors have no alternative to US large-cap growth has effectively vanished from coverage.

Markets PulseWeeklySep 22, 2026

Markets Pulse

Next release: September 29, 2026

Private Credit PulseBiweeklySep 22, 2026

Private Credit Pulse

Next release: October 06, 2026