Markets Pulse
WeeklyAugust 18, 2026

AI Pulse August 11, 2026

8.11AIPulse1.jpg
8.11AIPulse2.jpg
8.11AIPulse3.jpg
8.11AIPulse4.jpg
8.11AIPulse5.jpg
8.11AIPulse6.jpg
8.11AIPulse7.jpg
8.11AIPulse8.jpg
8.11AIPulse9.jpg
8.11AIPulse10.jpg
8.11AIPulse11.jpg
8.11AIPulse12.jpg
8.11AIPulse13.jpg
8.11AIPulse14.jpg
8.11AIPulse15.jpg
8.11AIPulse16.jpg
8.11AIPulse17.jpg
8.11AIPulse18.jpg

EXECUTIVE SUMMARY

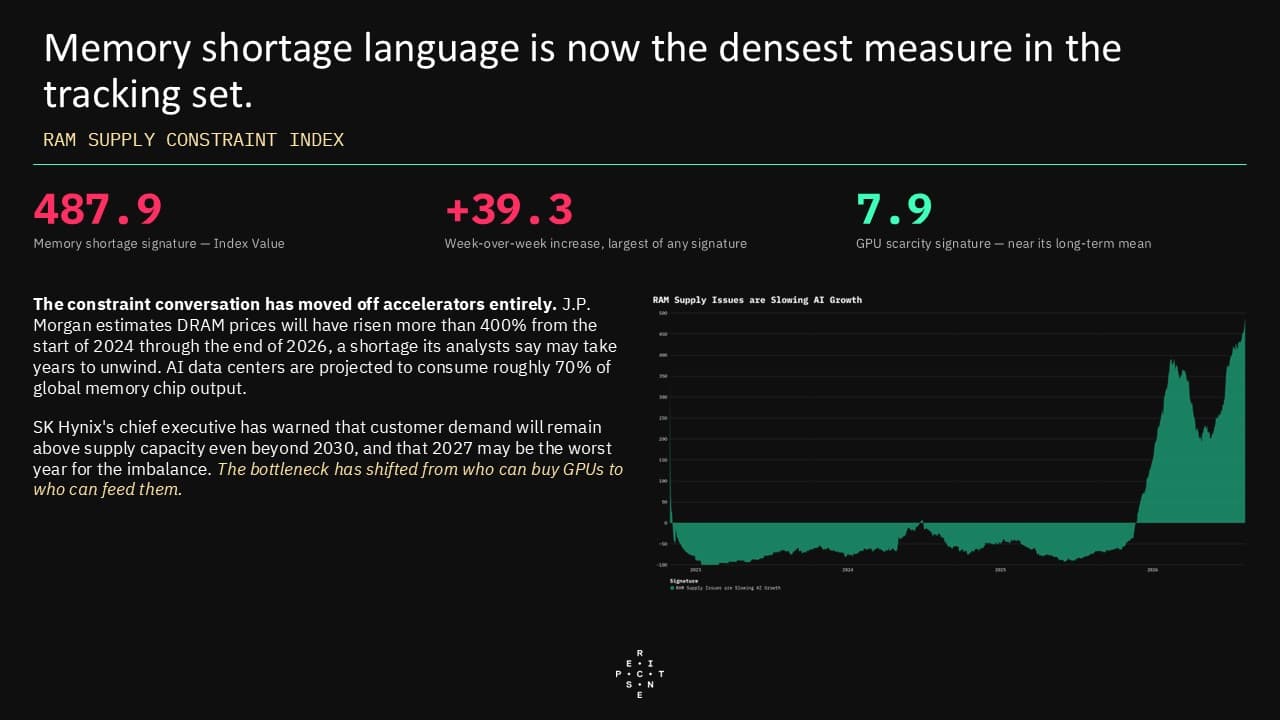
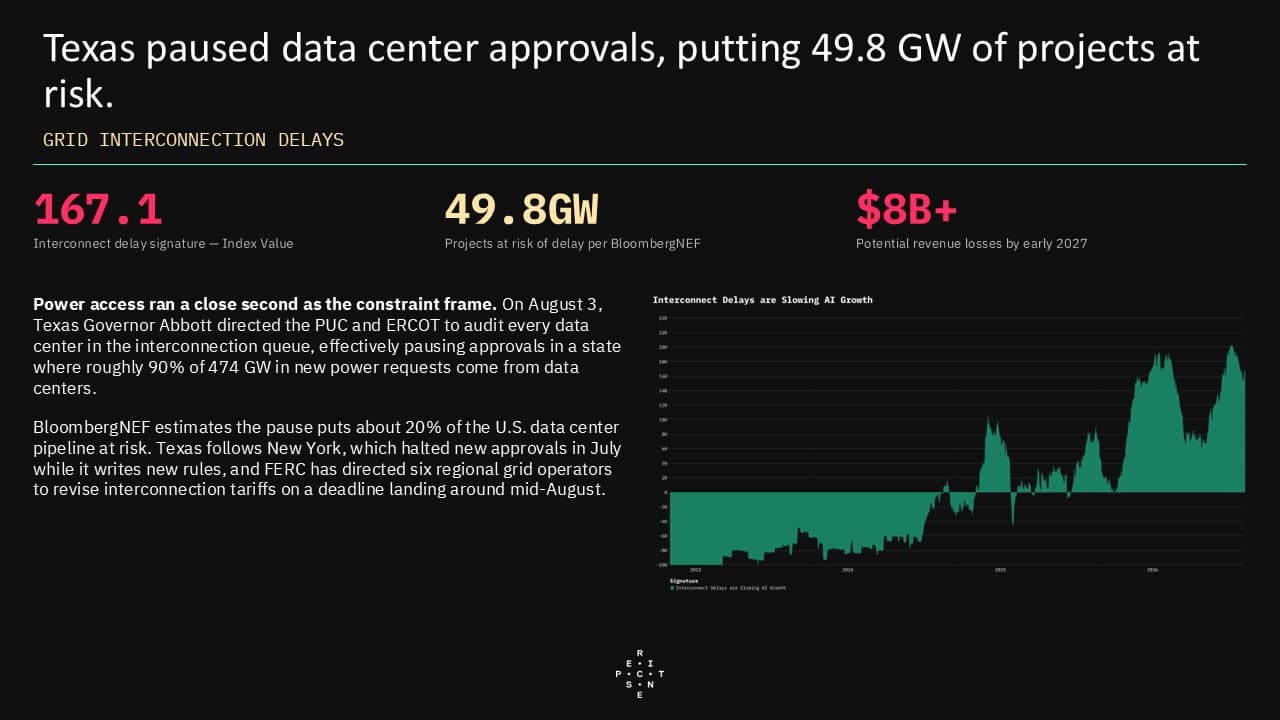
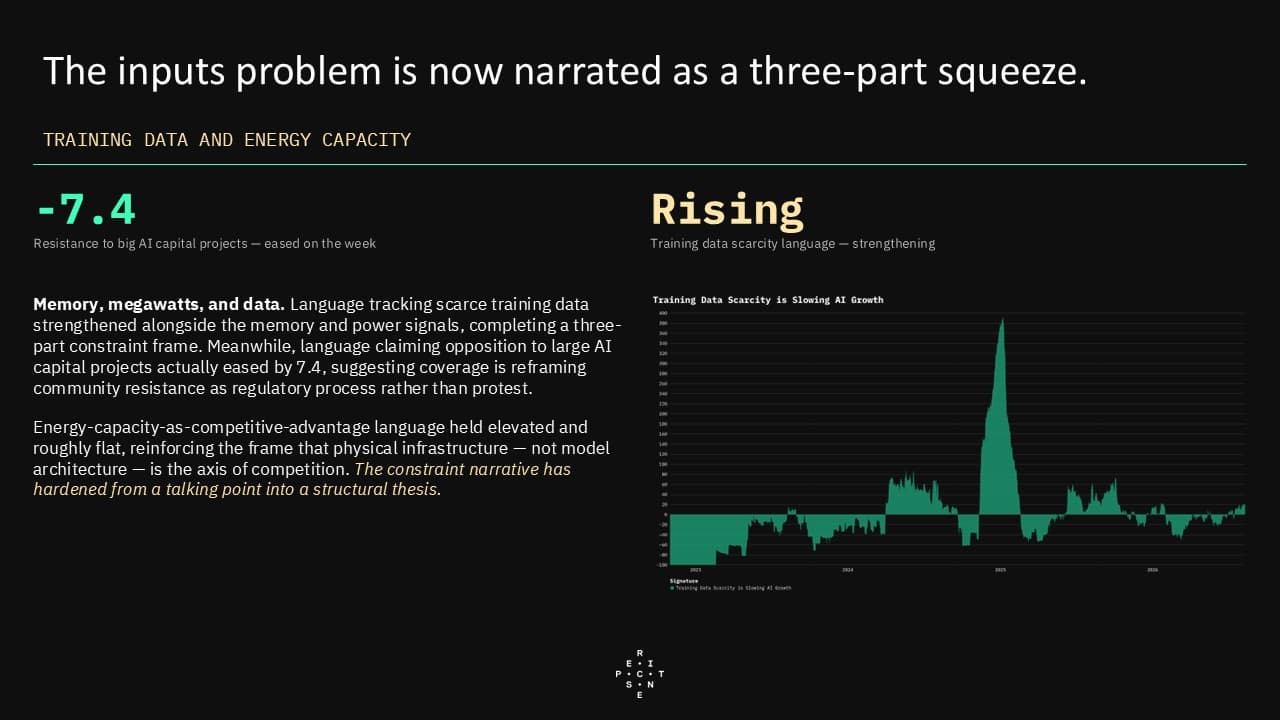
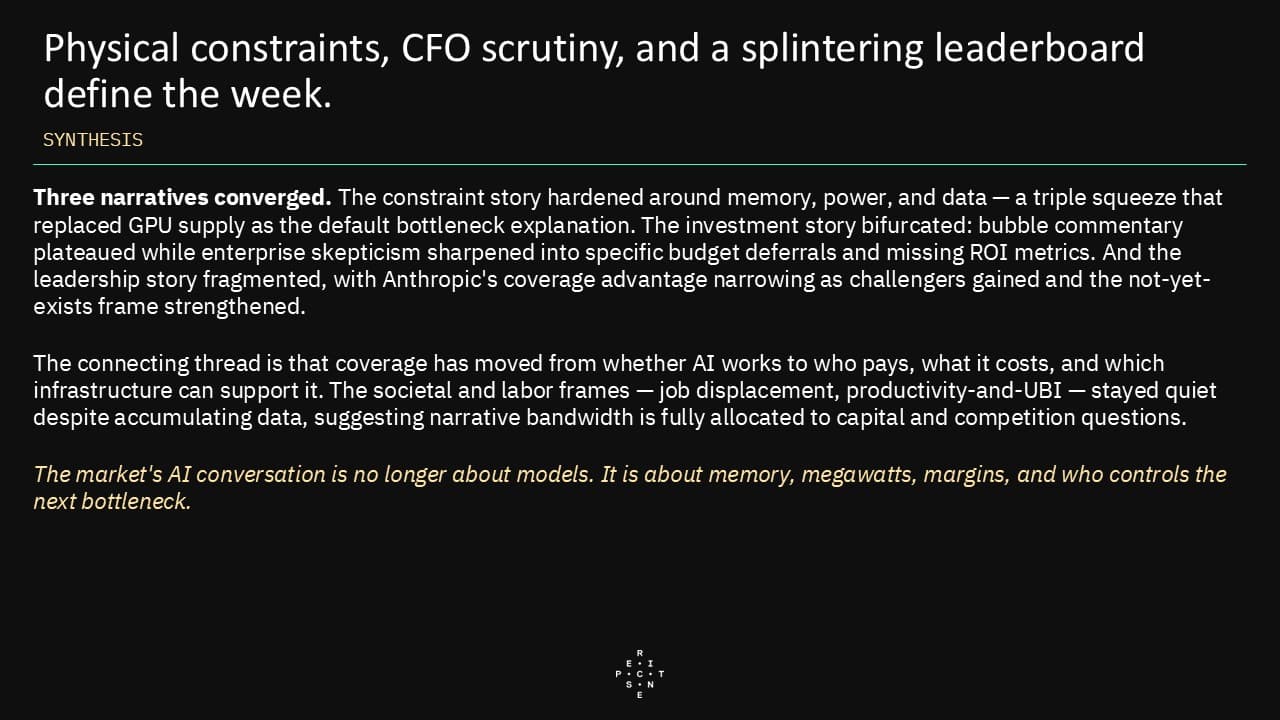
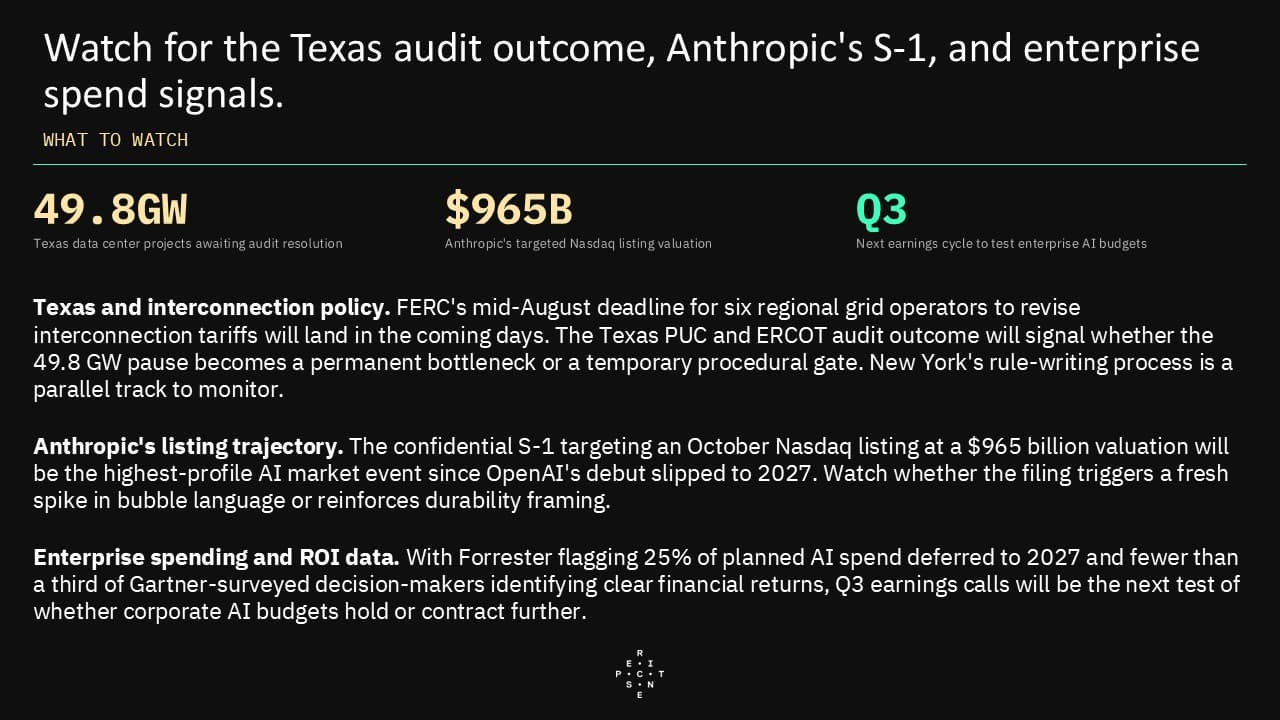
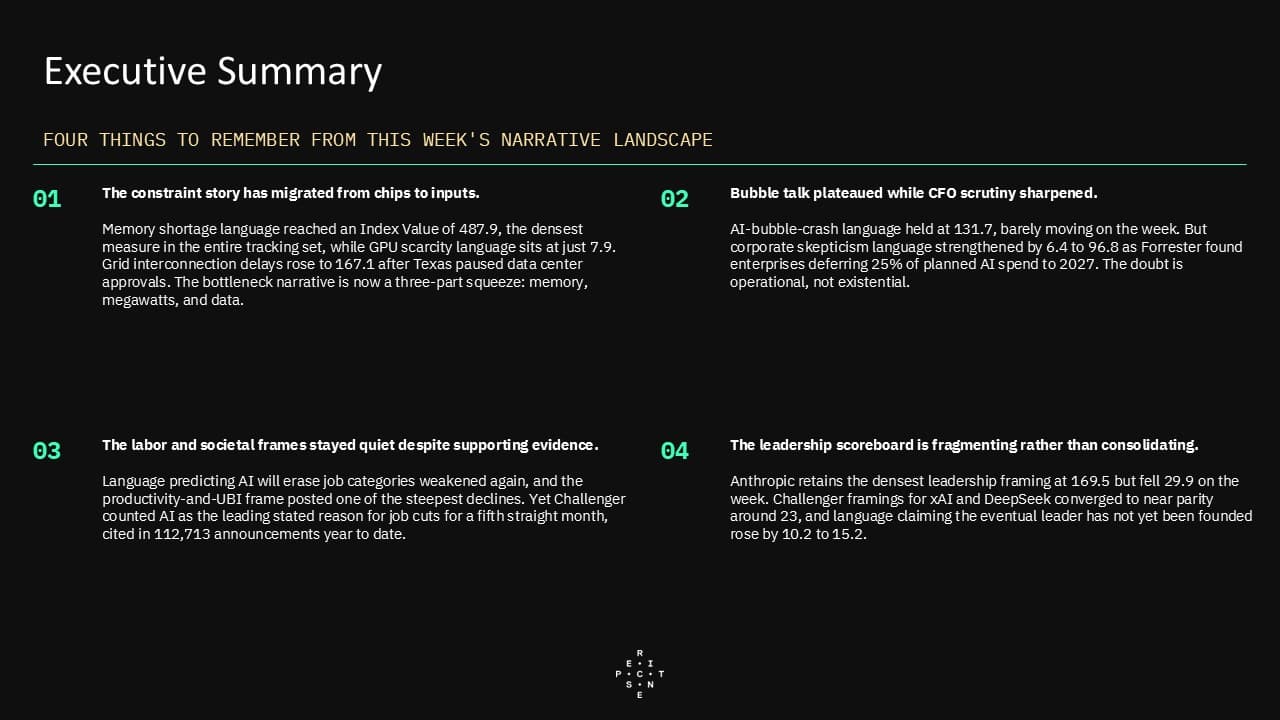
  • The constraint story has migrated from chips to inputs. Perscient's semantic signature tracking the density of language asserting that memory shortages are throttling AI growth is now the densest and fastest-rising measure in the set, while comparable language about GPU scarcity sits near its long-term mean. Coverage pairs this with grid interconnection delays and scarce training data, producing a three-part squeeze framing — memory, megawatts, and data — that has replaced accelerator supply as the default bottleneck explanation.
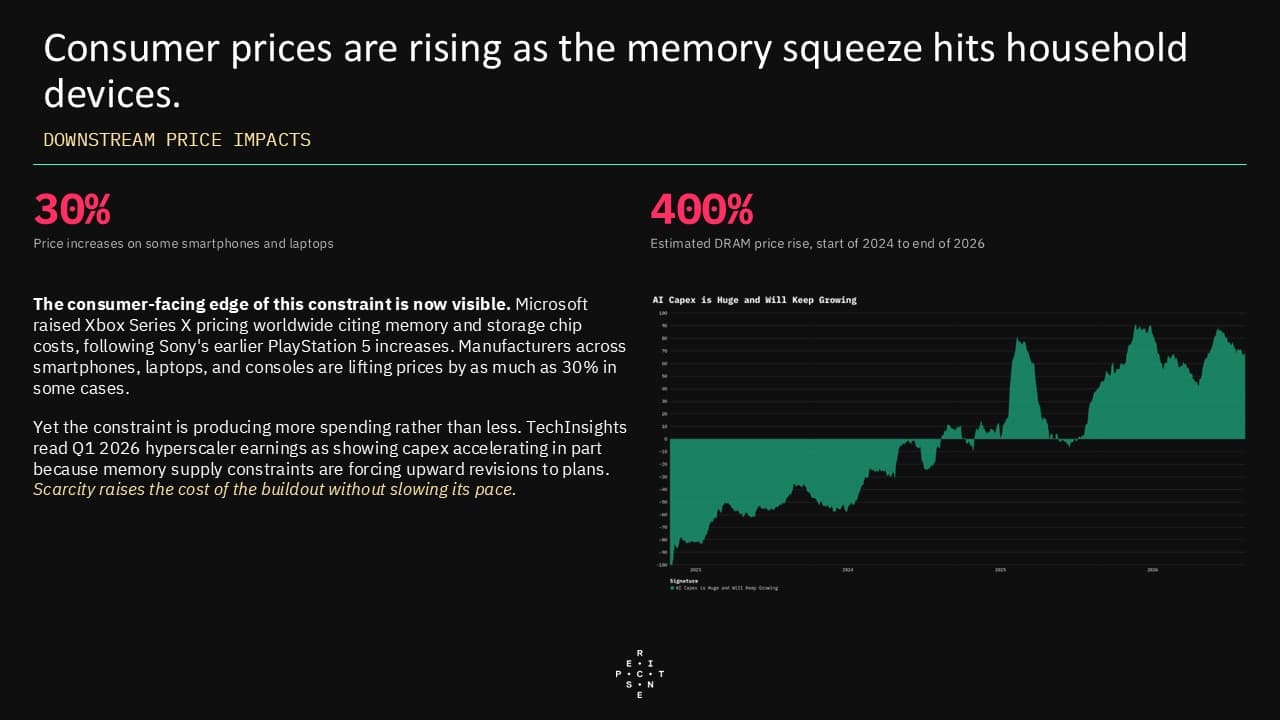
  • Physical constraints are being narrated as accelerants rather than brakes on spending. Reporting links memory scarcity to consumer price increases on consoles and laptops and to state-level pauses on data center approvals in Texas and New York, yet the same coverage cycle carries upward revisions to hyperscaler capex and trillion-dollar backlog figures. The implicit claim is that scarcity raises the cost of the buildout without slowing its pace.
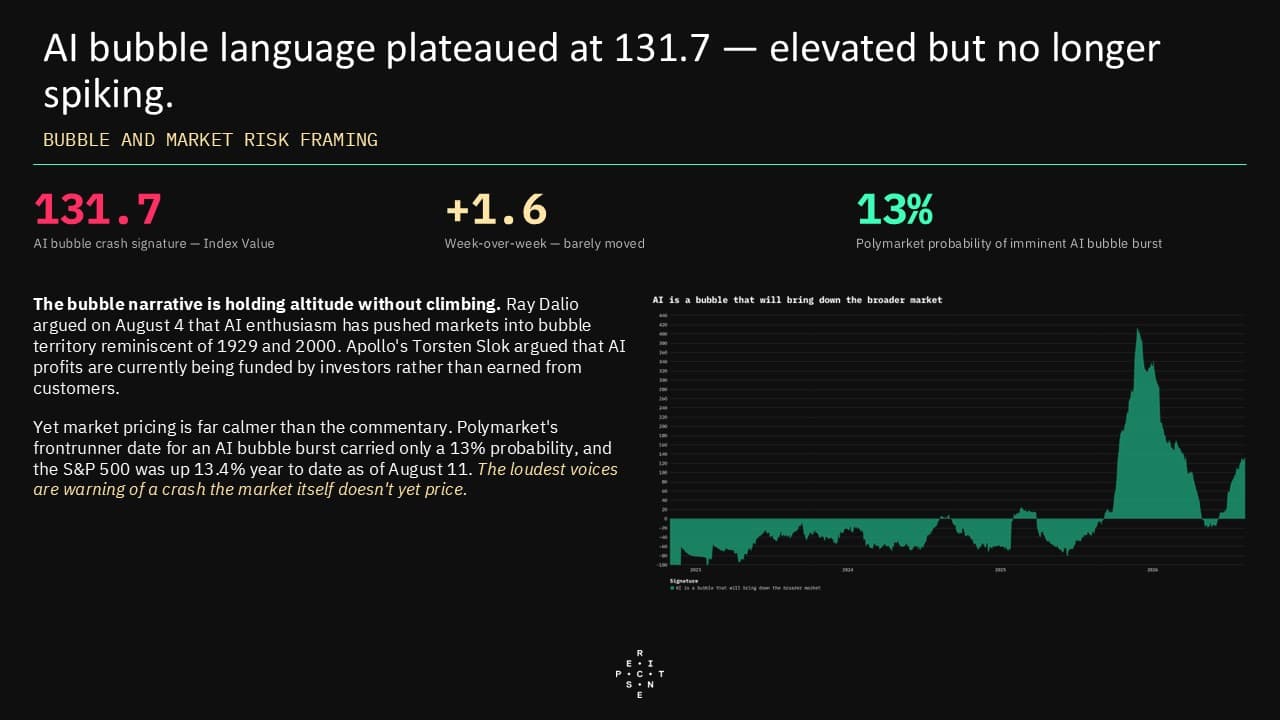
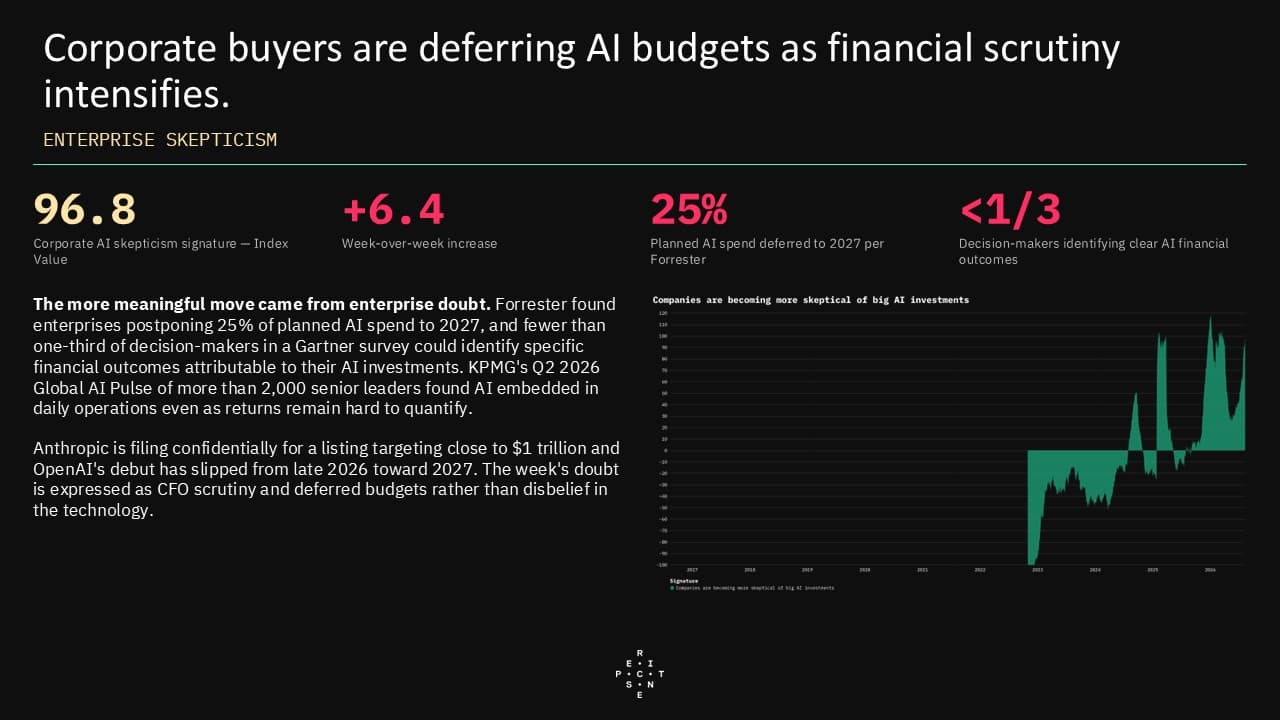
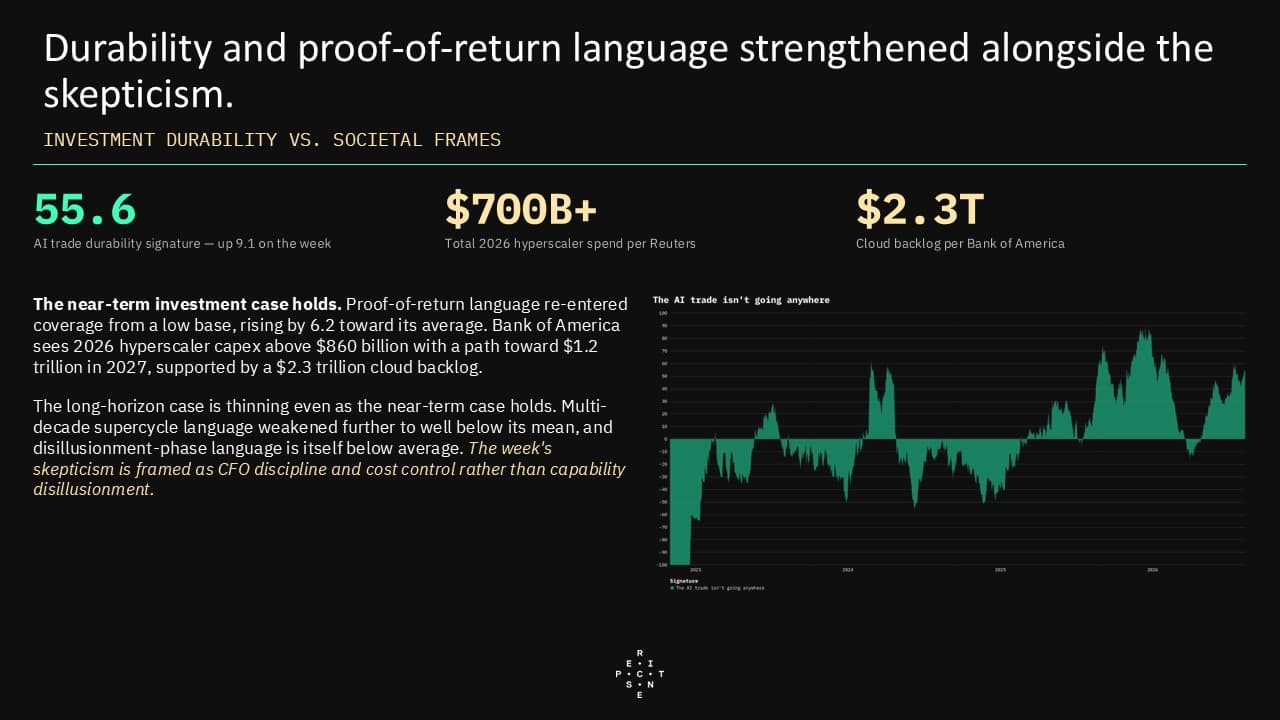
  • Bubble commentary has plateaued while a more granular skepticism gains ground. Language predicting an AI-driven market collapse stayed elevated but barely moved, whereas language describing corporate buyers as doubtful of large AI outlays strengthened, alongside a simultaneous rise in durability and proof-of-return framing. The week's doubt is being expressed as CFO scrutiny and deferred budgets rather than disbelief in the technology, and prediction markets and index performance remain considerably calmer than the loudest commentary.
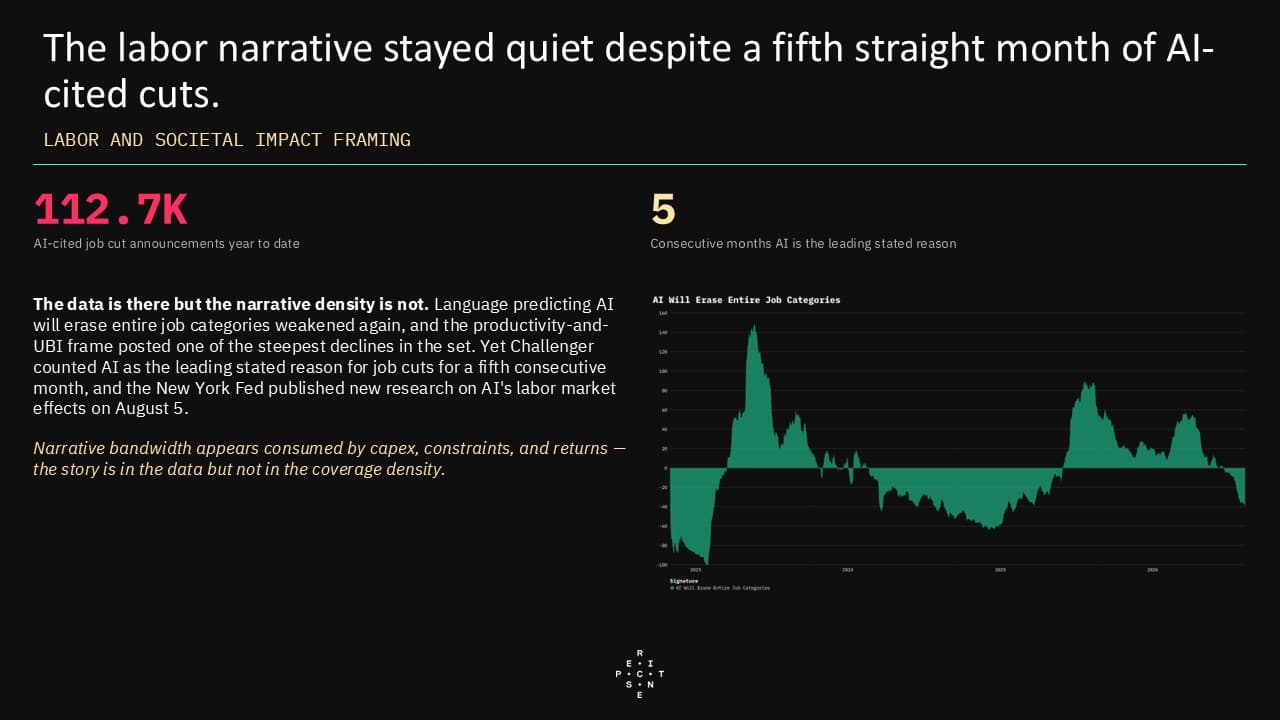
  • The labor and societal frames stayed quiet despite supporting evidence. Language predicting the elimination of whole job categories weakened again, and the productivity-and-UBI framing posted one of the steepest declines, even though layoff trackers cite AI as the leading stated reason for cuts for a fifth straight month and new central bank research landed during the week. Narrative bandwidth appears to be consumed by capital expenditure, supply constraints, and return-on-investment questions.
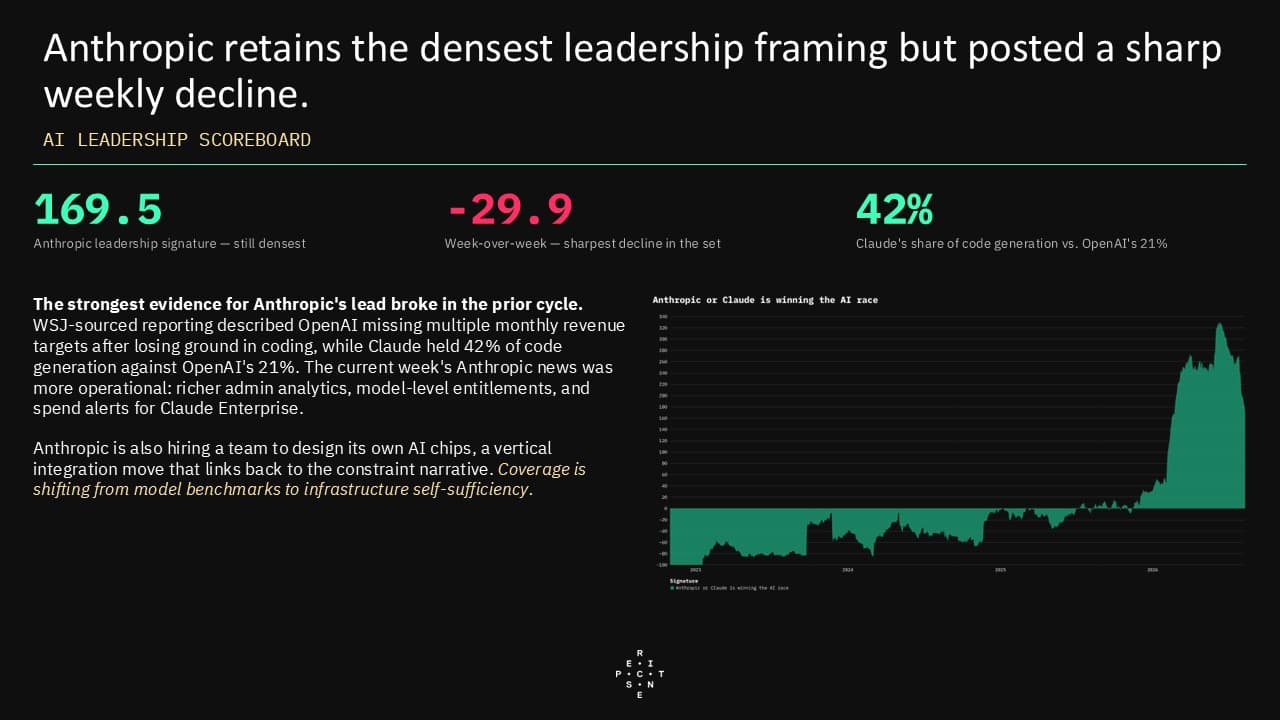
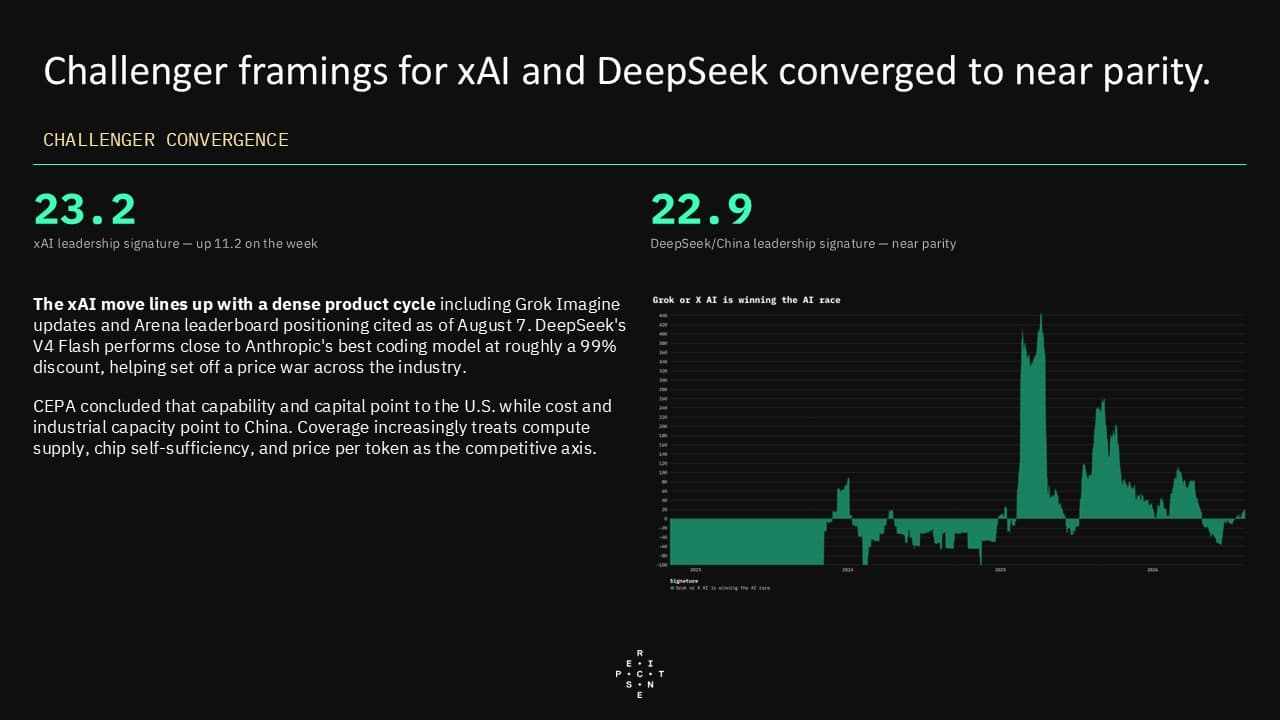
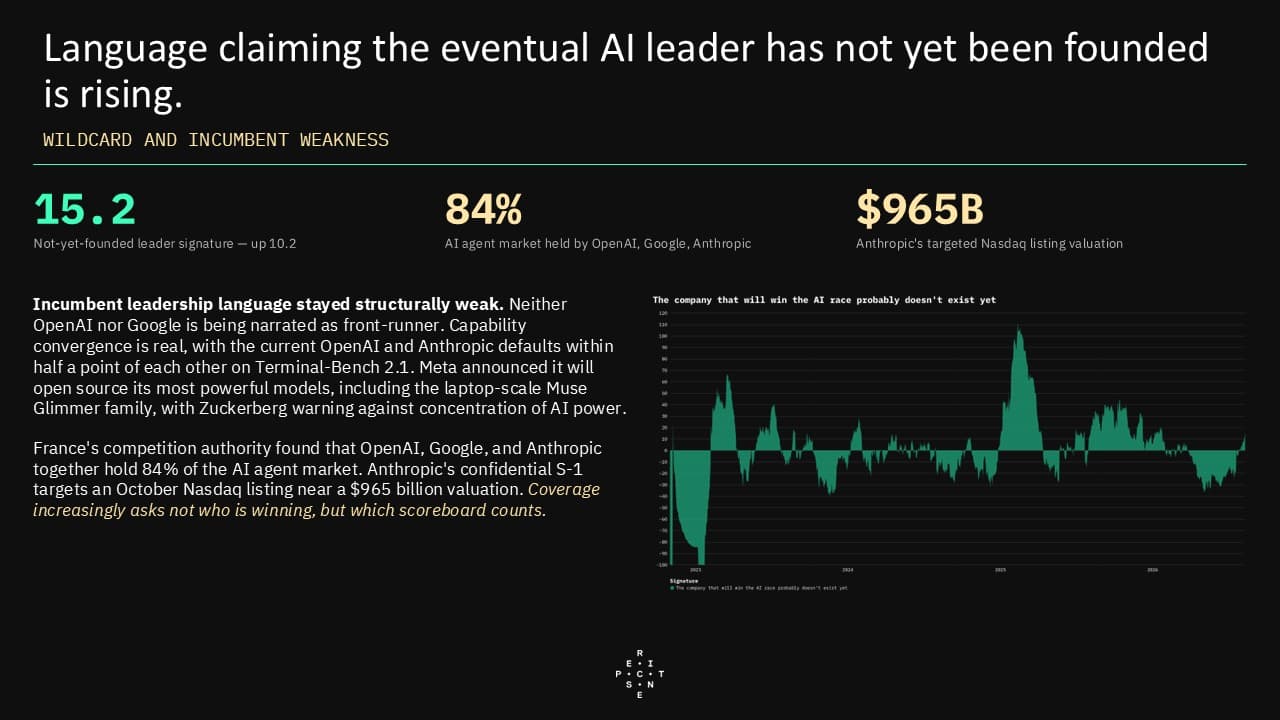
  • The leadership scoreboard is fragmenting rather than consolidating. Anthropic retains the densest leadership framing but recorded the sharpest weekly decline in the set, while challenger framings for xAI and for DeepSeek and China converged to near parity and language claiming the eventual leader has not yet been founded rose. Read together with the constraint and capital sections, coverage increasingly treats compute supply, chip self-sufficiency, and price per token as the competitive axis, shifting the question from who leads to which scoreboard counts.

Recent Pulses

Markets PulseWeeklySep 29, 2026

Markets Pulse

Next release: October 06, 2026

AI PulseWeeklySep 29, 2026

AI Pulse

Next release: October 06, 2026
Markets PulseWeeklySep 22, 2026

Markets Pulse September 15, 2026

The regime-change story arrives without any accompanying fear language. Every flight-to-safety signature — Treasurys, Swiss franc, yen, gold, money market funds — sits deep in negative territory, geopolitical and monetary policy uncertainty signatures were flat, and risk-on and risk-off readings have converged to nearly the same level just below zero. Media are narrating a supply shock, a five-percent ten-year, and a first hike since 2023 while conspicuously declining to counsel defensive positioning. Election-season transfer proposals collided with a hardening sovereign-risk story, and media asserted both outcomes at once. The helicopter-money signature registered the largest single move in the file, and stimulus-check predictions rose with it, yet signatures tracking debt paydown, deficit reduction, and austerity legislation also strengthened in the same week, while fiscal policy uncertainty remained flat. Commentators are expressing conviction about incompatible fiscal futures rather than doubt. Simultaneously, signatures tying runaway spending to higher Treasury yields, and those linking bond weakness to deficits and unfunded tax cuts, all gained, and claims that Treasurys are pricing genuine default risk moved into positive territory. Taken together, Sections 1 and 2 describe a media framework in which monetary and fiscal policy are pulling in opposite directions. Coverage pairs a hawkish Fed responding to oil-driven inflation with a proposed trillion-dollar household giveaway, and the reserve-currency channel sharpened alongside it: the signature tying dollar-status threats specifically to debt sustainability rose while the generic version held flat. Claims that White House pressure on foreign Treasury holders is deterring buyers remain the densest reading in the entire file, even as it eased slightly, and official-sector gold substitution language stayed elevated without accelerating further. Tariff politics are running in reverse, and the war has been absorbed into the same affordability argument. The signature tracking broad public opposition to tariffs climbed to one of the highest standings in the file while claims of public support weakened further, and the stated rationale rotated decisively: reshoring-manufacturing arguments dropped hard while "make other countries pay their fair share" and negotiating-leverage framings gained. Directional language turned two-sided for the first time in months. Bridging Sections 1 and 3, voter coverage now treats tariffs and the conflict as a single price story, which the K-shaped-economy framing organizes into a midterm affordability fight — notably, the market version of that bifurcation narrative eased even as chip stocks sold off, and the argument that investors have no alternative to US large-cap growth has effectively vanished from coverage.