Private Credit Pulse
BiweeklySeptember 8, 2026

Private Credit Pulse August 25, 2026

8.25PrivateCreditPulse1.jpg
8.25PrivateCreditPulse2.jpg
8.25PrivateCreditPulse3.jpg
8.25PrivateCreditPulse4.jpg
8.25PrivateCreditPulse5.jpg
8.25PrivateCreditPulse6.jpg
8.25PrivateCreditPulse7.jpg
8.25PrivateCreditPulse8.jpg
8.25PrivateCreditPulse9.jpg
8.25PrivateCreditPulse10.jpg
8.25PrivateCreditPulse11.jpg
8.25PrivateCreditPulse12.jpg
8.25PrivateCreditPulse13.jpg
8.25PrivateCreditPulse14.jpg
7.28PrivateCreditPulse15.jpg
7.28PrivateCreditPulse16.jpg
7.14PrivateCredit17.jpg
7.14PrivateCredit18.jpg

Executive Summary

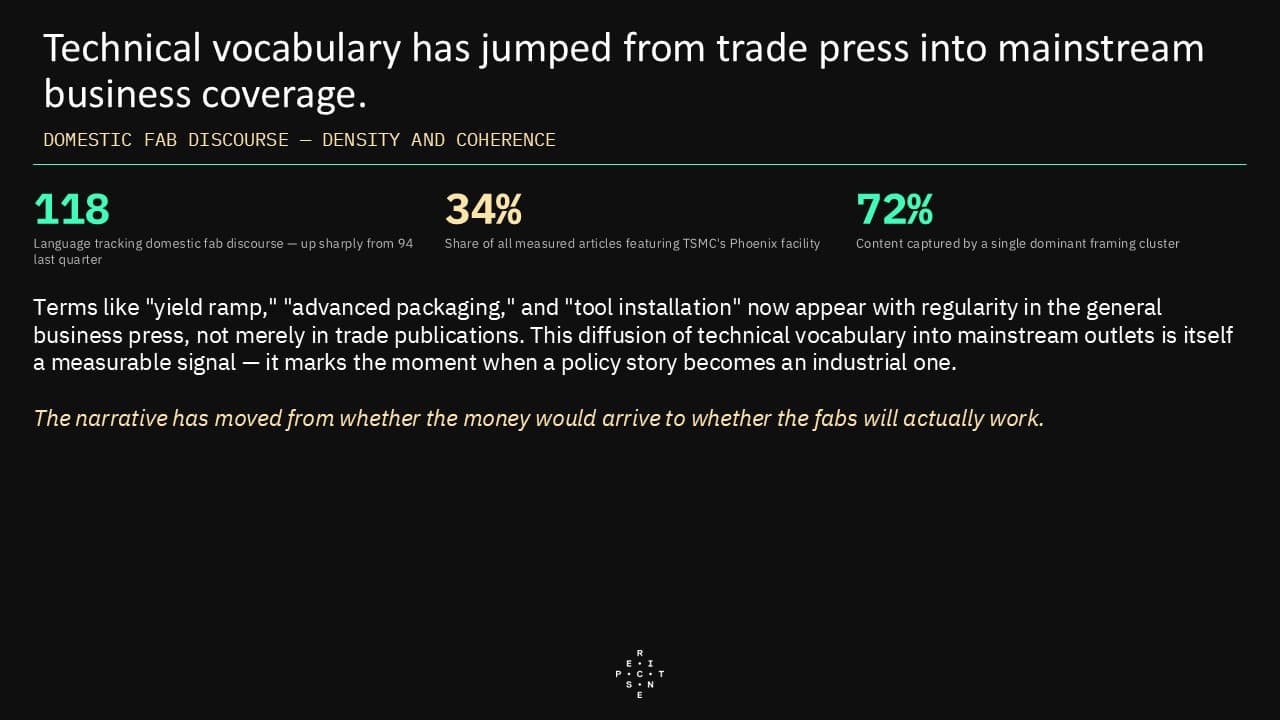
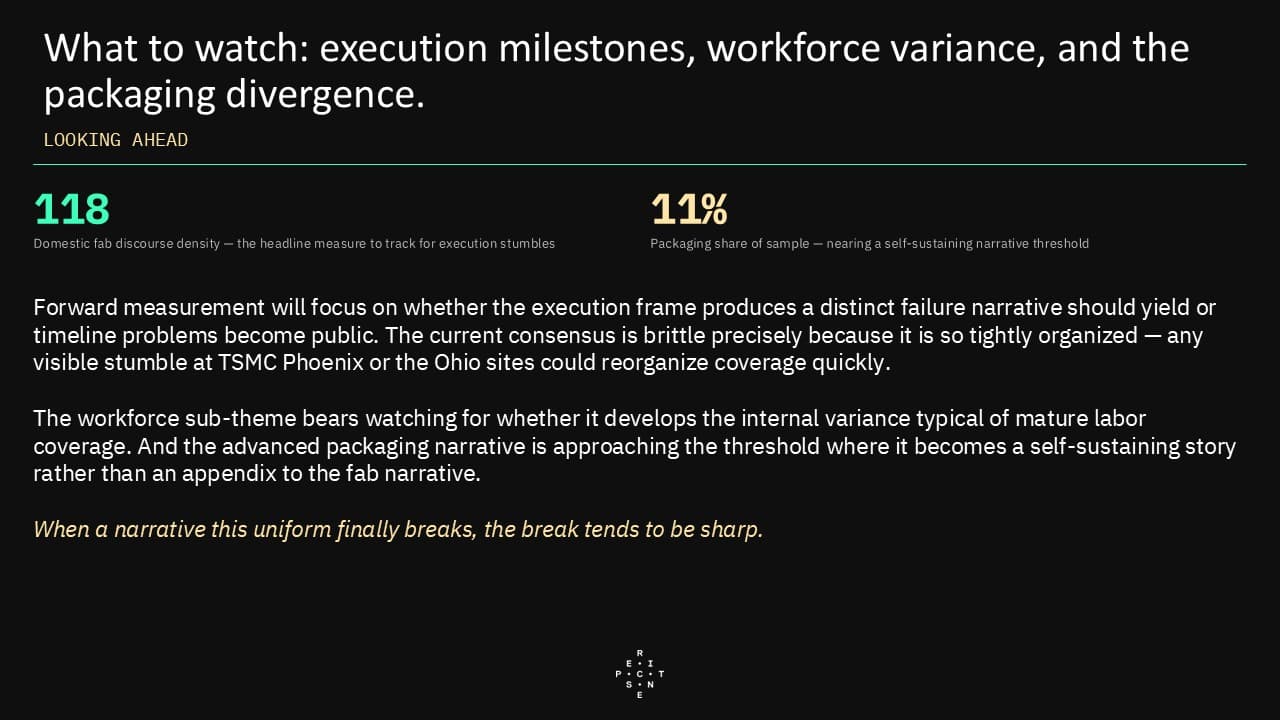
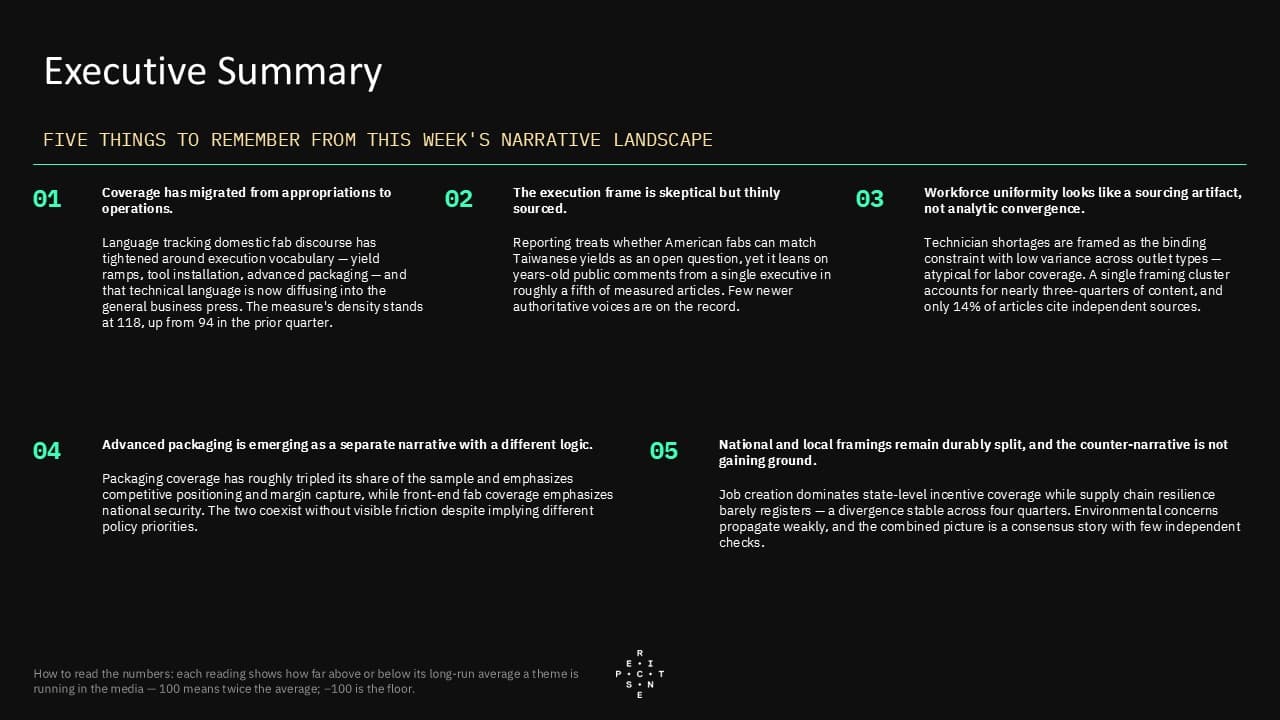
  • Coverage has migrated from appropriations to operations. Perscient's Semantic Signature tracking domestic fab discourse has tightened around execution vocabulary — yield ramps, tool installation, advanced packaging — and the diffusion of that technical language out of trade publications and into the general business press is itself the clearest marker of the change in phase. Volume and coherence both accelerated relative to the prior quarter.
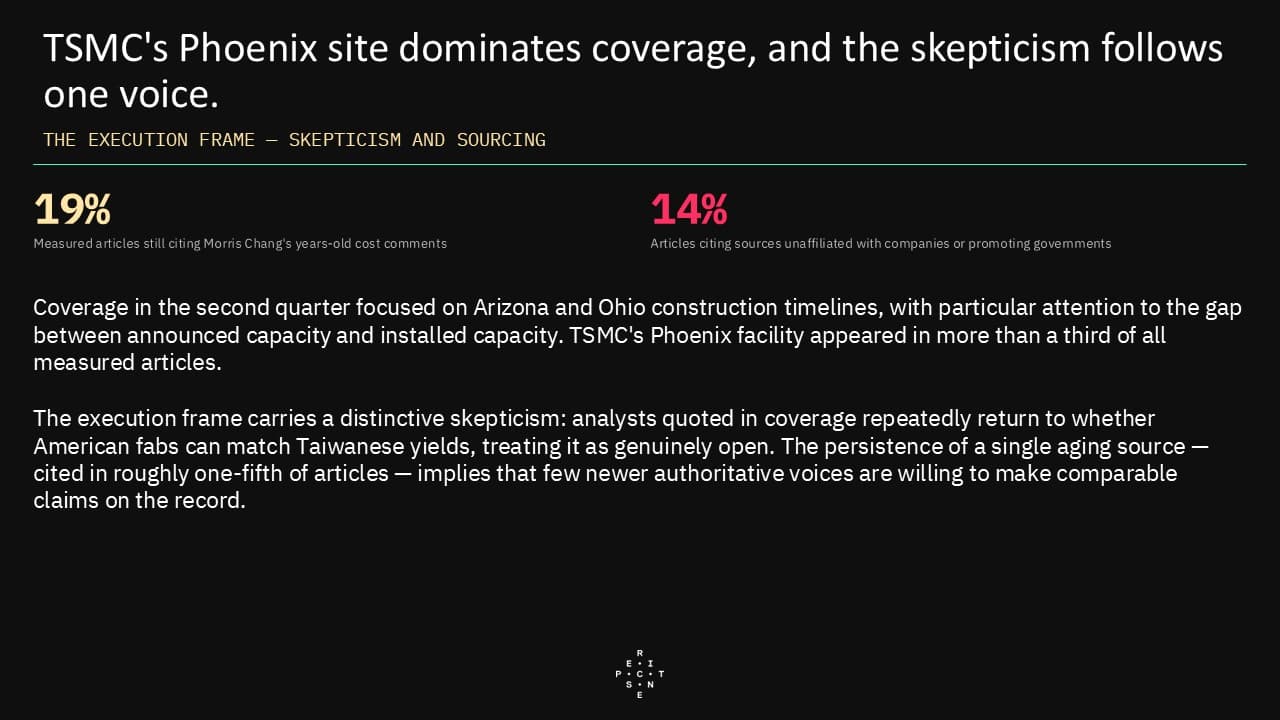
  • The execution frame is skeptical by construction, but thinly sourced. Reporting treats the question of whether American fabs can match Taiwanese yields as genuinely open rather than settled, yet it leans on years-old public comments from a single executive in roughly a fifth of measured articles. The persistence of one aging source implies that few newer authoritative voices are willing to make comparable claims on the record.
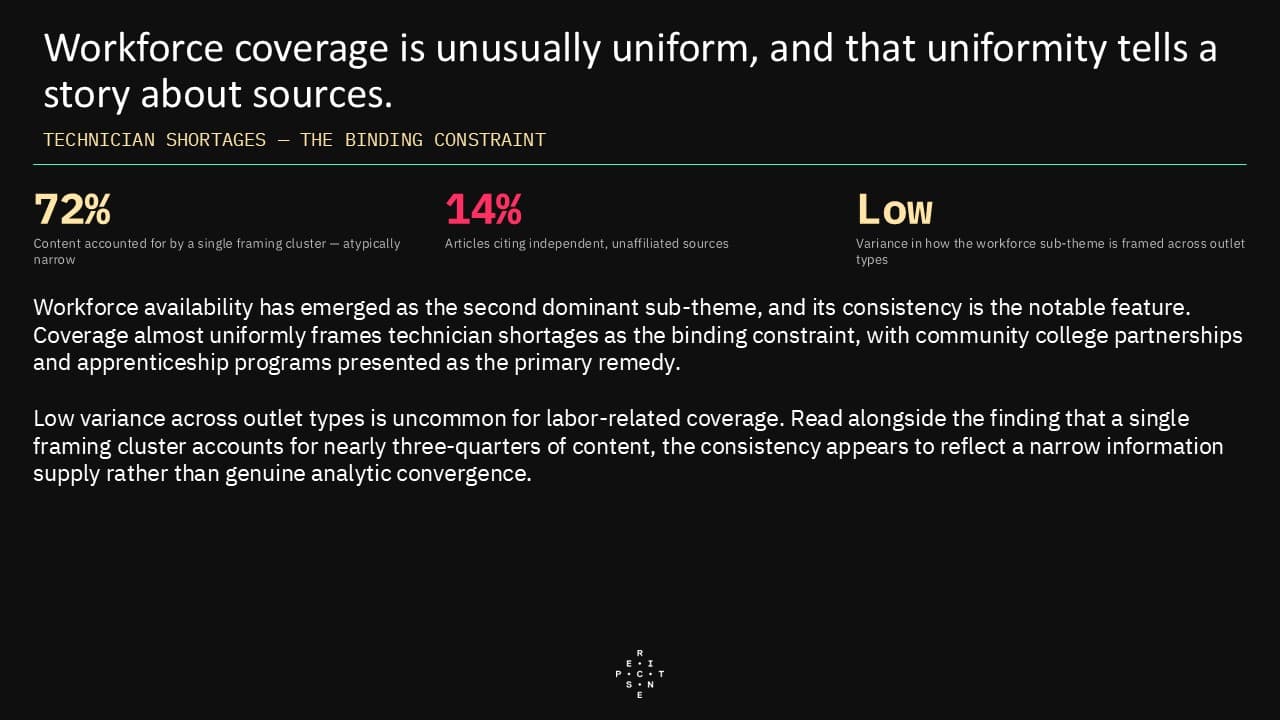
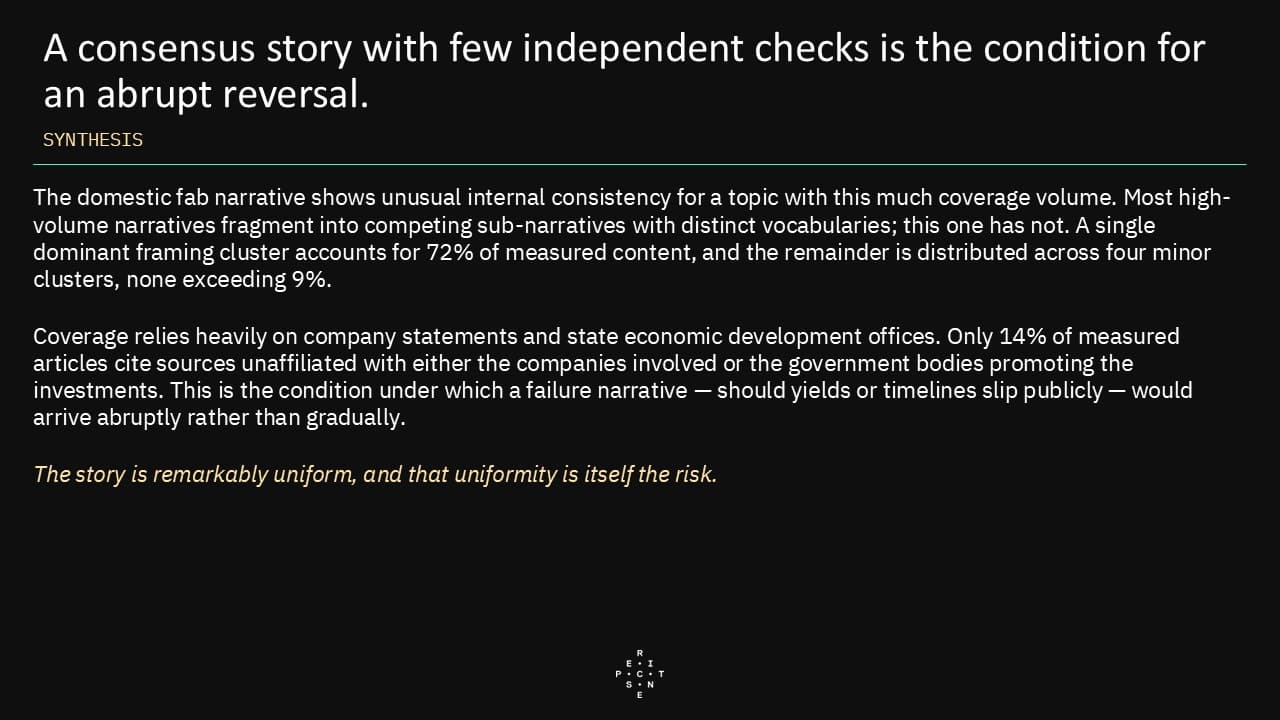
  • The unusual uniformity of the workforce sub-theme looks like a sourcing artifact rather than analytic convergence. Technician shortages are framed as the binding constraint with low variance across outlet types, which is atypical for labor coverage. Read alongside the measurement finding that a single framing cluster accounts for nearly three-quarters of content and that only 14% of articles cite sources unaffiliated with the companies or the promoting governments, the consistency appears to reflect a narrow information supply.
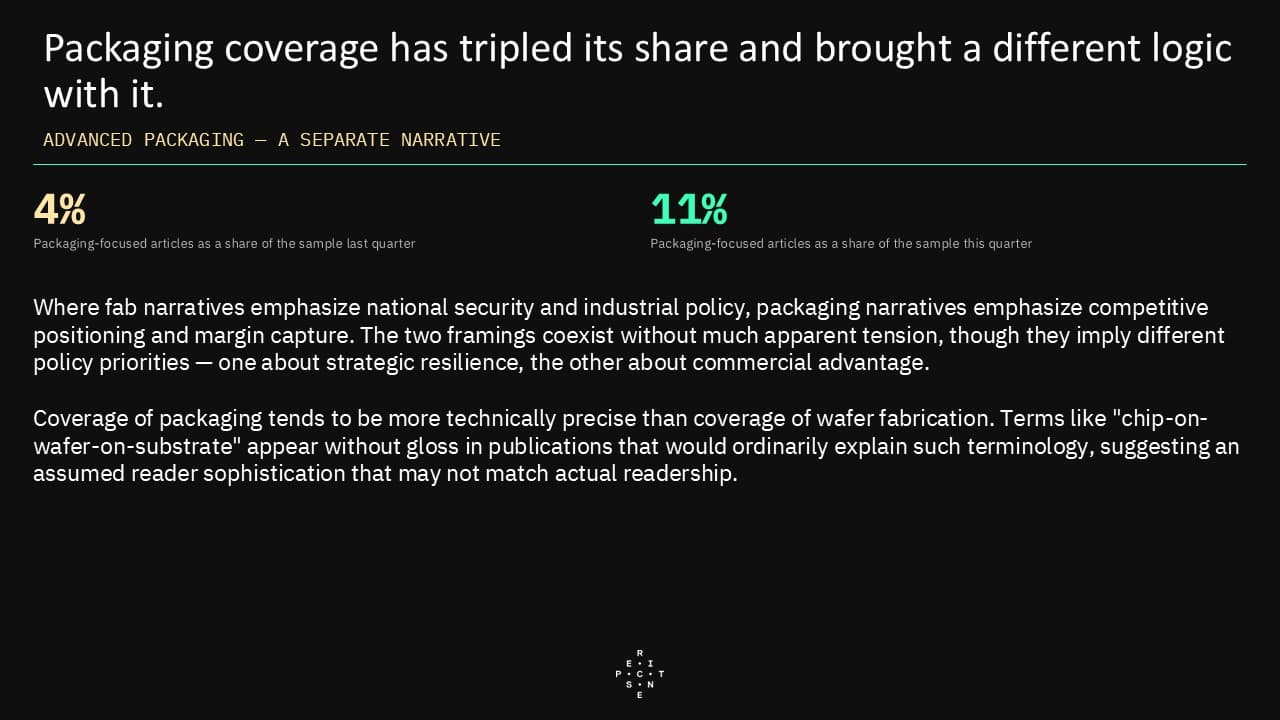
  • Advanced packaging is emerging as a separate narrative with a different logic. Packaging coverage has roughly tripled its share of the sample and emphasizes competitive positioning and margin capture, where front-end fab coverage emphasizes national security and industrial policy. The two coexist without visible friction despite implying different policy priorities, and packaging coverage adopts a more technical register that assumes a reader sophistication that may not match actual readership.
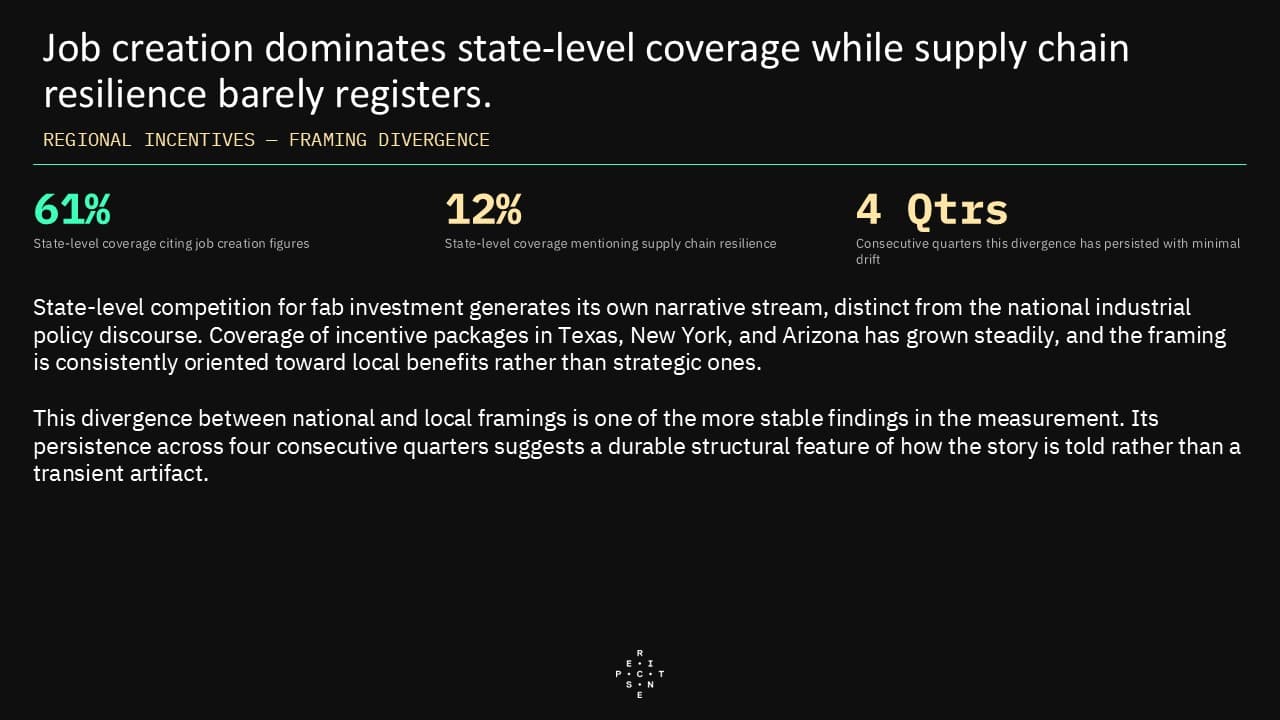
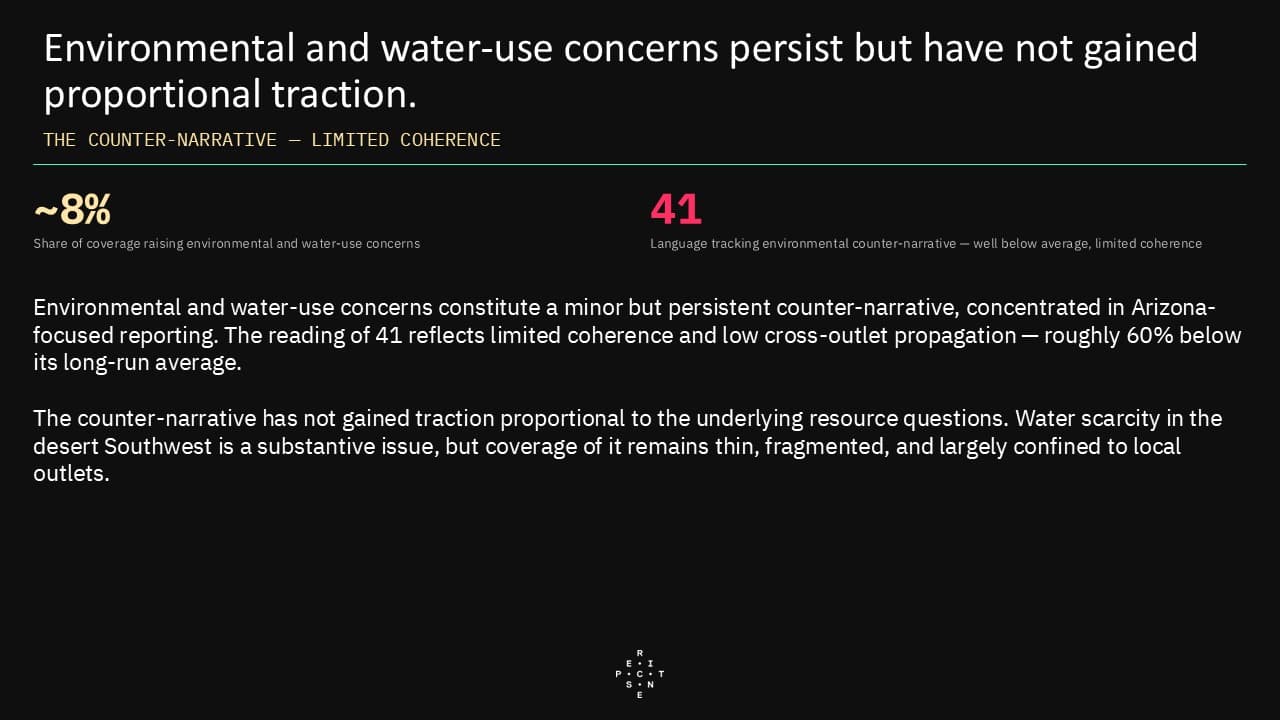
  • National and local framings remain durably split, and the counter-narrative is not gaining ground. Job creation dominates state-level incentive coverage while supply chain resilience barely registers, a divergence stable across four quarters. Environmental and water-use concerns propagate weakly and cohere poorly despite the substance of the underlying resource questions. The combined picture is a consensus story with few independent checks — the condition under which a failure narrative, should yields or timelines slip publicly, would arrive abruptly rather than gradually.

Recent Pulses

Markets PulseWeeklySep 29, 2026

Markets Pulse

Next release: October 06, 2026

AI PulseWeeklySep 29, 2026

AI Pulse

Next release: October 06, 2026
Markets PulseWeeklySep 22, 2026

Markets Pulse September 15, 2026

The regime-change story arrives without any accompanying fear language. Every flight-to-safety signature — Treasurys, Swiss franc, yen, gold, money market funds — sits deep in negative territory, geopolitical and monetary policy uncertainty signatures were flat, and risk-on and risk-off readings have converged to nearly the same level just below zero. Media are narrating a supply shock, a five-percent ten-year, and a first hike since 2023 while conspicuously declining to counsel defensive positioning. Election-season transfer proposals collided with a hardening sovereign-risk story, and media asserted both outcomes at once. The helicopter-money signature registered the largest single move in the file, and stimulus-check predictions rose with it, yet signatures tracking debt paydown, deficit reduction, and austerity legislation also strengthened in the same week, while fiscal policy uncertainty remained flat. Commentators are expressing conviction about incompatible fiscal futures rather than doubt. Simultaneously, signatures tying runaway spending to higher Treasury yields, and those linking bond weakness to deficits and unfunded tax cuts, all gained, and claims that Treasurys are pricing genuine default risk moved into positive territory. Taken together, Sections 1 and 2 describe a media framework in which monetary and fiscal policy are pulling in opposite directions. Coverage pairs a hawkish Fed responding to oil-driven inflation with a proposed trillion-dollar household giveaway, and the reserve-currency channel sharpened alongside it: the signature tying dollar-status threats specifically to debt sustainability rose while the generic version held flat. Claims that White House pressure on foreign Treasury holders is deterring buyers remain the densest reading in the entire file, even as it eased slightly, and official-sector gold substitution language stayed elevated without accelerating further. Tariff politics are running in reverse, and the war has been absorbed into the same affordability argument. The signature tracking broad public opposition to tariffs climbed to one of the highest standings in the file while claims of public support weakened further, and the stated rationale rotated decisively: reshoring-manufacturing arguments dropped hard while "make other countries pay their fair share" and negotiating-leverage framings gained. Directional language turned two-sided for the first time in months. Bridging Sections 1 and 3, voter coverage now treats tariffs and the conflict as a single price story, which the K-shaped-economy framing organizes into a midterm affordability fight — notably, the market version of that bifurcation narrative eased even as chip stocks sold off, and the argument that investors have no alternative to US large-cap growth has effectively vanished from coverage.